|
Amulet Capital has moved US Fertility into a second continuation vehicle, with StepStone as sole lead, five years after the first. The sale process in between found no buyer for the whole company and one for 42.5% of it. Golub Capital has hired a head for the $1 billion it set aside to buy equity in its borrowers' continuation vehicles. A secondaries buyer paid for the holding on in both cases, and it now sets the holding period.
Number of the day 42.5% The stake in US Fertility that Amulet sold to L Catterton last November, half of what it held, ten months before StepStone paid for the rest. |
The tape
- Amulet Capital closed a continuation vehicle for US Fertility with StepStone as sole lead and no terms disclosed.
- Golub Capital named Matt Shafer to run the GP-led strategy it launched in October with more than $1 billion of its own money.
- Forge's August print, published on 10 September and not carried here until today, has its private market index at -0.64% against +5.09% for the cap-weighted Accuidity index.
-
Amulet has sold US Fertility three times and still owns it
Amulet Capital has kept US Fertility through three liquidity events in five years, and a secondaries buyer paid for the third. Amulet's second fund formed the company in July 2020 with Shady Grove Fertility, per the firm's portfolio page. In December 2021 it moved the position into a single-asset vehicle, USF / Stork SPV, which Amulet's own fund list puts at $325 million. In August 2025 Morgan Stanley and Moelis ran a sale, marketed off about $175 million of EBITDA at a mid-teens multiple, according to Mergermarket. No buyer took the whole company.
L Catterton took half of it instead. In November it came in as co-lead investor, buying 42.5% of the company, half of Amulet's stake. A month later Buyouts reported that Amulet was running a CV-on-CV process for the rest. On Monday Amulet said the vehicle had closed, with StepStone as sole lead and existing and new investors behind it. Terms were not disclosed.
| Asset | US Fertility (121 IVF clinic and laboratory locations, 200-plus physicians) | | Sponsor | Amulet Capital Partners, out of USF / Stork SPV (2021, $325m) | | Lead buyer | StepStone Group (sole lead), existing and new investors | | Size | n/a | | Advisor | Evercore and Morgan Stanley (financial), Kirkland & Ellis (Amulet), Debevoise & Plimpton (StepStone) | | Price | n/a | | Rollover | n/a | | Structure | Single-asset CV, the second on the same asset |
The filing says more than the release. Stork 2 SPV, L.P. filed its Form D on 21 August from 1 Greenwich Plaza, Amulet's address, with Jay Rose and Ramsey Frank as officers. The agents are Evercore and Morgan Stanley, and there were no sales at that date. Amulet's fund list shows a "Stork 2" at $610 million with a 2025 date, next to the $325 million Stork SPV of 2021. The most probable reading is that Stork 2 is Monday's vehicle and $610 million is its size. Amulet could also have raised Stork 2 as a co-investment vehicle alongside L Catterton last year, and nothing published rules that out.
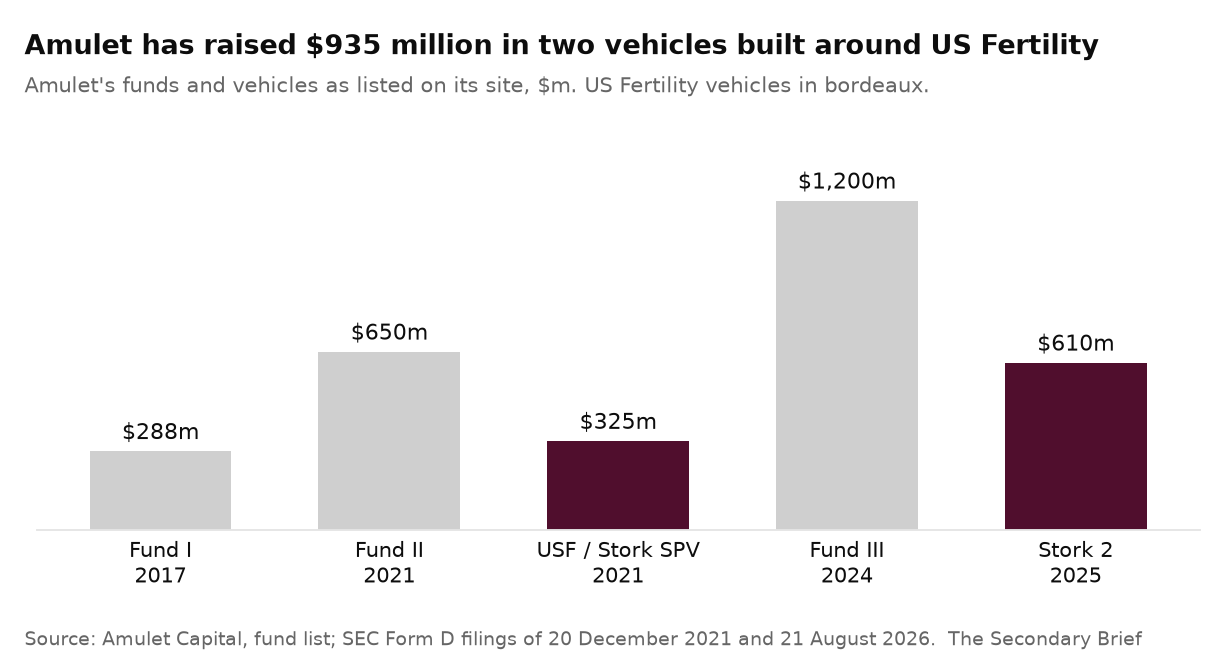 Source: Amulet Capital, fund list; SEC Form D filings of 20 December 2021 and 21 August 2026. |
The investor who rolled from Fund II into Stork SPV in 2021 has now had two election letters on the same company in five years. The second one arrives with a price reference the first lacked, because L Catterton paid for 42.5% of the company ten months ago at arm's length. GLIL did the same at Sølvtrans before Antin's vehicle. A minority sale before the election gives the sponsor's price a check, but it also fixes the mark. So the question for the rolling investor is whether StepStone paid L Catterton's price or a discount to it. StepStone also led Gainline's vehicle last week, where fewer than one in twenty investors stayed, and Amulet's release does not say how many of its own did.
Golub is hiring to buy what it lends against
Golub Capital is building a buyer of continuation-vehicle equity out of a direct-lending book, and it now has someone to run it. On Monday the firm named Matt Shafer head of Golub Equity Continuation Partners, the strategy it launched on 9 October with more than $1 billion of its own capital. Shafer ran capital solutions and US private equity at Northleaf. Until now Greg Cashman, Golub's co-head of direct lending, ran the strategy. Golub lends to more than 650 sponsor-backed companies and has made more than 400 equity co-investments alongside its loans. Private Equity Wire reported in October that outside money would follow in a dedicated fund.
Why a lender wants the equity is in Fitch's numbers, relayed by Private Equity Wire this morning. The default rate across about 1,300 private credit borrowers rose to 6.3% in August from 6.1% in July, a record. Stressed maturity extensions were 45% of August's default events. Healthcare, industrials and manufacturing each ran at 9.9%. A sponsor that cannot sell a company at its price asks the lender for more time. The lender is then in the company for longer than it planned and is paid a lender's return for the wait. A lender that buys the equity in the continuation vehicle instead chooses which companies get the extra years, and it is paid an owner's return for the same wait. Fitch's line reads like Shafer's mandate: "stressed maturity extensions remained the most common form of default for the third consecutive month."
Forge's two venture indexes split by six points in August
The venture secondary market moved two ways in August, and the direction depended on how the index was weighted. Forge's August print, published on 10 September, has the Forge Private Market Index down 0.64% for the month. The cap-weighted Forge Accuidity index rose 5.09%, and Forge says SpaceX's 32.59% rebound carried it. Forge's own summary is that "August was not a broad rally across private companies."
A buyer of a 2021 venture fund interest owns something closer to the broad index. A fund holds twenty or thirty companies, and few of them hold SpaceX. Callan's private equity page in the Alaska Retirement Management Board's packet for today's meeting shows the same split from the pension's side. Venture capital returned 23.3% net over the year to 31 March against 6.8% for buyouts, "led by mega-rounds for OpenAI, Anthropic, and xAI". TrueBridge's $508 million and StepStone's seventh fund were raised this month to buy from venture LPs. They are bidding on portfolios whose median company fell while the quoted index rose 5%.
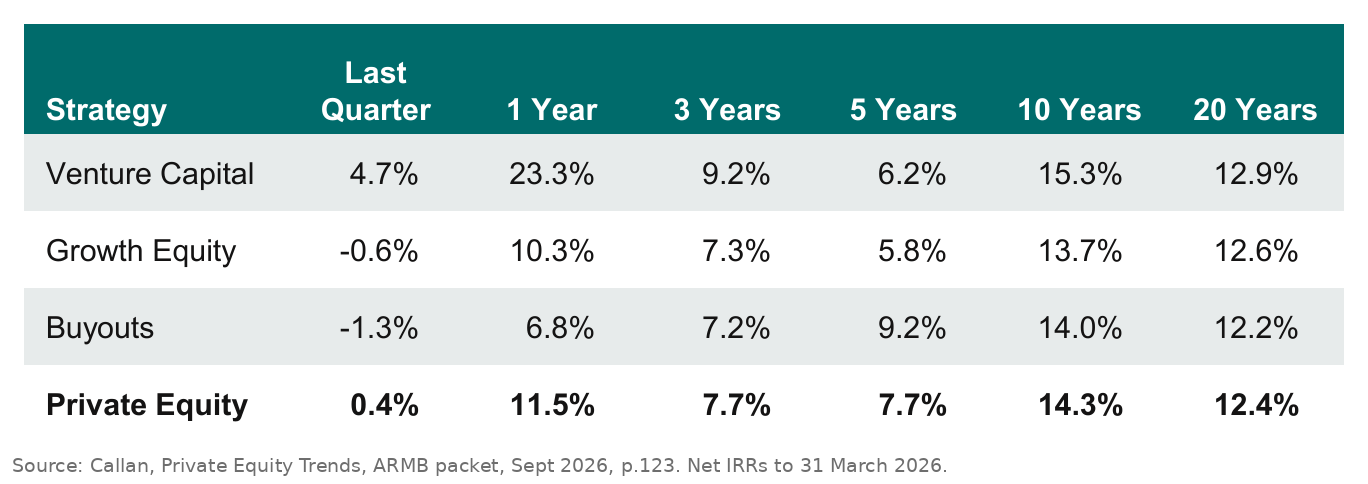 Source: Callan, "Private Equity Trends", ARMB Board of Trustees packet, September 2026, p.123. |
On the radar
- Tuesday 15 and Wednesday 16 September, Anchorage. The Alaska Retirement Management Board meets with private equity at 13.5% of the PERS plan against a 14% target. In the June minutes CIO Zach Hanna says that in real terms assets "are expected to shrink from this point forward". Trustees of a shrinking plan end up selling fund interests.
- Tuesday 15 September, New York. The PDI New York Forum's credit secondaries panel at 2pm meets on the morning of Fitch's 6.3%. The question for it is what a book of extended loans is worth to a buyer paying close to par.
- Thursday 17 September, Olympia. The Washington State Investment Board votes at 11:45 on commitments to Clayton Dubilier & Rice XIII and GTCR XV, the re-ups that put older funds on the secondary market.
- Tuesday 22 September, London. Informa's Global Secondaries Summit has a GP-led session that now has a CV-on-CV to discuss, and a credit session with Fitch's print to answer. ILPA's CV course follows in New York on the 29th, the day before quarter-end.
-
|