|
Nordic Capital is moving companies into a continuation vehicle of close to €2 billion, led by Ardian, HSBC and StepStone, Secondaries Investor reported on Friday afternoon. It is the tenth continuation vehicle reported this week, after Meridiam closed $4.5 billion on Tuesday and Blackstone raised $1 billion for loans on Thursday. Meanwhile, StepStone's sixth secondaries fund has raised $3.1 billion, its first count. The same week, PitchBook counted continuation funds at half of last year's pace.
Since Friday
- DEAL Nordic Capital is raising a near €2 billion multi-asset vehicle led by Ardian, HSBC and StepStone, with CVC Secondary Partners also buying, Secondaries Investor reported.
- DEAL WhiteHorse Finance, a listed lender, is pursuing a $680 million continuation vehicle for its loans with Jefferies advising, PitchBook reported on Friday.
- DEAL Veremark's employees and early investors sold shares in an auction on the LSE's private market, valuing the company above £100 million, SecondaryLink reported.
- FUND StepStone has raised $3.1 billion from 84 investors for its sixth secondaries fund, a first count, after Fund V closed at $7.4 billion in 2024.
- FUND Partners Group launched an evergreen credit fund on Friday that buys credit secondaries beside direct loans, open to institutions and wealth clients.
-
Sponsors raised ten continuation vehicles in one week
Ten continuation vehicles were reported closed, raised or in market this week, and the largest new one is Nordic Capital's. Nordic Capital has invested in the Nordic region since 1989, and it is moving companies into a vehicle of close to €2 billion. The vehicle's leads are Ardian, HSBC and StepStone, and CVC Secondary Partners is also buying, Secondaries Investor reported on Friday. Secondaries Investor expects the close late in the fourth quarter, and it does not say which fund sells or which companies move. The move repeats one of April 2018. Then Nordic Capital put nine companies of its 2008 fund into a €2.5 billion vehicle that Coller led.
The other nine came from every part of the market, and six of them closed. Meridiam closed about $4.5 billion on Tuesday for 15 North American infrastructure assets, with Ares, GIC and Pantheon buying, as read here on Wednesday. Second, Energy Capital Partners closed $834 million for Next Wave on Monday with five anchors, as read on Tuesday. Then Blackstone raised about $1 billion for loans of its Capital Opportunities Fund IV with Allianz Global Investors leading, Bloomberg reported on Thursday. Loans aside, three smaller buyout vehicles closed at Parthenon, M-One and Center Rock, as read on Wednesday and Thursday.
The four in market are Primavera's $1 billion ByteDance vehicle and IMM's Air First fund in Korea, then Nordic Capital's and WhiteHorse Finance's. WhiteHorse is the listed lending company of HIG Capital, whose own Supreme vehicle was read here on 1 October. Its board set up a committee on 15 September to explore "a sale or other corporate transaction". The committee's answer is a $680 million continuation vehicle for its loans with Jefferies advising, PitchBook reported on Friday.
The week's count sits oddly beside the year's. The year's count comes from PitchBook, which found 95 continuation fund deals in the twelve months to 30 September, worth $47.4 billion. Its 2025 count was 161 deals and $97.6 billion. Its analyst Kyle Walters wrote on 5 October that the pace has "all but confirmed" that 2026 will not reach last year's level. His reason is that sponsors can sell to buyers again. Sponsors' sales of companies were 7.9% more in the third quarter than a year earlier, PitchBook counts. So the vehicles that still come are larger and fewer. Meridiam's vehicle alone is a tenth of PitchBook's twelve-month total, and this week's ten vehicles are a tenth of its count.
Chart of the week
Ten continuation vehicles in one week, the eight with a size Closed, raised or in market, 5 to 9 October 2026, $bn | Meridiam North America Core | | | closed Tuesday, ~$2.5bn of new money, Ares, GIC and Pantheon | | Nordic Capital multi-asset | | | in market, Ardian, HSBC and StepStone lead, close late Q4 | | IMM, Air First | | | equity sought, GIC weighing, close targeted by December | | Blackstone Capital Opportunities IV loans | | | raised, Allianz Global Investors lead, per Bloomberg | | Primavera, ByteDance and Ant | | | target, ADIA and Coller in talks at 30% below the mark | | Energy Capital Partners, Next Wave | | | closed Monday, five anchors | | WhiteHorse Finance loans | | | pursued, Jefferies advising, per PitchBook | | Parthenon, NewEdge | | | closed 29 September, Campbell Lutyens advising |
Source: Business Wire, 5 and 6 October; Bloomberg, 6 and 8 October; Seoul Economic Daily, 7 October; Secondaries Investor, 9 October; PitchBook, 9 October; SecondaryLink, 29 September 2026. |
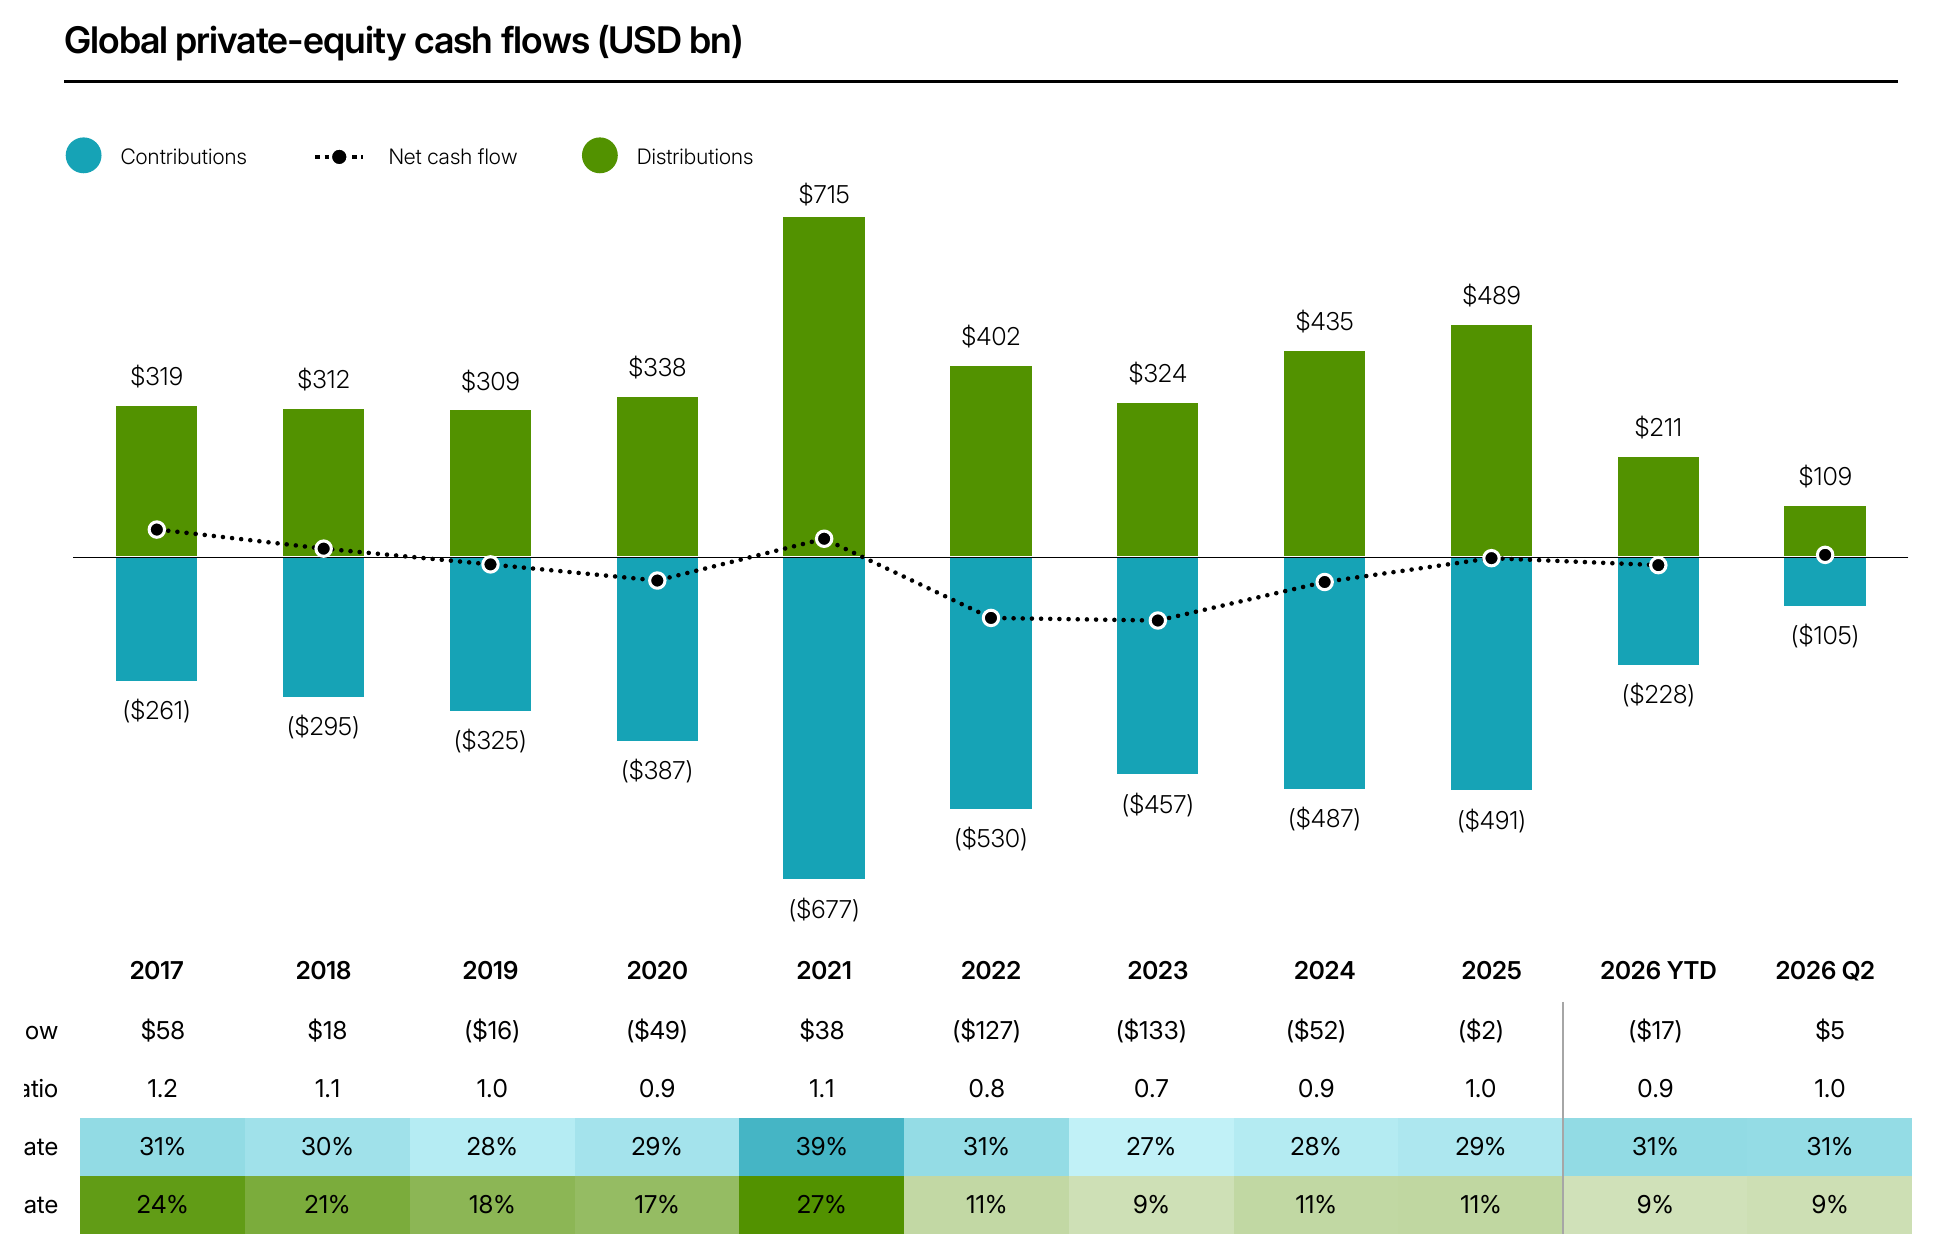
Private equity paid out 9% of its value
Private equity funds paid their investors 9% of their value in the first half of 2026, MSCI counts in benchmarks published this month. MSCI puts that payout rate at 11% for 2025 and calls it "roughly a third of the historical norm" on page 13. MSCI also counts $16.5 billion more called than paid out over the six months. Its authors read the half as "an exit market that is yet to bounce back", even though valuations improved.
Source: MSCI, Private Capital Benchmarks Summary Q2 2026, p.13.
That drought ran through the week's other decisions. The week's largest came on Wednesday, when Partners Group Private Equity's shareholders voted 99.89% to sell its whole €771 million portfolio, as read here on Thursday. Their third-quarter exits had brought in €4.8 million. The same week, holders of Harrison Street's interval fund sold at an auction that cleared 15% below value, as read on Monday. Cox Capital, meanwhile, bid 20% below value for Blue Owl Credit Income shares, as read on Tuesday.
So buyers paid 15% to 20% below value where holders sold this week, and PGPE's holders chose a wind-down with their shares at 40% below. PGPE's wind-down and the auction both wait on distributions, and the next reading of those comes on 22 October, when Blackstone reports its quarter. If Blackstone's realisations have not picked up, the fourth quarter brings more vehicles of the kind it raised this week.
The board
Open offers for evergreen shares
All five bids are Cox Capital's, for Class I shares.
Deals carried in the last two weeks
| Asset |
Buyer |
Size |
| Meridiam North America Core Fund, 15 assets |
Ares, GIC, Pantheon |
~$4.5bn |
| Blackstone Capital Opportunities IV loans |
Allianz Global Investors, StepStone |
~$1bn |
| Next Wave Energy Partners, ECP |
GCM Grosvenor, Phoenix, Ardian, StepStone, North Hudson |
$834m |
| NewEdge Capital Group, Parthenon |
n/a |
$455m |
| Scooter's Coffee, M-One |
Adams Street, Golub |
n/a |
| Power Services Group, Center Rock |
New 2ND Capital |
n/a |
| Awayday, preferred equity |
Warburg Pincus Capital Solutions |
n/a |
| Osaic, Reverence |
Ares Secondaries, Lexington |
>$2bn |
Dates ahead
| Date |
Event |
| Tue 13 to Thu 15 Oct |
SuperReturn Global Infrastructure, London |
| Wed 14 Oct |
Pantheon International's annual meeting, London |
| Wed 14 Oct |
Anthropic briefs institutional investors, San Francisco |
| Thu 15 Oct |
SDCL Efficiency Income Trust's general meeting on Saba's and General Atlantic's directors |
| Wed 21 Oct |
Pomona's 3% repurchase offer expires |
| Thu 22 Oct |
Blackstone's third-quarter call |
| Fri 23 Oct |
Baillie Gifford US Growth Trust's annual meeting on Saba's three nominees |
| Tue 3 Nov |
Cox's offers for BCRED and HLEND shares expire |
| Sat 14 Nov |
Cox's offers for Apollo Debt Solutions and Ares Strategic Income shares expire |
| Fri 4 Dec |
Comments close on the SEC's interval fund proposal |
| Fri 11 Dec |
Comments close on the FCA's 90-day notice proposal |
Seen before the press, the week's finds
Halifax has set up its first continuation vehicle, with William Blair running the sale. HCP Continuation Fund I filed on Friday from the firm's Raleigh address, signed by managing partner Christopher Cathcart, with nothing raised yet. Cathcart's firm, The Halifax Group, was founded in 1999 and buys lower-middle-market companies in health, business services and franchising. Its fourth fund raised $650 million in 2018, and its fifth had raised $445 million from 92 investors by May 2024. The fourth fund is now in its ninth year, so the vehicle is most probably for one or more of its companies. It could also take one from the fifth, and Halifax has announced nothing.
| SEC · Form D | Filed 9 Oct 2026 |
| | HCP Continuation Fund I, L.P. | | Raised | nothing yet | | Size | Open-ended | | Placement agent | William Blair | | Sponsor | The Halifax Group, Raleigh, officers Christopher Cathcart, Scott Plumridge and Arthur High Jr. | | Earlier | Halifax Capital Partners V raised $445m from 92 investors by May 2024 | | Read the filing |
|
On the radar
- Tuesday 13 to Thursday 15 October, London. SuperReturn Global Infrastructure at the Hilton Bankside, the first infrastructure gathering since Meridiam closed its $4.5 billion North America vehicle on Tuesday.
- Wednesday 14 October, 10.30am, London. Pantheon International's annual meeting at Carlton House Terrace, the first since Saba Capital reached 12% of the trust, as read here on Tuesday.
- Thursday 22 October, 9am, New York. Blackstone's third-quarter call, the first since it shelved Eclipse on 24 September and since its $1 billion credit vehicle.
- Friday 23 October, London. Baillie Gifford US Growth Trust's annual meeting votes on Saba's three board nominees. The board says Saba refused an exit at 99.75% of value. The trust holds OpenAI, Anthropic, Stripe and SpaceX.
-
|