|
Shareholders of Partners Group Private Equity voted 99.89% on Wednesday to sell its whole €771 million portfolio, with a first payout due in March 2027. Meanwhile, sponsors won carried interest above the usual tiers in 29% of the single-asset continuation funds that closed in the first half, PJT Partners found. In addition, St James's Place has sold all the private holdings of a £1.4 billion fund to one buyer before winding the fund up.
The tape
- DEAL Center Rock Capital Partners closed on 30 September its first continuation vehicle, for turbine servicer Power Services Group, led by New 2ND Capital.
- FUND Ardian and SMBC launched on Wednesday a NAV financing platform that lends to mid-market buyout and infrastructure funds against their portfolios.
- FUND Collective Global, which buys stakes in venture managers, is seeking up to $1.2 billion for its second fund, SecondaryLink reported.
- LP ICG Enterprise Trust sold no fund positions in the half to July, against £66.3 million a year earlier, and bought back shares 31% below value.
- PEOPLE Simpson Thacher hired six Weil partners on 2 October, among them London secondaries lawyers Simon Saitowitz and Charles Cooper-Isow.
-
PGPE's shareholders voted to sell the whole portfolio
Partners Group Private Equity's shareholders approved the sale of its entire portfolio on Wednesday, with 99.89% of the votes cast and only 46,119 shares against. Partners Group Private Equity, known as PGPE, is a Guernsey fund listed in London since 2007 and worth about £457 million on the market. Its €771 million of net assets sits almost entirely in direct stakes in more than 70 companies that Partners Group invested in. But the shares traded at €6.99 on Tuesday, 40% below the net asset value of €11.58 a share at the end of July.
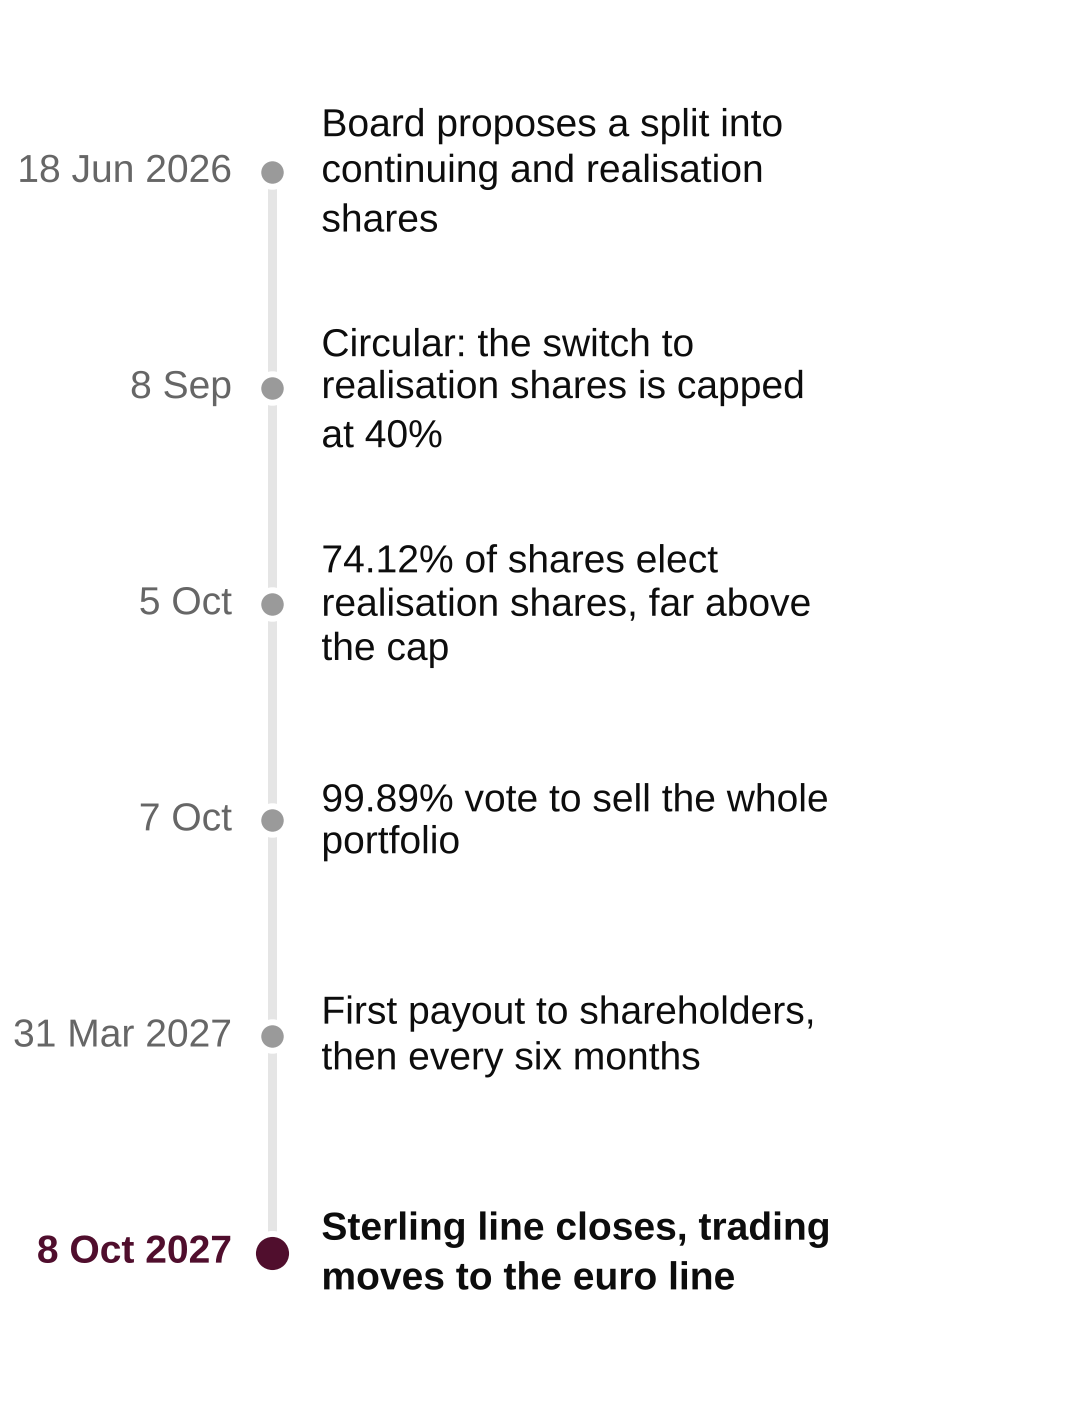
The board offered its shareholders a choice because of that gap. On 18 June it proposed to split the company in two. Shareholders could keep shares in a company that goes on investing, at a fee of 150 basis points a year. They could also switch to realisation shares, which pay back cash as each company is sold, at 125 basis points. The switch was capped at 40% of the shares in the circular of 8 September. The circular said that above the cap the board would ask everyone to wind down the whole company instead. On Monday the company counted 74.12% of its shares for the switch, so the split fell away and Wednesday's vote was on the wind-down alone.
Five months from a split proposal to a full wind-down Partners Group Private Equity, dated events from June 2026 to October 2027
Source: PGPE announcements, 18 June to 7 October 2026.
The vote changes three things, the announcement says. Partners Group will sell each holding "in accordance with the ordinary course business plan for each investment". Then PGPE sends the proceeds to shareholders as payouts rather than reinvesting them. The payouts start on 31 March 2027 and come every six months, more often if the cash allows.
The question for anyone buying at a 40% discount is how fast the exits bring cash. The exits brought PGPE €110.6 million in the first half of the year, the half-year report shows. In the third quarter they brought €4.8 million, against €9.2 million that PGPE put into its companies, this morning's update says. That left no free cash flow for buybacks under the policy of March 2024. So the board approved a discretionary €10 million instead, to be spent by 31 January 2027. The first payout is due by 31 March 2027. The next two quarters, if they look like the third, would leave less than €10 million of exit proceeds to pay out by then.
GPs won super carry on 29% of CVs
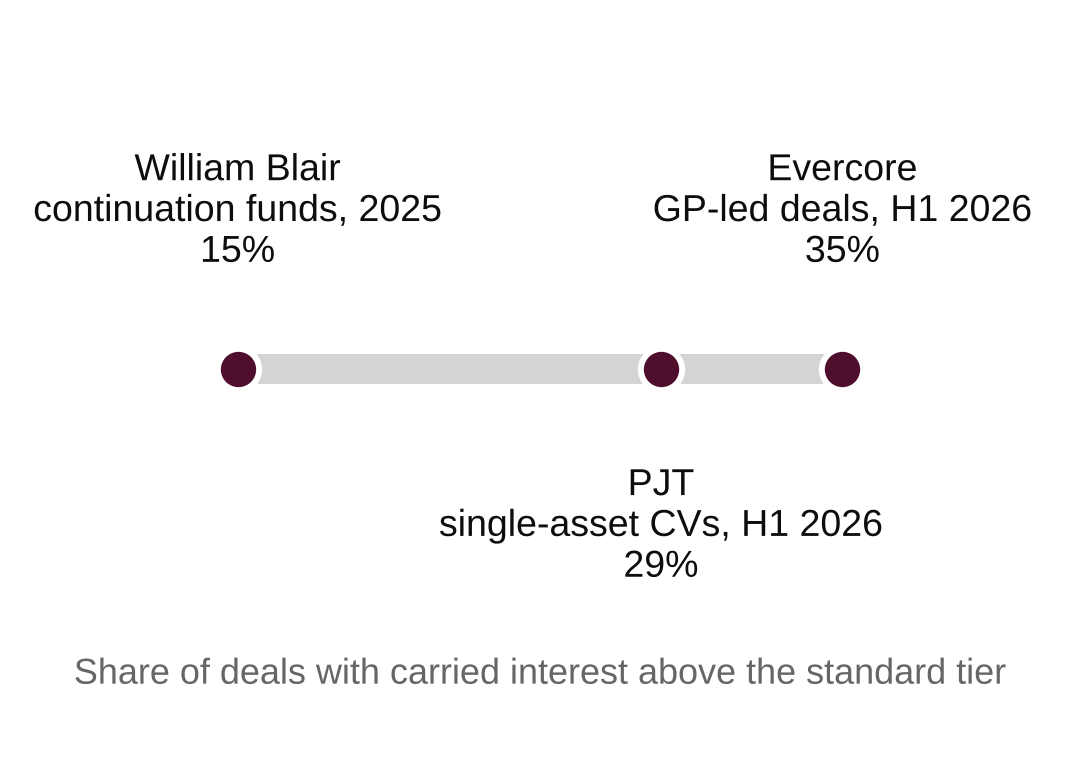
Sponsors won super carry in 29% of the single-asset continuation funds that closed in the first half of 2026, PJT Partners found. PJT's count is almost three times the share of a year earlier, Bloomberg reported on Wednesday. That count covers carried interest above the usual tiers of 12% to 20%, which comes with conditions that vary by buyer. The conditions can be a 30% internal rate of return, a return of three times the money, or both.
The named cases show who gave in, starting with Parthenon Capital, the Boston buyout firm whose NewEdge vehicle closed last week. Parthenon asked for super carry on a new fund holding Kroll Bond Rating Agency. Several of its investors balked at the terms before HarbourVest agreed, and Parthenon then raised more than $1.7 billion for the single-asset vehicle, Bloomberg says. Percheron Capital met the same objections last year on its $1.62 billion fund for Big Brand Tire & Service, and won over Blue Owl, Iconiq and Warburg Pincus. The third case is Lightspeed Venture Partners, which asked for 25% on a $600 million multi-asset fund it is raising. Its lead buyer, Coller EQT, refused, Private Equity Wire reported.
For reference, Evercore found super carry in 35% of GP-led deals by volume in the first half, on page 9 of its review. William Blair found it in 15% of continuation funds in 2025, on page 6 of its survey.
Three advisors count super carry in a growing share of GP-led deals Share of deals with carry above the standard tier, by source and period
Source: William Blair, 2026 Secondary Market Report and Survey, p.6; PJT Partners via Bloomberg, 7 October 2026; Evercore, H1 2026 Secondary Market Review, p.9.
Blue Owl, one of the buyers that accepted, told Bloomberg: "In general, we support structures that align sponsors with investors, paying sponsors more only when investors earn more." One dealmaker estimated to Bloomberg that only a fraction of these agreements will ever pay out.
SJP sold one fund's private book whole
On 29 September St James's Place accepted "an offer to sell all the Fund's private market exposure" of its Diversified Assets fund, its client notice says. St James's Place, known as SJP, is a UK wealth manager, and this fund was less than 0.6% of the money it manages. It suspended the fund the day after the offer. KKR has managed the fund since its launch in 2018, investing in KKR vehicles. The fund held about £1.4 billion when the closure was announced.
Clients had been leaving for three years, and the fund has halved since 2023, the notice says. Over twelve months alone, clients withdrew more than £800 million from the fund, Citywire reported. The fund's private holdings were less than a quarter of it, so the sale covers under £350 million at the last reported size. Neither the buyer nor the price has been disclosed.
After a strategic review, SJP concluded the fund "no longer has a sustainable long-term role" in its range, investments chief Justin Onuekwusi said on 30 September. "This decision should not be interpreted as a change in our view of alternatives," he added. The decision leaves KKR to sell the remaining assets once the FCA approves the closure, which SJP expects within about a month. Until then the fund charge of 1.04% falls to zero, and KKR has waived its fee for the rest of the fund's life. KKR's sales should return the cash to clients before the end of the year, SJP says, and it will write to them again in November.
Seen before the press
General Atlantic, which sold ByteDance stock in February, has set up a new vehicle for Argus Media, the energy-price publisher it moved into a continuation fund in 2021. The vehicle is called GA Continuity II (AM), L.P. and filed its Form D on Wednesday from the firm's New York address. Evercore is its placement agent, and nothing has been raised yet.
Its initials match an earlier filing. In June 2021 General Atlantic filed GA Continuity I (AM) Fund beside sleeves marked HG and SNF. A week later it closed a continuation fund of more than $3 billion for Argus Media, Howden Group, Sanfer and Red Ventures. A second programme, GA Continuity Fund II, filed in October 2024. Since January 2024 General Atlantic has been adding capital to Argus from the 2021 fund, when Hg sold out and Adrian Binks became majority owner. The new partnership most probably carries Argus from the 2021 fund into the second programme, five years on. It could also be a co-investment sleeve for that extra capital, and nothing has been announced.
| SEC · Form D | Filed 7 Oct 2026 |
| | GA Continuity II (AM), L.P. | | Raised | nothing yet | | Size | Open-ended | | Placement agent | Evercore Group | | Sponsor | General Atlantic, New York, officers William Ford, Gabriel Caillaux, David Hodgson and three others | | Earlier | GA Continuity I (AM) Fund, June 2021, before the $3bn continuation fund for four companies | | Read the filing |
|
On the radar
- Tuesday 13 to Thursday 15 October, London. SuperReturn Global Infrastructure at the Hilton Bankside, the first infrastructure gathering since Meridiam closed its $4.5 billion North America vehicle on Tuesday.
- Wednesday 14 October, London. Pantheon International's annual meeting at Carlton House Terrace, the first since Saba Capital reached 12% of the trust, as read here on Tuesday.
- Thursday 15 October, 2pm, London. SDCL Efficiency Income Trust's general meeting votes on seating Boaz Weinstein of Saba and Richard Pavry of General Atlantic as directors. Its two largest holders would then review the sale of its portfolio.
- Thursday 22 October, 9am, New York. Blackstone's third-quarter call, the first since it shelved Eclipse on 24 September. Eclipse was a $3 billion securitization of about 700 fund interests.
-
|