|
Hamilton Lane asked the SEC on Wednesday to let five evergreen funds holding $7.7 billion issue shares that trade on an exchange. Meanwhile, Blackstone has raised about $1 billion for a credit continuation fund, Bloomberg reported on Thursday. In addition, the FCA proposed 90 days' notice and monthly dealing for UK retail funds that hold mostly illiquid assets. Its proposal came nine days after St James's Place suspended one such fund and sold its private holdings.
The tape
- DEAL Neo Secondaries and Kenro Capital are negotiating to buy ₹4 billion of SK Finance from Norwest and TPG, read here on 25 September, Mint reported.
- FUND Pomona Capital has raised $2.36 billion of a $3 billion target for Fund XI from 90 investors, after its evergreen's offer read here on Monday.
- LP Saba Capital, at 12% of Pantheon International as read here on Tuesday, cut its NBPE stake to 5.1% on 6 October from 8%.
- DATA Partners Group may split its $14.4 billion US Master Fund as it proposed for Global Value, whose third-quarter requests hit the 5% cap, Bloomberg reported.
- DATA Firmus, the Nvidia-backed AI data center operator, shelved its $5 billion Australian listing on Thursday and will raise money privately instead, Reuters reported.
-
Hamilton Lane wants its evergreens on an exchange
Hamilton Lane asked the SEC on Wednesday to let five of its evergreen funds issue a class of shares that trades on a stock exchange. The same application asks for a second class recorded on a blockchain. Its five funds held $7.7 billion at 30 June, led by the Private Assets Fund at $6.5 billion. Among them is the Private Secondary Fund, which buys fund interests and backs GP-led deals. Hamilton Lane, based in Pennsylvania, runs 12 such evergreen funds with about $18 billion. It also passed $430 million for its first GP-led fund, as read here on Wednesday.
Five Hamilton Lane funds would get a listed class Net assets at 30 June 2026, $m, from each fund's quarterly holdings report | Private Assets Fund | | | tender fund, the largest of the five | | Private Secondary Fund | | | tender fund, LP and GP-led secondaries | | Venture Capital & Growth Fund | | | tender fund | | Private Infrastructure Fund | | | interval fund since April 2026 | | Credit Income Fund | | | interval fund, launched April 2026 |
Source: SEC Form N-PORT filings of 28 August 2026, Hamilton Lane release of 22 April 2026. |
Today each of the five funds buys back shares once a quarter at net asset value. Between those buybacks, a holder who wants out has no one to sell to. Two of those funds are interval funds, which must offer to buy at least 5% of their shares every quarter. The other three run tender offers. In June the Private Assets Fund offered to buy back up to $290 million, and its holders tendered $77.5 million, all of which it paid. So the request does not answer a queue but adds an exit.
The SEC allowed the same exit for one fund last month. On 24 August it published its notice on ARK's request to list and tokenize classes of its venture interval fund, as read here on 16 September. The order came on 21 September, Hamilton Lane's filing says. Hamilton Lane's lawyers at Simpson Thacher wrote the new application on the same lines. It covers the five funds and any fund the firm launches later.
The listed class would be sold onto the exchange in at-the-market offerings, without a sales charge. Each fund would then publish its net asset value every business day. In addition, the tokenized class would trade on alternative trading systems, and the ordinary classes could be tokenized too, for "peer-to-peer transactions between whitelisted wallets". Such trading "will enhance shareholder liquidity", the filing says. It gives holders "the option to sell their shares on an Exchange rather than waiting for a quarterly repurchase option".
Holders who take that exit would pay a discount. That discount would narrow as the next buyback approaches, the filing expects, with listed shares "naturally pricing in a liquidity discount" in between. For reference, the discount was 15% at Harrison Street's interval fund auction last month, as read here on Monday. In London, meanwhile, Partners Group Private Equity's shares stood 40% below its value on Tuesday, as read here on Thursday.
The SEC must now publish a notice and wait for hearing requests, which took four weeks for ARK. Then a yes gives the five funds a share price beside their net asset value, and a no leaves their holders with the quarterly buyback.
Blackstone raised $1 billion for a credit vehicle
Blackstone has raised about $1 billion for a credit continuation fund, Bloomberg reported on Thursday. Allianz Global Investors is the lead buyer and StepStone is also a buyer, Bloomberg says, citing people familiar with the deal. The vehicle holds assets of Blackstone Capital Opportunities Fund IV, an opportunistic credit fund that finished raising in 2022. The raise comes two weeks after Blackstone stopped marketing Eclipse, as read here on 24 September. Eclipse was a $3 billion securitization backed by about 700 fund interests, and its bond investors objected to the age of those funds. So a vehicle for loans raised money where a vehicle for old fund interests could not.
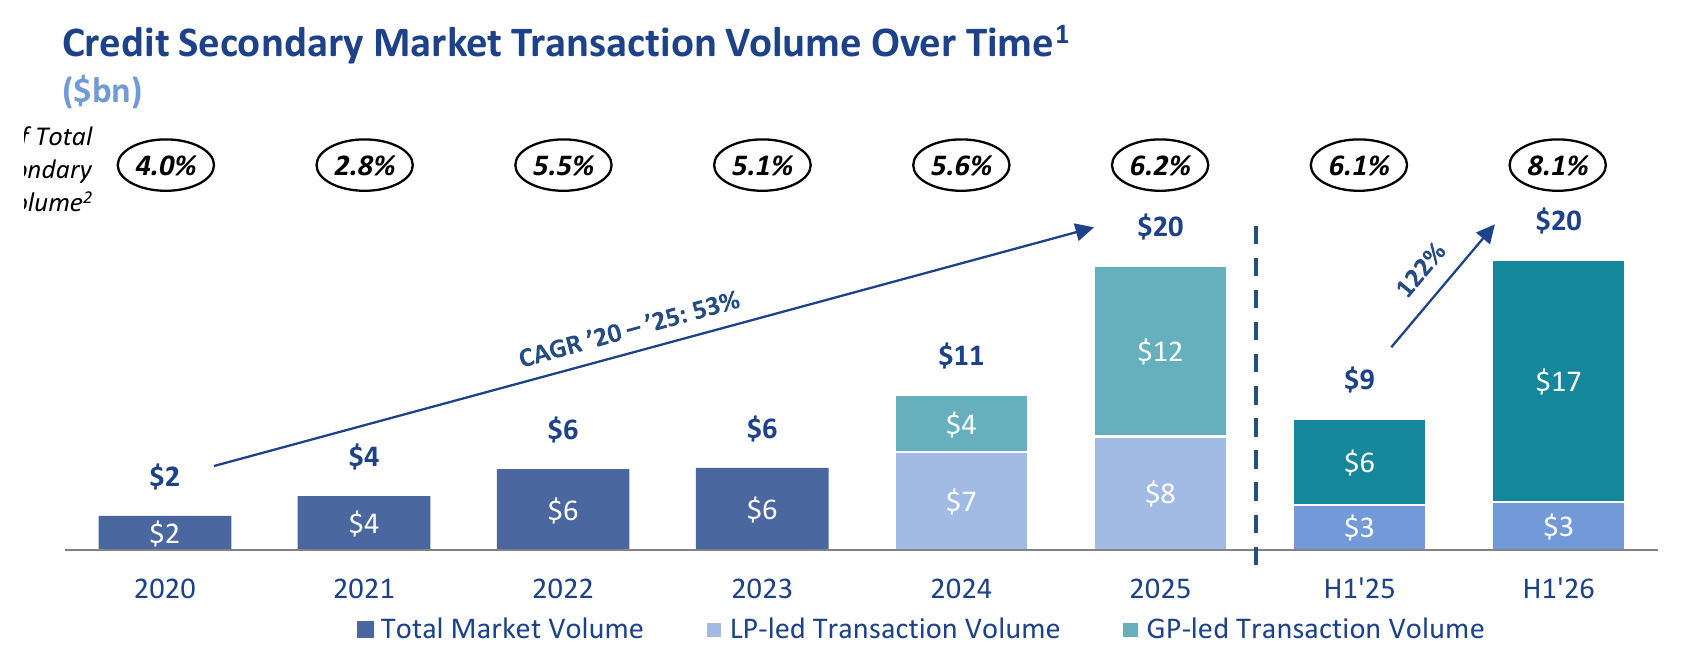
Blackstone's vehicle lands in what Evercore calls the strongest first half on record for credit secondaries. For reference, Evercore counts $20.4 billion of credit secondaries in the first half of 2026, on page 2 of its July review. That volume is 122% more than a year earlier and already more than all of 2025. Of that volume, GP-led deals made 83%. Also, prices held, with "high-quality first-lien portfolios" still trading "in the high 90s as a percentage of FMV", the review says.
Source: Evercore, H1 2026 Credit Secondary Market Review, p.3.
| Deal card | October 2026ANNOUNCED |
| | Blackstone Capital Opportunities Fund IV assets, credit continuation fund | | | Structure | Credit continuation fund | | Sponsor | Blackstone | | Selling fund | Blackstone Capital Opportunities Fund IV (2022) | | Lead buyer | Allianz Global Investors | | Co-investors | StepStone Group | | Size | ~$1bn, per Bloomberg |
|
Blackstone joins a line of large lenders moving loans into vehicles they keep managing. First, KKR filed on 5 October for a Hudson vehicle beside two partnerships named after its third middle-market lending fund, as read here on Wednesday. Second, Partners Group is preparing a vehicle of about €800 million for loans held by five of its own funds, as read here on 21 September. Evercore expects BDCs, interval funds and other semi-liquid vehicles to supply about 25% of this year's volume. They will sell, it says, as "redemption activity, share-price pressure, and liquidity needs create additional secondary opportunities". Neither the price nor the share of the fund's investors who rolled has been reported. Blackstone's next word on its own vehicles comes at its third-quarter call on 22 October.
FCA proposes 90 days' notice for illiquid funds
The FCA, the UK's markets regulator, proposed on Thursday that retail funds holding mostly illiquid assets give investors 90 days' notice and deal no more than once a month. The rule covers non-UCITS retail schemes with at least half their money in assets that take months to sell, such as property. It "only affects a small number of funds", the FCA says. Funds of alternative funds with limited dealing would fall under it too, whatever share of illiquid assets they hold, the consultation says.
St James's Place ran one of those funds. Its Diversified Assets fund, a fund of alternative funds that KKR managed, lost more than £800 million to withdrawals in twelve months. On 29 September it accepted an offer for all its private holdings and suspended dealing the next day, as read here on Thursday. Daily-dealt funds of that kind risk "suspensions or forced asset sales that can depress market prices", the FCA says. So the notice period is meant to give managers time to sell in an orderly way.
The FCA first consulted on notice periods in 2020, for property funds only. It paused then because the distribution system "was not equipped to accommodate funds with notice periods". This time the rule would take at least 90 days' notice and monthly dealing at most, with the right to defer requests above a limit to the next month. A manager whose assets take longer than 90 days to sell would have to set a longer period. Otherwise the FCA "would not expect to authorise it with a 90-day notice period". Under that rule, existing funds would get two years to change their terms, and they must give investors a year's notice.
Comments are due by 11 December, and the FCA expects final rules in the first half of 2027, so an existing fund would have until 2029 to comply. Michelle Beck, the FCA's director of markets, said: "Funds should be clear about whether they offer quick access or are built for longer-term investments like property."
Seen before the press
Framework Venture Partners has set up a continuation vehicle with UBS as placement agent. Framework Venture Partners CV 2026 LP filed its Form D on Wednesday from the firm's Toronto address, signed by Peter Misek, with nothing raised yet. Framework is a Toronto venture firm that Misek and Andrew Lugsdin founded in 2018. Its first fund raised $100 million of a $150 million target in 2019 to back Canadian software companies. The vehicle is most probably a continuation fund for holdings of that 2019 fund, with UBS running the sale to secondary buyers. It could also be a vehicle for one company, and Framework has announced nothing.
| SEC · Form D | Filed 7 Oct 2026 |
| | Framework Venture Partners CV 2026 LP | | Raised | nothing yet | | Size | Open-ended | | Placement agent | UBS | | Sponsor | Framework Venture Partners, Toronto, officers Peter Misek, Ajay Gopal and Jean-Michel Texier | | Earlier | the first fund raised $100m of a $150m target in 2019 | | Read the filing |
|
On the radar
- Tuesday 13 to Thursday 15 October, London. SuperReturn Global Infrastructure at the Hilton Bankside, the first infrastructure gathering since Meridiam closed its $4.5 billion North America vehicle on Tuesday.
- Wednesday 14 October, 10.30am, London. Pantheon International's annual meeting at Carlton House Terrace, the first since Saba Capital reached 12% of the trust, as read here on Tuesday.
- Thursday 15 October, 2pm, London. SDCL Efficiency Income Trust's general meeting votes on seating Boaz Weinstein of Saba and Richard Pavry of General Atlantic as directors, as read here on Thursday.
- Thursday 22 October, 9am, New York. Blackstone's third-quarter call, its first since shelving Eclipse on 24 September.
-
|