|
Ninety-four percent of the secondary investors William Blair surveyed expect LP-led prices to stay stable, the bank wrote on 7 October. Its forecast for 2026 volume rose to $252 billion from $250 billion in March. Hollyport, meanwhile, has raised $1.5 billion for its latest GP-led fund, and Goldman Sachs has filed to register a venture secondaries fund. On Wednesday, Pantheon International holds its first annual meeting since Saba Capital reached 12%.
Buyers want LP portfolios before December
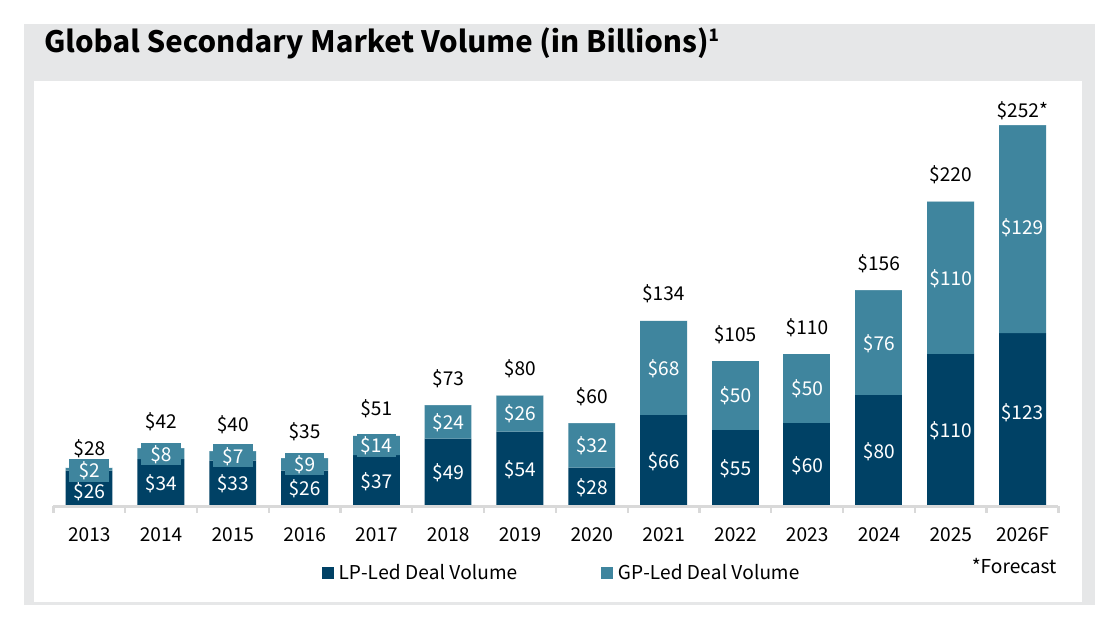
Secondary buyers expect prices to hold and want more fund portfolios to bid on before the year ends. William Blair gives that message in a newsletter published on 7 October. William Blair is a Chicago investment bank that advises on continuation funds and portfolio sales. Its March report forecast $250 billion of secondary volume for 2026. A second survey this summer, of 61 people the bank calls market insiders, lifted that forecast to $252 billion. The chart below splits that forecast into $123 billion of LP-led and $129 billion of GP-led volume, against $220 billion in 2025.
Source: William Blair, Private Capital Advisory Quarterly Newsletter Q3 2026, p.1.
Of the buyers it surveyed, 94% expect LP-led pricing to stay stable, and 98% expect GP-led valuations to hold for six months. In addition, the bank's own gauge now puts LP-led sellers at "slightly motivated", because pricing improved compared with the spring. Meanwhile the sponsors' marks "have come down since the spring", the bank writes. Those marks matter because a buyer bids on the cash it expects back. The mark is only the sponsor's estimate, so a lower mark turns the same bid into a smaller discount.
Supply is the problem, since the LP-led market "has been slower since the spring" and many of the recent sales were tail-end or clean-up portfolios, the bank writes. Buyers are "eager for additional supply and a new wave of scaled sales". "The fourth quarter of 2026 might be a good time to launch a deal, which is not always the case", the bank writes. Its reason is that buyers "are still working to meet their deployment targets".
However, software is the caveat, because portfolios with a large share of software and technology have been "harder to execute", and some buyers pass on them or wait. On that software limit, PitchBook reported on 1 October that buyers' tolerance had risen. That tolerance is "getting closer to 35-40%" of a portfolio, against under 20% after the software sell-off, Nick Best of Campbell Lutyens told PitchBook.
Other advisors forecast more volume than William Blair, and the bars below set the five houses side by side.
Five advisors' forecasts for 2026 secondary volume Full-year forecast, $bn, with the date of the report | Lazard | | | 12 August, interim report | | Jefferies | | | 14 July, half-year review | | Evercore | | | 15 July, half-year review | | William Blair | | | 7 October, summer survey | | Campbell Lutyens | | | 26 August, at least $250bn |
Source: Lazard, Interim 2026 Secondary Market Report, p.3; Jefferies, H1 2026 Global Secondary Market Review, p.3; Evercore, H1 2026 Secondary Market Review, p.21; William Blair, PCA Quarterly Newsletter Q3 2026, p.1; Campbell Lutyens, 1H 2026 Secondary Market Overview, p.3. |
The sellers who can test the bank's advice this quarter include Korea Investment Corporation. It hired PJT Partners in September to sell more than $1 billion of fund interests. On 5 October it was evaluating offers, as read here on Monday. If KIC sells this quarter, its sale is the first billion-dollar test of the bank's advice. If it does not, the quarter's LP-led supply stays the tail-end portfolios the bank describes.
Since Friday
- FUND Hollyport, the London tail-end specialist, has raised $1.5 billion for its latest fund for GP-led deals, Secondaries Investor reported on 8 October.
- FUND Goldman Sachs filed on Thursday to register G-X Venture Capital & Growth, an unlisted fund that buys venture fund interests, direct secondaries and continuation vehicles.
- FILING VanEck and Brookmont filed to register two funds for pre-IPO shares, a Private Growth Fund on Friday and an AI interval fund on Wednesday.
-
On the radar, the week of 12 October
- Tuesday 13 to Thursday 15 October, London. SuperReturn Global Infrastructure at the Hilton Bankside, the first infrastructure gathering since Meridiam closed its $4.5 billion vehicle with Ares, GIC and Pantheon on 6 October.
- Wednesday 14 October, 10.30am, London. Pantheon International's annual meeting at Carlton House Terrace, the first since Saba Capital reached 12% of the trust. The trust sold 42 fund positions in May at 8.1% below their June 2025 value.
- Wednesday 14 October, San Francisco. Anthropic briefs institutional investors at its headquarters, Bloomberg reported on 1 October, relayed by Briefs, with formal marketing possible from the week of 9 November. The listing prices the pre-IPO shares that trusts such as Baillie Gifford US Growth hold.
- Thursday 15 October, 2pm, London. SDCL Efficiency Income Trust's general meeting votes on seating Boaz Weinstein of Saba and Richard Pavry of General Atlantic as directors. A yes puts its two largest holders on the board that reviews a sale of its portfolio.
-
|