|
Six buyers have lined up for Bain Capital's $2.5 billion continuation vehicle for ITP Aero, a company Bain bought for €1.8 billion and recapitalized last November. Morgan Stanley has hired the co-heads of Baird's secondaries advisory, four months after losing its own head to JPMorgan. Meanwhile Hawaii's consultant has put three portfolios in front of the trustees, and all three hold less private equity. One more seller is being told it owns too much.
Number of the day 46% The share of Hawaii's $26.6 billion pension in illiquid classes today, which Meketa's three options would take to 41% to 43%. |
The tape
- Six buyers have lined up on Bain Capital's $2.5 billion continuation vehicle for ITP Aero, the Spanish engine maker it carved out of Rolls-Royce, Secondaries Investor reported on Wednesday.
- Amundi completed its purchase of a 9.9% stake in ICG for about €620 million on Thursday. The first product of their wealth distribution deal is a private equity secondaries fund due "in the coming weeks."
- Morgan Stanley has hired the co-heads of Baird's secondaries advisory, Secondaries Investor reported on Wednesday night, after senior departures from its own team this year.
- HarbourVest named Tony Ranaldi, formerly of Sixth Street, to run portfolio management for its private credit evergreens, which include credit secondaries.
- Hawaii's $26 billion pension is rethinking a decade-long tilt to private markets, Buyouts reported on Thursday.
-
Six buyers want a company that already paid Bain a dividend
Bain Capital is asking six buyers to pay more for ITP Aero than the whole company cost it four years ago. Secondaries Investor reported on Wednesday that six buyers have lined up on a $2.5 billion continuation vehicle for the engine maker, with Evercore advising. The names in the frame are BCI, CVC, Goldman Sachs Asset Management, LGT, Warburg Pincus, Neuberger Berman and Carlyle.
The price has moved three times since the purchase. Bain agreed in September 2021 to buy ITP Aero from Rolls-Royce at an enterprise value of €1.8 billion. In August 2023 Indra paid €175 million for 9.5%, which valued the company at about €1.84 billion. Then in November 2025 ITP Aero refinanced a $1.1 billion term loan and added a $450 million one. Paul Weiss, which advised, says the proceeds "will support a dividend distribution to Bain Capital." The company earned it, because its 2025 results show revenue of €1.88 billion, up 17%, and EBITDA of €379 million, up 28%.
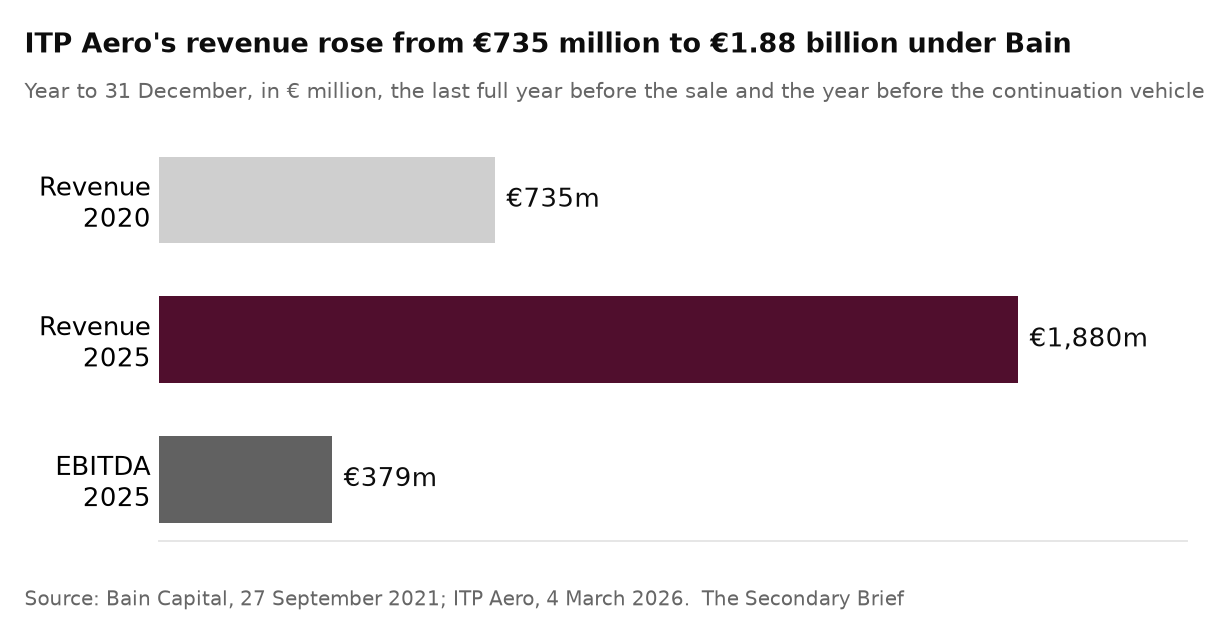 Source: Bain Capital, 27 September 2021; ITP Aero, 4 March 2026. |
| Asset | ITP Aero (aero-engine modules and MRO, €1.88bn revenue in 2025) | | Sponsor | Bain Capital Private Equity, with SAPA, JB Capital and Indra as minority holders | | Lead buyer | six buyers, among BCI, CVC, Goldman Sachs AM, LGT, Warburg Pincus, Neuberger Berman and Carlyle | | Size | $2.5bn | | Advisor | Evercore | | Price | n/a | | Rollover | n/a | | Structure | Single-asset CV |
For the buyer pricing this vehicle, the order of events is the reverse of Kelso, where the vehicle paid off the preferred holder on Wednesday. At ITP Aero the sponsor took its dividend first, out of $1.55 billion of term loans, so the buyers are writing equity into a company that carries that debt. The size then says how much of the bet is growth, because ITP Aero plans €600 million a year of capex by 2030 and as much again of research. The syndicate is being asked for $2.5 billion against an entry price of €1.8 billion.
Morgan Stanley rebuilds with Baird's two co-heads
Morgan Stanley is rebuilding its secondaries advisory by hiring the two people who built Baird's. Secondaries Investor reported late on Wednesday that the bank has hired the co-heads of Baird's secondaries advisory, after senior departures from its own business this year. The largest of those was Will Boyle, its global head of private capital advisory for nearly five years. He went to JPMorgan in May to run secondary advisory, according to Reuters relayed by Investing.com. JPMorgan's Keith Canton put the market at "$200 billion to $225 billion in size, with the general partner-led portion close to $100 billion."
Baird's group is small and recent, which is why two names are most of it. Baird created its GP Solutions group in December 2022 with two co-heads. Alex Mejia had run secondary market advisory at Goldman Sachs, and Jeremy Duksin had run capital solutions in Credit Suisse's private fund group. A year ago the traffic ran the other way, because Baird hired Thomas Vermeiren from Morgan Stanley's private capital advisory team. Alternatives Watch reported then that the group had closed 15 GP-led deals for more than $5 billion since the start of 2024.
The reason banks keep paying for the same dozen people is in Canton's number. A GP-led market of close to $100 billion a year pays a fee on every vehicle, but the sponsor hires the banker who ran its last process. So a co-head who leaves takes the next Saviynt with him, the $600 million vehicle Baird advised last week.
Meketa's three portfolios for Hawaii all hold less private equity
Hawaii's pension is being told that its private markets kept it out of a ten-year bull market, and every fix on the table takes private equity down. Meketa's study is in the packet for Monday's board meeting. It says the ERS "did not benefit as much as peers in the Public Equity bull market of the last 10+ years." Its illiquid targets "represent the largest driver of peer relative return differences." The fund returned 9.2% in the year to June against 14.3% for its peer median, and Buyouts reported the rethink on Thursday.
The three options Meketa put in front of the trustees all move the same way. Private equity goes from a 19% policy target, and 19.6% held, to 17%, 16% or 17%. Public equity goes from 20% to 25%, 28% or 32%, so the illiquid classes fall from 46% of the fund to between 41% and 43%. Meketa also cut its expected return for private equity from 9.8% to 9.0% in May, citing "pricing and distribution/liquidity challenges." The study concludes in October, when Meketa returns "with refined portfolio allocation options" for adoption.
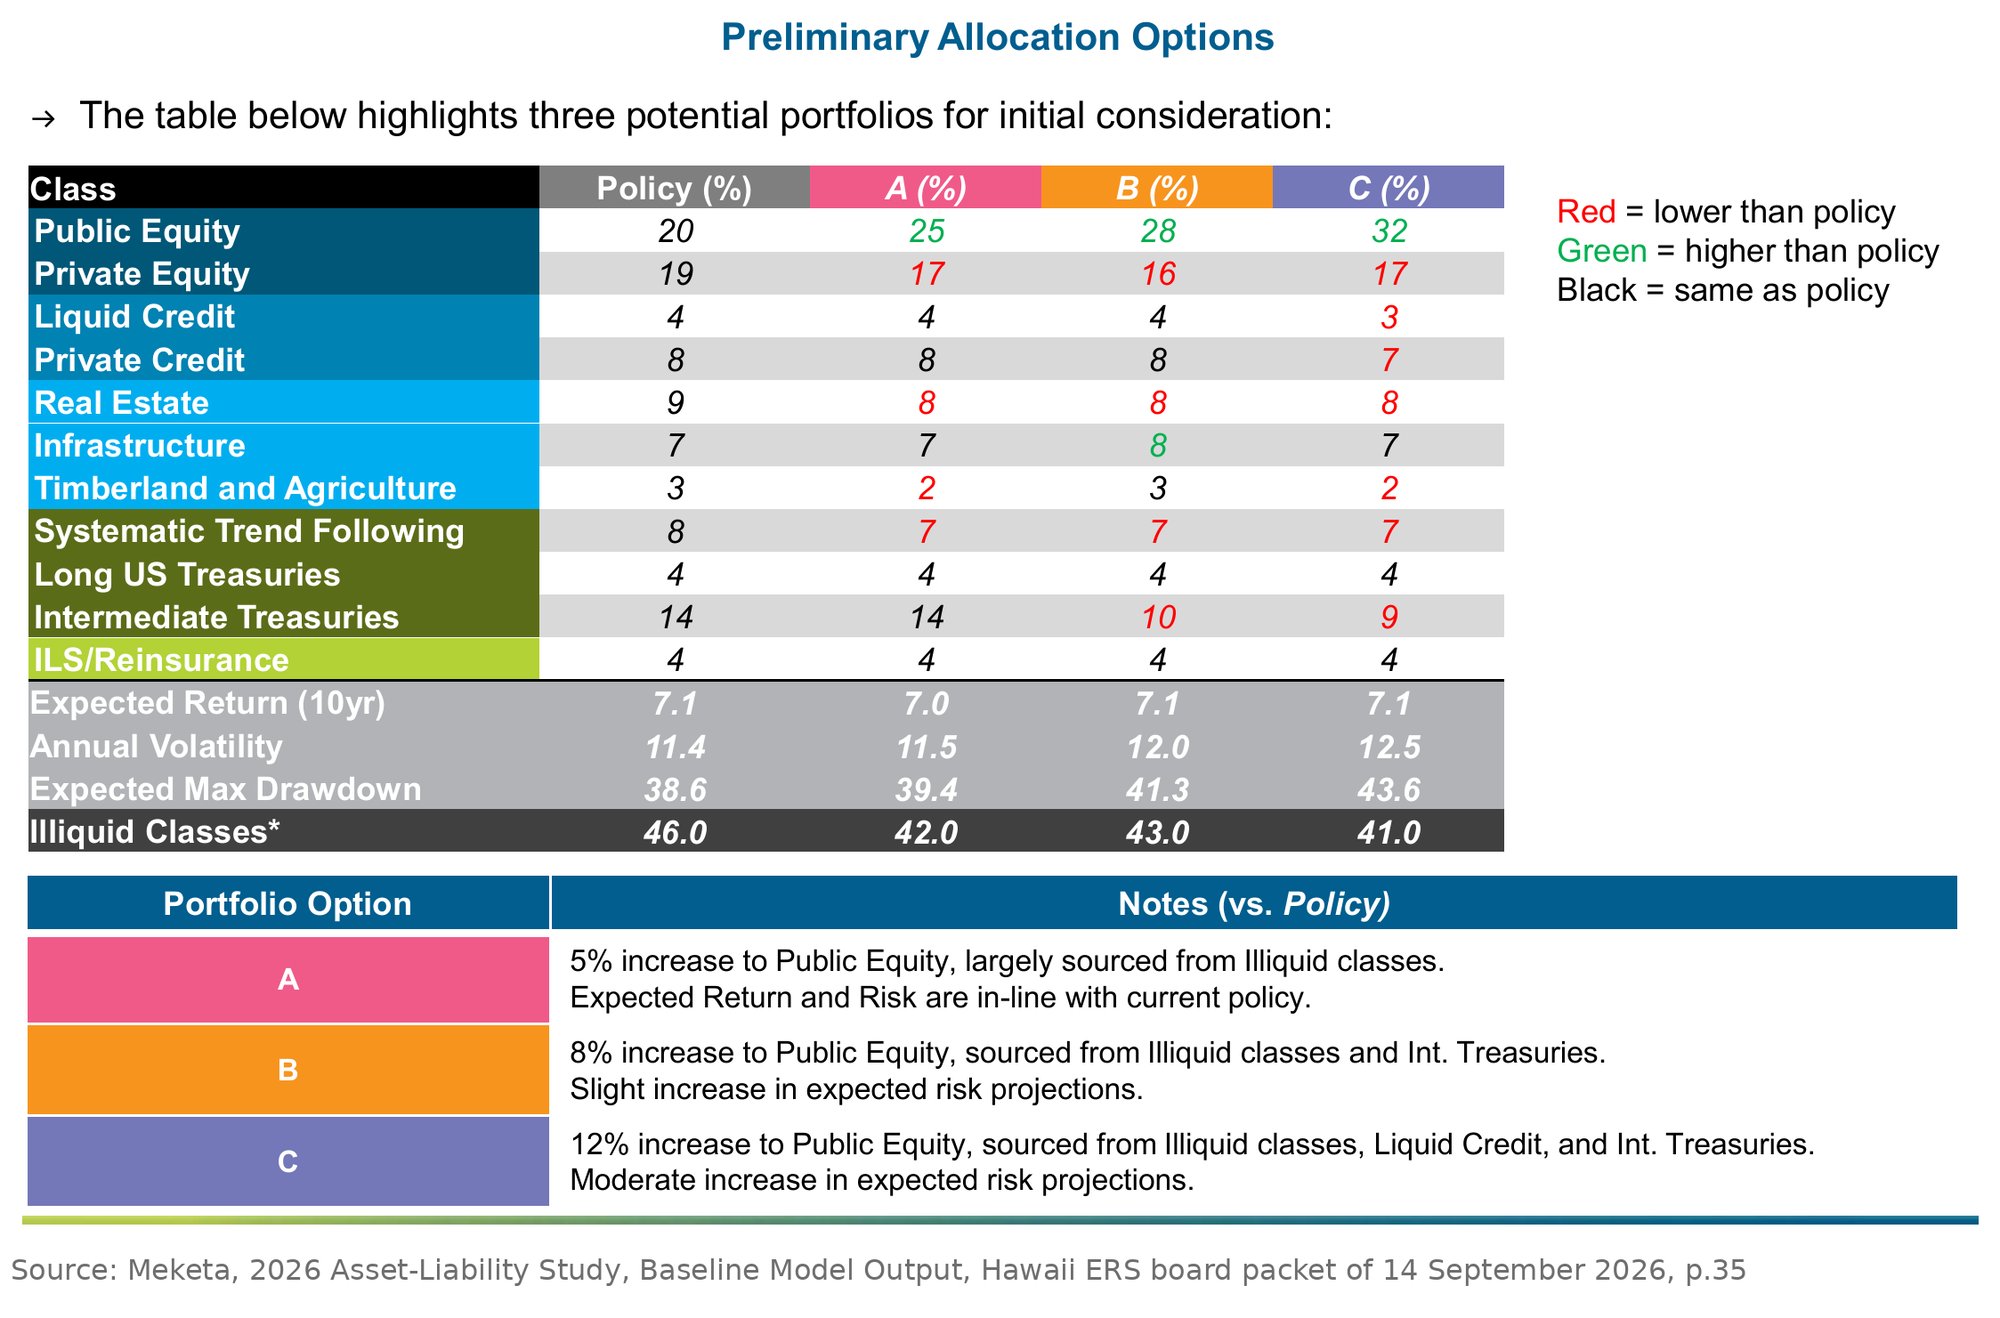 Source: Meketa, 2026 Asset-Liability Study, Baseline Model Output, Hawaii ERS board packet of 14 September 2026, p.35. |
A cut of two to three points on a $26.6 billion fund is $530 million to $800 million of private equity at today's size. The study says where the difficulty lies, because "the primary challenge relates to Illiquid classes and the ability to increase/decrease these allocations in a ~3-year time frame." A $5.2 billion private equity book, most of it run by Hamilton Lane, only shrinks through distributions, slower commitments or a sale. Hawaii's consultant has not named the last of those yet, as Oregon's did last week. It adds one line the buyers will read differently from the trustees: "Throughout all modeled scenarios, overall ERS liquidity is not a major risk."
On the radar
- Friday 18 September, Washington. Hearing requests on ARK's application for exchange-listed and tokenized classes of its venture interval fund close at 5:30pm Eastern, and without a hearing the order issues.
- Tuesday 22 September, London. Informa's Global Secondaries Summit has a session on single and multi-asset GP-leds, which now has a $2.5 billion aerospace vehicle with six bidders to discuss.
- Wednesday 23 September, West Sacramento. The CalSTRS investment committee takes the private equity consultant's semi-annual report, then an investment decision in closed session.
- Tuesday 29 September, New York. ILPA's Continuation Vehicles for the Limited Partner course meets the day before quarter-end. Sellers price every autumn process off the 30 September marks.
-
|