
Pre-Bell: VIX **normal** (16.82), SPX **+6.3% above** its 200-day SMA; US equities softer (SPX −0.4…
Daily Market Brief — 2026-09-15
Before the bell rings — here's the tape.
VIX normal (16.82), SPX +6.3% above its 200-day SMA; US equities softer (SPX −0.48%, NASDAQ −0.56%); SMH −4.75% leads sector losers on ASML/TSMC chipmaking cost news.
News (last 24h)
- [FinancialJuice/MarketWatch, <1h] Wells Fargo cuts S&P 500 year-end target to 7,700 from 7,950
- [FinancialJuice, <2h] NY Fed Manufacturing index 7.6 actual vs 15.0 forecast; prior 20.6
- [FinancialJuice, <2h] US ADP Weekly Employment Change 16.25k
- [MarketWatch, <3h] The 'Magnificent Seven' has its mojo back. It's on track to reach new highs.
- [FinancialJuice, <1h] Wells Fargo cuts tech stocks to equal-weight from overweight
- [Yahoo, <2h] ASML drops 5.4% on $400M machine costs; TSMC falls 3.3% on 2028 roadmap
- [FinancialJuice, <3h] Salesforce and Google Cloud expand enterprise AI pact
- [Yahoo, <2h] Broadcom's Real Constraint Isn't Demand. It's Supply.
- [MarketWatch, <4h] An AI bubble is no longer Wall Street's biggest fear. This market risk just took its place.
- [Yahoo, <2h] AI chip sell-off overblown: Zero GPU slowdown after Anthropic essay, analyst says
Observations
Today's setup: Long-dated Treasury yields are climbing back toward multi-year highs — the 10-year hit 4.99%, just below its 52-week peak, and the 30-year crossed 5.36% — even as a sharp NY Fed Manufacturing miss (7.6 vs a 15.0 forecast) signals activity slowing in the Northeast. That combination — weak economic data alongside rising bond yields — is unusually awkward for equities and is driving a clear rotation today: technology hardware is under pressure while defensive names are catching bids. Wells Fargo added fuel by cutting both its S&P 500 year-end target and its tech-sector rating in the same session, right as ASML and TSMC headline news raised questions about the trajectory of semiconductor equipment spending.
Semiconductor equipment cycle: The dominant sector story today is a repricing of the semiconductor capital-expenditure cycle. When the cost of chipmaking machines escalates ($400M cited for ASML's newest systems) and a leading foundry revises its multi-year roadmap, the market interprets it as a demand-cycle pause: equipment makers, foundries, and chip designers all sell off together, as order books that were priced against multi-year forward demand suddenly look less certain. This is the mechanism behind SMH's −4.75% move and TSMC's −3.52% decline. Importantly, software and platform companies — Meta +2.71%, Communication Services +2.19% — are bucking the selloff, suggesting investors are distinguishing between hardware-cycle exposure and software earnings streams with clearer near-term visibility.
Yield curve and defensive rotation: The yield curve is steepening with the long end leading, which would traditionally compress the valuation multiples for growth equities — and that is exactly what we see with XLK −1.81% and XLI −1.42%. On the other side, steepening curves modestly widen net interest margins for banks and insurers: Regional Banks (KRE) and Insurance (KIE +1.70%) are among the few sectors in the green. Utilities, by contrast, are near their 52-week low — the most duration-sensitive sector is taking the worst of both the rate move and the defensive rotation into higher-yielding alternatives.
Contrarian context: The CNN Fear & Greed gauge sits at 30 — squarely in Fear territory. Historically, readings this low during a normal VIX regime (16.8) and with the index still 6.3% above its 200-day moving average suggest more sentiment overshoot than structural deterioration. The SPX is down less than 0.5% on the session; this is a rotation day, not a breakdown day.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,619.98 | −0.48% | 86.9% |  |
| ^IXIC | NASDAQ Composite | 26,186.41 | −0.56% | 84.6% |  |
| ^DJI | Dow Jones Industrial Average | 52,421.20 | −0.29% | 76.0% |  |
| ^RUT | Russell 2000 (US small-cap) | 2,892.24 | −0.40% | 76.8% |  |
| ^GDAXI | DAX (Germany, EUR) | 25,453.89 | +0.05% | 75.5% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,676.95 | −0.19% | 82.8% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 63,484.10 | −0.01% | 67.2% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 6,627.26 | −0.85% | 54.2% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 45,511.49 | −0.77% | 88.2% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 24,667.24 | −1.00% | 38.8% |  |
| ^FVX | US 5Y yield | 4.811% | +0.44% | 91.0% | |
| ^TNX | US 10Y yield | 4.987% | +0.52% | 97.5% | |
| ^TYX | US 30Y yield | 5.362% | +0.62% | 93.1% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 99.57 | +0.11% | 64.3% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,332.20 | −0.45% | 35.7% |  |
| SI=F | Silver | 64.335 | +1.29% | 28.6% |  |
| CL=F | WTI Crude | 101.53 | +0.14% | 72.2% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 6,026.00 | +0.52% | 66.6% | S |  |
| KC=F | Coffee | 287.25 | −6.54% | 22.8% | T |  |
| ZS=F | Soybeans | 1,298.75 | +1.05% | 94.0% | T |  |
| ZC=F | Corn | 528.25 | +3.17% | 96.1% | L |  |
| ZW=F | Wheat | 712.50 | +0.78% | 77.7% | L |  |
| SB=F | Sugar | 18.03 | −0.72% | 85.0% | L |  |
| CT=F | Cotton | 84.09 | +4.28% | 74.4% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 16.82 | −1.64% |  |
| ^VXN | NASDAQ | 22.05 | +4.90% |  |
| ^GVZ | Gold | 26.54 | +3.35% |  |
| ^OVX | Crude | 59.46 | +0.92% |  |
Regime: normal (VIX-band 15–20).
Fear & Greed (CNN): Fear (30/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 184.28 | −1.81% | 79.9% |  |
| XLV | Health Care | 167.75 | +1.45% | 79.4% |  |
| XLF | Financials | 57.03 | −0.38% | 85.6% |  |
| XLRE | Real Estate (S&P) | 43.12 | −0.69% | 50.4% |  |
| XLE | Energy | 64.53 | −0.94% | 93.1% |  |
| XLB | Materials | 50.49 | −0.90% | 69.6% |  |
| XLI | Industrials | 169.93 | −1.42% | 55.5% |  |
| XLU | Utilities | 41.82 | −1.34% | 1.3% | 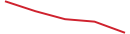 |
| XLP | Consumer Staples | 84.42 | +1.25% | 61.8% | 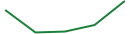 |
| XLY | Consumer Disc | 112.85 | −0.10% | 38.6% | 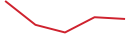 |
| XLC | Communication Svcs | 115.07 | +2.19% | 65.3% | 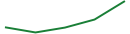 |
| SMH | Semiconductors | 541.50 | −4.75% | 64.8% |  |
| GLD | Gold (ETF) | 392.84 | −1.49% | 33.6% |  |
| GDX | Gold Miners | 94.14 | −3.05% | 53.8% |  |
| XME | Metals & Mining | 110.17 | −3.04% | 49.0% |  |
| OIH | Oil Services | 402.06 | −4.42% | 73.6% |  |
| XOP | Oil & Gas E&P | 193.47 | −1.15% | 92.3% |  |
| PBW | Clean Energy | 30.40 | −2.25% | 20.6% |  |
| MOO | Agribusiness | 86.32 | −0.19% | 85.1% |  |
| IBB | Biotech | 204.60 | +0.82% | 84.0% |  |
| KRE | Regional Banks | 74.11 | +0.28% | 79.6% |  |
| KIE | Insurance | 63.41 | +1.70% | 76.1% |  |
| ITB | Home Construction | 90.05 | +0.57% | 16.7% |  |
| VNQ | REITs (broad) | 94.33 | −0.50% | 50.1% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| EPM | 2026-09-15 | AH | 23.72% | — |
| FPS | 2026-09-15 | PM | 14.06% | — |
| TCOM | 2026-09-15 | AH | 6.15% | — |
| ALMU | 2026-09-16 | AH | 10.68% | — |
| LEN | 2026-09-16 | AH | 5.41% | — |
See you tomorrow, 60 minutes before the open.