
Pre-Bell: VIX **normal** (15.84, −11.21%) · SPX **+6.9% above** its 200-day SMA · SPX +0.86% (Fri)…
Daily Market Brief — 2026-09-13
Weekend tape — here's what's worth your time.
VIX normal (15.84, −11.21%) · SPX +6.9% above its 200-day SMA · SPX +0.86% (Fri) · SMH +1.47% / ITB +1.50% led sectors · WTI at $100 amid Saudi supply disruption; ECB hawkish + Fed meeting ahead
News (last 24h)
- [FinancialJuice, <24h] Saudi pipeline outage threatens 4% loss in global oil supply unless pumping resumes within days, say traders, sources
- [FinancialJuice, <24h] Vessel hit by unidentified projectile while passing Strait of Hormuz
- [FinancialJuice, <24h] Italy economy minister: crucial for Italy to maintain public finances as ECB hikes interest rates
- [FinancialJuice, <24h] Ukraine's military: strike on Taneko oil refinery in Russia's Tatarstan
- [Yahoo, <24h] Apple and Taiwan Semiconductor Manufacturing Just Announced a Cutting-Edge Chip. 1 Stock Offers Far Greater Upside.
- [MarketWatch / Yahoo, <24h] Dow Jones Futures: Fed Meeting Ahead; Anthropic's Amodei, OpenAI's Altman, SpaceX's Musk Call For AI Slowdown
- [FinancialJuice, <24h] UK foreign secretary: UK stands firmly with Saudi Arabia and internationally recognized Yemen government against attacks
- [Yahoo, <24h] Tesla Is Reclaiming the U.S. EV Market as Legacy Automakers Retreat
- [Yahoo, <24h] Nvidia vs. AMD: Elon Musk Picked a Side on the SpaceX Earnings Call
- [FinancialJuice, <24h] South Korea industry minister: $200 billion total chip investment cap to be maintained as previously agreed with U.S.
Observations
Today's setup: Friday's session delivered a broad risk-on rally — US indices up roughly 1%, and the VIX falling 11% from 17.8 to 15.8 — against a backdrop of two serious oil supply disruptions (a Saudi pipeline outage threatening 4% of global output, and a vessel struck in the Strait of Hormuz) and a hawkish central-bank week ahead. WTI crude stands at $100, up nearly 10% on the week, yet equity volatility collapsed rather than spiked. The central tension heading into Monday is whether a sustained oil shock quietly feeds into CPI — and forces the Fed's hand — in the weeks ahead, even as markets are pricing in a relatively benign near-term outlook.
The yield curve told a hawkish story Friday. Italy's economy minister reinforced ECB rate-hike expectations, and with the Fed meeting on the calendar this week, US 5-year yields rose 1.2% (to 4.79%) while the 30-year barely moved (−0.1%, at 5.35%). When near-term policy rate expectations rise faster than long-term yields, it typically pressures rate-sensitive sectors — and Friday partially confirmed this: utilities fell 0.3% while tech and industrials advanced. The exception was home construction (ITB +1.5%), which rallied despite a 10-year yield of nearly 5% — suggesting either that mortgage-rate expectations are already fully priced in, or that seasonal new-home demand is absorbing the rate drag in this particular market.
Apple and Taiwan Semiconductor's joint announcement of an advanced chip, combined with Elon Musk selecting Nvidia over AMD on a SpaceX earnings call, gave the semiconductor sector a strong tailwind Friday. The Semiconductor ETF (SMH) rose 1.5% and Taiwan Semiconductor itself gained 1.2% despite Taiwan's broader equity market falling 1.6% in the Asia session. This divergence — US-listed semiconductor exposure advancing while the home market trades down — reflects that institutional positioning in the global AI capital-expenditure cycle is dominating over regional sentiment.
Agricultural markets delivered two sharp moves worth watching. Coffee futures plunged 9.4% — the largest single-day move in the soft-commodity universe — with no clear news catalyst in weekend headlines; the contract is now at 21% of its 52-week range. Cotton surged 6%, while corn rose 4.3% and wheat 2.7%. September is seasonally supportive for corn and wheat based on a decade of futures history (post-harvest strength typically overrides the intuitive harvest-pressure narrative), and Friday's moves are directionally consistent with that pattern.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,656.98 | +0.86% | 89.4% | 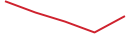 |
| ^IXIC | NASDAQ | 26,333.04 | +0.96% | 86.8% | 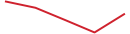 |
| ^DJI | Dow Jones | 52,573.29 | +0.98% | 77.6% | 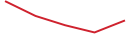 |
| ^RUT | Russell 2000 (US small-cap) | 2,903.94 | +0.45% | 78.4% | 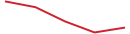 |
| ^GDAXI | DAX (Germany, EUR) | 25,568.56 | +0.82% | 77.9% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,650.44 | +0.39% | 81.3% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 64,011.34 | −1.93% | 69.0% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 6,909.91 | −1.76% | 58.9% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 46,184.85 | −1.61% | 91.1% | 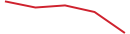 |
| ^HSI | Hang Seng (HK / China, HKD) | 24,805.63 | −0.60% | 41.3% | 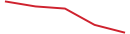 |
| ^FVX | US 5Y yield | 4.791% | +1.23% | n/a | |
| ^TNX | US 10Y yield | 4.975% | +0.63% | n/a | |
| ^TYX | US 30Y yield | 5.354% | −0.13% | n/a | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 99.10 | −0.03% | 56.7% | 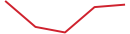 |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,408.90 | +0.98% | 39.7% | 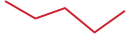 |
| SI=F | Silver | 65.19 | +0.98% | 29.7% |  |
| CL=F | WTI Crude | 100.05 | 0.00% | 69.9% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,913.00 | −0.34% | 64.3% | S |  |
| KC=F | Coffee | 284.25 | −9.37% | 21.3% | T |  |
| ZS=F | Soybeans | 1,299.00 | +1.46% | 89.4% | T | 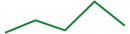 |
| ZC=F | Corn | 532.00 | +4.26% | 91.3% | L | 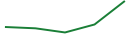 |
| ZW=F | Wheat | 726.25 | +2.72% | 82.6% | L | 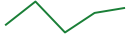 |
| SB=F | Sugar | 18.15 | 0.00% | 74.2% | L | 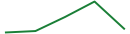 |
| CT=F | Cotton | 87.37 | +6.06% | 84.8% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 15.84 | −11.21% |  |
| ^VXN | NASDAQ | 21.02 | −9.90% |  |
| ^GVZ | Gold | 25.68 | −9.83% |  |
| ^OVX | Crude | 58.92 | −3.03% | 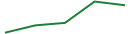 |
Regime: normal (VIX 15.84, band 15–20).
Fear & Greed (CNN): Fear (33/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 187.67 | +1.32% | 84.7% | 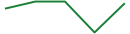 |
| XLV | Health Care | 165.36 | −0.18% | 73.8% | 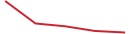 |
| XLF | Financials | 57.25 | +0.67% | 87.7% | 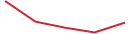 |
| XLRE | Real Estate (S&P) | 43.42 | +0.86% | 54.9% | 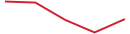 |
| XLE | Energy | 65.14 | +0.32% | 95.7% | 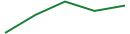 |
| XLB | Materials | 50.95 | +0.37% | 73.3% | 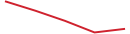 |
| XLI | Industrials | 172.37 | +1.07% | 61.5% | 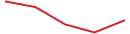 |
| XLU | Utilities | 42.39 | −0.31% | 10.7% |  |
| XLP | Consumer Staples | 83.38 | +0.35% | 54.9% |  |
| XLY | Consumer Disc | 112.96 | +0.89% | 39.2% |  |
| XLC | Communication Svcs | 112.60 | +0.99% | 49.2% |  |
| SMH | Semiconductors | 568.53 | +1.47% | 72.1% |  |
| GLD | Gold (ETF) | 398.77 | +0.61% | 37.0% |  |
| GDX | Gold Miners | 97.10 | +1.11% | 59.8% |  |
| XME | Metals & Mining | 113.63 | −0.99% | 55.9% |  |
| OIH | Oil Services | 420.67 | +0.11% | 82.2% |  |
| XOP | Oil & Gas E&P | 195.72 | +0.13% | 96.7% |  |
| PBW | Clean Energy | 31.10 | +0.81% | 25.4% |  |
| MOO | Agribusiness | 86.48 | −0.36% | 85.9% |  |
| IBB | Biotech | 202.93 | +0.14% | 81.9% |  |
| KRE | Regional Banks | 73.90 | +0.12% | 78.6% |  |
| KIE | Insurance | 62.35 | +0.16% | 68.1% |  |
| ITB | Home Construction | 89.54 | +1.50% | 15.1% |  |
| VNQ | REITs (broad) | 94.80 | +0.72% | 53.2% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| BIOX | 2026-09-14 | AH | 429.42% | — |
| HAIN | 2026-09-14 | PM | 22.17% | — |
| PLAY | 2026-09-14 | AH | 14.75% | — |
| HITI | 2026-09-14 | AH | 8.47% | — |
| RLGT | 2026-09-14 | AH | 7.50% | — |
| EPM | 2026-09-15 | AH | 23.66% | — |
| FPS | 2026-09-15 | PM | 13.57% | — |
| TCOM | 2026-09-15 | AH | 5.99% | — |
| ALMU | 2026-09-16 | AH | 13.39% | — |
| LEN | 2026-09-16 | AH | 5.72% | — |
Zacks rank changes (last 24h)
- DOWNGRADE THO (Thor Industries)
2 → 3
See you Monday, 60 minutes before the open.