
Pre-Bell: VIX **normal** (15.45), SPX **+8.1% above** its 200-day SMA; Nikkei −1.70% on yen 6-month…
Daily Market Brief — 2026-09-08
Before the bell rings — here's the tape.
VIX normal (15.45), SPX +8.1% above its 200-day SMA; Nikkei −1.70% on yen 6-month high; SMH +2.61% on ASML multi-foundry endorsement; TSLA −5.92% on BYD China price war.
News (last 24h)
- [FinancialJuice, <24h] Bank of England to hold bank rate at 3.75% through Q2 2027; consensus of 65 economists confirms hold.
- [FinancialJuice, <24h] RBA signals cautious rate-hike debate focused on upside inflation risks; outcome not guaranteed.
- [FinancialJuice, <24h] US NFIB Business Optimism Index misses forecast at 98.7 vs. 99.3 expected.
- [FinancialJuice, <24h] Qualcomm reports multi-generational product pact with Amazon.
- [MarketWatch, <24h] US oil prices reach highest level in over three months after Saudi Arabia sites struck.
- [Yahoo, <24h] TSMC, Samsung, and Intel endorse ASML's next-generation chipmaking technology.
- [FinancialJuice, <24h] Accenture and Google Cloud deploy FDES on-site for AI buildout.
- [FinancialJuice, <24h] EU trade chief Sefcovic signals current EU-China situation is unsustainable.
- [MarketWatch, <24h] Japanese yen strengthens to six-month high amid broader market shifts.
- [FinancialJuice, <24h] BNP Paribas revises BoE rate-hike forecast to November vs. prior September expectation.
Observations
Today's setup: A Saudi Arabia supply disruption sent WTI crude to its highest level in over three months, but energy-sector ETFs (XLE −0.87%, XOP −0.84%, OIH −0.53%) all fell on the day — the market appears to be treating the shock as transient rather than structural. Semiconductors bucked the broader selloff: TSMC, Samsung, and Intel jointly endorsed ASML's next-generation chipmaking tools, providing a demand-confirmation boost to SMH (+2.61%) and TSM (+2.85%). The yen hit a six-month high against the dollar, pressuring the Nikkei down 1.7%. TSLA fell nearly 6% on news that BYD has undercut its China pricing by $6,000, accelerating an already difficult competitive dynamic in its largest growth market.
The unified endorsement of ASML's next-generation EUV technology by the world's three largest semiconductor foundries is a meaningful demand signal for the chip-equipment spending cycle. When TSMC, Samsung, and Intel collectively commit to the same technology roadmap, it removes uncertainty from multiyear capex plans — supporting ASML, its supplier ecosystem, and the broader semiconductor index even as the rest of the market slipped. This is the AI infrastructure buildout playing out in the supply chain: hyperscaler demand flows through the foundries into the equipment makers.
A strengthening yen exerts a well-documented mechanical pressure on Japanese equities through the carry-trade channel. Funds borrowed cheaply in yen and deployed into higher-yielding assets must unwind when the yen appreciates sharply — they sell those assets and repay the yen loans, creating concurrent downward pressure. Today's 1.5% JPY move against the dollar was the visible force behind the Nikkei's 1.7% decline; Japan's export-heavy index faces an additional headwind when yen strength erodes the translated revenues of its large multinationals.
The Bank of England's confirmed hold at 3.75% through Q2 2027 — backed by a rare consensus of 65 economists — reinforces a global narrative in which central banks are pausing rather than easing further. The US 10-year yield edged down slightly to 4.77% and the dollar index slipped 0.30%. The NFIB Business Optimism miss (98.7 vs. 99.3 expected) adds a softening note to the US activity picture, though the Federal Reserve's next move remains data-dependent and distant.
Premarket Gappers
Premarket scan unavailable this run.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,718.60 | −0.38% | 93.5% |  |
| ^IXIC | NASDAQ | 26,506.99 | −0.29% | 89.5% |  |
| ^DJI | Dow Jones | 53,414.25 | −0.51% | 86.3% |  |
| ^RUT | Russell 2000 (US small-cap) | 2,975.65 | +0.25% | 87.7% |  |
| ^GDAXI | DAX (Germany, EUR) | 26,008.48 | +0.01% | 87.2% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,828.80 | +0.06% | 91.1% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 65,269.33 | −1.70% | 74.3% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 6,954.52 | −0.58% | 60.6% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 47,105.78 | −0.47% | 95.3% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 25,317.18 | −0.38% | 50.5% |  |
| ^FVX | US 5Y yield | 4.536% | −0.31% | 95.7% | |
| ^TNX | US 10Y yield | 4.770% | −0.29% | 95.1% | |
| ^TYX | US 30Y yield | 5.229% | −0.32% | 87.8% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 98.878 | −0.30% | 53.2% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,446.10 | −0.68% | 42.1% |  |
| SI=F | Silver | 66.78 | +0.05% | 32.2% |  |
| CL=F | WTI Crude | 93.11 | +1.78% | 59.1% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,983.00 | −3.31% | 65.7% | S |  |
| KC=F | Coffee | 293.50 | −0.71% | 26.0% | T |  |
| ZS=F | Soybeans | 1,306.50 | −0.25% | 95.5% | T |  |
| ZC=F | Corn | 537.75 | +0.19% | 96.1% | L |  |
| ZW=F | Wheat | 745.00 | +1.50% | 89.2% | L |  |
| SB=F | Sugar | 18.07 | +0.00% | 87.4% | L |  |
| CT=F | Cotton | 86.17 | −0.32% | 81.0% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 15.45 | +0.98% |  |
| ^VXN | NASDAQ | 20.04 | −0.60% |  |
| ^GVZ | Gold | 26.63 | −2.02% |  |
| ^OVX | Crude | 44.96 | −3.12% | 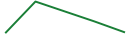 |
Regime: normal (VIX-band 15–20).
Fear & Greed (CNN): Fear (42/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 187.28 | +0.70% | 84.1% | 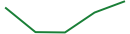 |
| XLV | Health Care | 171.45 | −1.04% | 87.9% | 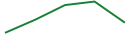 |
| XLF | Financials | 58.10 | −0.79% | 95.4% | 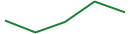 |
| XLRE | Real Estate (S&P) | 43.93 | −0.72% | 62.5% |  |
| XLE | Energy | 64.06 | −0.87% | 93.7% |  |
| XLB | Materials | 52.44 | −0.34% | 85.6% |  |
| XLI | Industrials | 175.27 | +0.41% | 68.5% |  |
| XLU | Utilities | 43.08 | +0.12% | 28.2% |  |
| XLP | Consumer Staples | 84.58 | −0.80% | 62.9% |  |
| XLY | Consumer Disc | 114.91 | −1.33% | 49.0% |  |
| XLC | Communication Svcs | 112.03 | −1.19% | 45.5% |  |
| SMH | Semiconductors | 567.01 | +2.61% | 72.2% |  |
| GLD | Gold (ETF) | 406.77 | −0.84% | 43.9% |  |
| GDX | Gold Miners | 99.26 | −2.20% | 64.5% |  |
| XME | Metals & Mining | 118.62 | +0.20% | 67.6% |  |
| OIH | Oil Services | 427.53 | −0.53% | 85.4% |  |
| XOP | Oil & Gas E&P | 190.71 | −0.84% | 94.3% |  |
| PBW | Clean Energy | 31.79 | +0.79% | 31.9% |  |
| MOO | Agribusiness | 87.83 | −0.40% | 92.6% |  |
| IBB | Biotech | 211.92 | −0.88% | 93.4% |  |
| KRE | Regional Banks | 75.27 | +0.53% | 85.2% |  |
| KIE | Insurance | 63.90 | −1.39% | 79.9% |  |
| ITB | Home Construction | 93.91 | +0.31% | 28.4% |  |
| VNQ | REITs (broad) | 96.02 | −0.66% | 61.4% |  |
Earnings & Zacks
Rank 2 with earnings in next ~30 days (pre-positioning window)
- Rank 2 M — ESP +20.81% — reports 2026-09-10
- Rank 2 ORCL — ESP +1.10% — reports 2026-09-10
See you tomorrow, 60 minutes before the open.