
Pre-Bell: VIX **calm** (14.87, −5.11%); SPX **+7.5% above** its 200-day SMA; Nikkei 225 +1.30% led…
Daily Market Brief — 2026-09-27
Weekend tape — here's what's worth your time.
VIX calm (14.87, −5.11%); SPX +7.5% above its 200-day SMA; Nikkei 225 +1.30% led global equities; Home Construction (ITB +1.27%) topped US sectors; META −3.33% on AI repositioning news; GM +2.56% on EV battery breakthrough. Prices reflect Friday's close — US market closed today (Sunday).
News (last 24h)
- [MarketWatch, ~12h] Why the upcoming jobs report could send 10-year and 30-year Treasury yields surging
- [FinancialJuice, ~8h] Iran escalates military posturing while maintaining Strait of Hormuz leverage; captures US autonomous vehicle; foreign minister signals negotiation openness
- [FinancialJuice / Yahoo, ~9h] Trump approves new fuel economy standards ending Biden's EV mandate; GM and Ford stock trade differently
- [Yahoo, ~6h] Zuckerberg's 'wartime CEO' positions Muse as company centerpiece; analyst sees personalized AI as major profit driver; Meta blocks Muse from Amazon Seller Central
- [Yahoo, ~7h] The AI gold rush is fueling a record corporate bond boom
- [Yahoo, ~5h] GM achieves closed-loop EV battery breakthrough; MP Materials ships first magnets to GM in Q4
- [FinancialJuice, ~6h] Libya reopens Sharara-Zawiya pipeline; crude output returning to normal levels
- [Yahoo, ~4h] Dow Jones Futures: Growth shrugs off surging yields; Trump rejects Iran deal; Micron, SpaceX, Tesla eye buy points
- [Yahoo, ~5h] 2 key checks for the AI trade and the economy: What to watch this week
- [Yahoo, ~3h] Ford halted F-150 output at Dearborn in Q3's final week
Observations
Today's setup: US equities ended Friday near 52-week highs — the S&P 500 sits more than 7% above its 200-day moving average, the NASDAQ at 97% of its 52-week range, and semiconductors (SMH) at 82% — while the VIX compressed to 14.87, a calm reading suggesting low institutional hedge demand heading into a pivotal week. The structural tension in the setup is elevated long-term rates: the 10-year Treasury yield settled at 5.18% and the 30-year at 5.50%, both moving higher on Friday. Next week's jobs report is the key binary: strong labor data would remove the Fed's rationale for rate cuts and could push long-end yields toward — and past — their 52-week highs.
When strong employment data removes the rationale for near-term rate cuts, bond markets tend to price higher terminal rates, lifting long-end yields while the dollar firms up alongside them. The dollar index (DXY) at 101 — near its 52-week high — is consistent with this already tightening in. The unusual aspect of the current setup is that equities are simultaneously near their own 52-week highs: technology (XLK at 97% of range) and semiconductors are absorbing elevated rates through the AI infrastructure narrative, which has fueled a record corporate bond issuance boom as companies race to fund data center buildout.
Iran's mixed posture — military escalation alongside diplomatic signals from its foreign minister — is keeping a risk premium embedded in energy markets via the Strait of Hormuz, through which roughly 20% of global oil transits. The Libyan Sharara-Zawiya pipeline resumption pushed in the other direction, providing a partial supply offset that helps explain why WTI crude was little changed on Friday. What is notable is that crude oil volatility (OVX) rose 9.5% on the week even while equity volatility fell — an early cross-asset divergence worth watching if Iran's diplomatic window narrows further.
Meta fell 3.3% on Friday after Zuckerberg repositioned the company as a "wartime CEO" around its Muse AI platform. The narrative of Muse as a personalized AI profit engine was offset by news that Meta has been blocked from Amazon Seller Central, creating a real distribution friction that the market appears to have weighed negatively. At 89% of its 52-week range, Meta had limited cushion for an ambiguous strategic signal.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,743.41 | +0.51% | 95.1% | 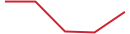 |
| ^IXIC | NASDAQ Composite | 27,068.72 | +0.48% | 96.7% | 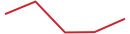 |
| ^DJI | Dow Jones | 51,828.62 | +0.93% | 69.9% | 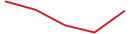 |
| ^RUT | Russell 2000 (US small-cap) | 2,837.55 | +0.07% | 69.7% | 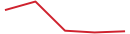 |
| ^GDAXI | DAX (Germany, EUR) | 25,408.64 | +0.56% | 74.6% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,695.25 | +0.14% | 82.9% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 66,364.20 | +1.30% | 77.3% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 7,080.92 | +0.90% | 61.4% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 48,024.60 | −0.28% | 97.5% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 24,510.09 | −1.01% | 36.0% |  |
| ^FVX | US 5Y yield | 5.007% | −0.36% | n/a | |
| ^TNX | US 10Y yield | 5.184% | +0.43% | n/a | |
| ^TYX | US 30Y yield | 5.504% | +0.79% | n/a | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 101.035 | +0.06% | 87.8% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,321.20 | 0.00% | 29.8% |  |
| SI=F | Silver | 64.80 | +0.87% | 25.6% |  |
| CL=F | WTI Crude | 92.41 | 0.00% | 58.0% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,603.00 | −0.28% | 65.5% | S |  |
| KC=F | Coffee | 278.10 | −0.18% | 18.1% | T |  |
| ZS=F | Soybeans | 1,319.00 | 0.00% | 96.1% | T |  |
| ZC=F | Corn | 528.25 | 0.00% | 88.9% | L |  |
| ZW=F | Wheat | 703.25 | 0.00% | 74.4% | L |  |
| SB=F | Sugar | 17.52 | +0.11% | 76.0% | L |  |
| CT=F | Cotton | 82.49 | +4.54% | 69.3% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 14.87 | −5.11% |  |
| ^VXN | NASDAQ | 20.87 | −1.74% |  |
| ^GVZ | Gold | 22.44 | −0.62% |  |
| ^OVX | Crude | 55.09 | +1.18% |  |
Regime: calm (VIX 14.87 < 15).
Fear & Greed (CNN): Fear (37/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 196.27 | +0.80% | 96.6% |  |
| XLV | Health Care | 170.70 | +0.49% | 85.9% |  |
| XLF | Financials | 54.84 | +0.57% | 65.6% |  |
| XLRE | Real Estate (S&P) | 41.56 | −0.22% | 27.3% |  |
| XLE | Energy | 62.04 | −0.89% | 82.7% |  |
| XLB | Materials | 49.80 | +0.24% | 63.9% |  |
| XLI | Industrials | 170.43 | +0.95% | 56.7% |  |
| XLU | Utilities | 39.51 | +0.38% | 4.4% |  |
| XLP | Consumer Staples | 82.06 | +0.44% | 46.1% |  |
| XLY | Consumer Disc | 110.56 | +0.22% | 27.1% |  |
| XLC | Communication Svcs | 112.96 | −0.90% | 51.6% |  |
| SMH | Semiconductors | 606.56 | +1.01% | 81.7% |  |
| GLD | Gold (ETF) | 393.41 | +0.44% | 26.8% |  |
| GDX | Gold Miners | 92.87 | +0.56% | 50.4% |  |
| XME | Metals & Mining | 108.33 | +0.34% | 45.4% |  |
| OIH | Oil Services | 393.68 | −0.13% | 69.8% |  |
| XOP | Oil & Gas E&P | 181.50 | −1.39% | 75.4% |  |
| PBW | Clean Energy | 30.02 | +0.30% | 13.3% |  |
| MOO | Agribusiness | 83.27 | −0.08% | 69.8% |  |
| IBB | Biotech | 209.77 | +0.25% | 90.4% |  |
| KRE | Regional Banks | 71.55 | +0.86% | 67.3% |  |
| KIE | Insurance | 59.71 | +0.07% | 47.9% |  |
| ITB | Home Construction | 89.43 | +1.27% | 14.7% |  |
| VNQ | REITs (broad) | 90.99 | −0.20% | 27.7% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| MTN | 2026-09-28 | AH | 8.46% | |
| JEF | 2026-09-28 | AH | 7.42% | |
| CNXC | 2026-09-29 | AH | 17.50% | |
| KMX | 2026-09-29 | PM | 10.66% | |
| AIR | 2026-09-29 | AH | 9.75% | |
| UEC | 2026-09-29 | PM | 6.66% | |
| CCL | 2026-09-29 | PM | 5.99% | |
| PRGS | 2026-09-30 | AH | 10.31% | |
| FDS | 2026-09-30 | PM | 9.33% | |
| CALM | 2026-09-30 | PM | 7.87% | |
| JBL | 2026-09-30 | PM | 7.77% | |
| MU | 2026-09-30 | AH | 7.29% | 3 |
| CAG | 2026-09-30 | PM | 4.61% | |
| MKC | 2026-10-01 | PM | 7.27% | |
| NKE | 2026-10-01 | AH | 7.06% | |
| ACN | 2026-10-01 | PM | 6.64% |
See you Monday, 60 minutes before the open.