
Pre-Bell: VIX **calm** (14.87, −5.1%). SPX **+7.5% above** its 200-day SMA. Nikkei led indices at +…
Daily Market Brief — 2026-09-26
Weekend tape — here's what's worth your time.
VIX calm (14.87, −5.1%). SPX +7.5% above its 200-day SMA. Nikkei led indices at +1.30%; 30Y Treasury at a new 52-week high. ITB home construction +1.27% led sectors; crude fell −2.33% despite a Ukrainian strike on a Russian oil refinery.
News (last 24h)
- [FinancialJuice, <1h] SNB chairman Schlegel: can maintain interest rates as inflation hits target
- [FinancialJuice, <2h] Ukrainian military: It hit Ilsky oil refinery in southern Russia
- [Yahoo, ~4h] Tesla (TSLA), Ford (F), and GM (GM) Face a Weaker EV Market. Who Can Protect Profits?
- [Yahoo, ~4h] Meet the Magnificent Semiconductor Stock Crushing Nvidia in 2026
- [FinancialJuice, <3h] China foreign minister Wang Yi: Xi's U.S. visit opens 'new chapter' in China-U.S. ties
- [MarketWatch, ~3h] China is playing a different game when it comes to AI
- [FinancialJuice, <1h] South Korea president Lee calls for comprehensive trade deal between South Korea and Mexico
- [Yahoo, ~3h] Meta has an AI solution to its misunderstood trust problem
- [Yahoo, ~4h] What Do Tesla (TSLA) Tunnel And Grid Plans Mean For Investors?
- [FinancialJuice, <2h] Trump rejects Iran ceasefire: anticipates increased bombing after midterms — WSJ
Observations
Today's setup: Friday's session closed with a notable divergence: the 30-year Treasury yield broke to a new 52-week high while equity indices drifted higher and VIX compressed toward its yearly lows. Rate-sensitive sectors — real estate, utilities, home builders — remain pinned near the bottom of their 52-week ranges, but the broader market is shrugging off the bond pressure for now. The Fear & Greed gauge sits in "Fear" territory at 37, suggesting investor positioning is more cautious than prices alone imply.
The surge in long-term Treasury yields is the week's central tension. Long-end yields — the 10-year and 30-year — are driven by inflation expectations and term premium, not by Federal Reserve rate decisions. When the 30-year breaks to new highs, it raises the discount rate on every long-duration asset: mortgage rates rise, REIT valuations compress, and utility stocks (which trade like bonds) fall. The data confirms this channel: XLU and home builders are sitting near their 52-week lows even as technology sits near its 52-week high. The market is bifurcating cleanly along duration lines.
Ukraine struck a Russian oil refinery, yet WTI crude fell over 2%. This is significant: the market is pricing supply adequacy despite the headline disruption. One strike on one refinery — even a meaningful one — isn't enough to shift global oil balances when U.S. production remains at elevated levels. Energy sector ETFs (XOP, XLE) both fell on the day. The geopolitical-oil-shock-to-inflation transmission chain requires a sustained supply disruption, not a one-day event.
The semiconductor complex continues to benefit from AI infrastructure spending. SMH gained over 1% and XLK sits near a 52-week high. The news that a rival semiconductor firm is outperforming Nvidia in 2026 year-to-date reflects healthy competition within the theme rather than a threat to it — AI-driven capex spending supports foundries, memory, and custom silicon broadly. TSM and the broader chip ecosystem remain structurally supported.
META dropped 3.3% on Friday despite sitting near its 52-week high and despite constructive AI news flow. With no fundamental catalyst, the move looks like distribution after a strong week (+1.4%). GM bucked the EV-market weakness narrative with a +2.56% gain, apparently boosted by news that it is now supplying Patriot missile components to Lockheed Martin — a defense supply-chain angle that insulates it somewhat from the consumer EV demand story.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,743.41 | +0.51% | 95.1% | 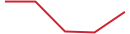 |
| ^IXIC | NASDAQ | 27,068.72 | +0.48% | 96.7% | 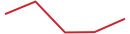 |
| ^DJI | Dow Jones | 51,828.62 | +0.93% | 69.9% | 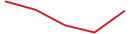 |
| ^RUT | Russell 2000 (US small-cap) | 2,837.55 | +0.07% | 69.7% | 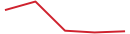 |
| ^GDAXI | DAX (Germany, EUR) | 25,408.64 | +0.56% | 74.6% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,695.25 | +0.14% | 82.9% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 66,364.20 | +1.30% | 77.3% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 7,080.92 | +0.90% | 61.4% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 48,024.60 | −0.28% | 97.5% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 24,510.09 | −1.01% | 36.0% |  |
| ^FVX | US 5Y yield | 5.007% | −0.36% | — | |
| ^TNX | US 10Y yield | 5.184% | +0.43% | — | |
| ^TYX | US 30Y yield | 5.504% | +0.79% | New 52W H | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 101.04 | −0.25% | 87.8% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,321.20 | +0.54% | 29.7% |  |
| SI=F | Silver | 64.80 | +2.12% | 25.6% |  |
| CL=F | WTI Crude | 92.41 | −2.33% | 58.0% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,603.00 | +0.23% | 65.5% | S |  |
| KC=F | Coffee | 278.10 | +1.00% | 18.1% | T |  |
| ZS=F | Soybeans | 1,319.00 | +0.11% | 96.1% | T |  |
| ZC=F | Corn | 528.25 | +0.14% | 88.8% | L |  |
| ZW=F | Wheat | 703.25 | −0.53% | 74.4% | L |  |
| SB=F | Sugar | 17.52 | −0.34% | 76.0% | L |  |
| CT=F | Cotton | 82.49 | +3.75% | 69.3% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 14.87 | −5.11% |  |
| ^VXN | NASDAQ | 20.87 | −1.74% |  |
| ^GVZ | Gold | 22.44 | −0.62% |  |
| ^OVX | Crude | 55.09 | +1.18% |  |
Regime: calm (VIX 14.87 < 15).
Fear & Greed (CNN): Fear (37/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 196.27 | +0.80% | 96.6% |  |
| XLV | Health Care | 170.70 | +0.49% | 85.9% |  |
| XLF | Financials | 54.84 | +0.57% | 65.6% |  |
| XLRE | Real Estate (S&P) | 41.56 | −0.22% | 27.3% |  |
| XLE | Energy | 62.04 | −0.89% | 82.7% |  |
| XLB | Materials | 49.80 | +0.24% | 63.9% |  |
| XLI | Industrials | 170.43 | +0.95% | 56.7% |  |
| XLU | Utilities | 39.51 | +0.38% | 4.4% |  |
| XLP | Consumer Staples | 82.06 | +0.44% | 46.1% |  |
| XLY | Consumer Disc | 110.56 | +0.22% | 27.1% |  |
| XLC | Communication Svcs | 112.96 | −0.90% | 51.6% |  |
| SMH | Semiconductors | 606.56 | +1.01% | 81.7% |  |
| GLD | Gold (ETF) | 393.41 | +0.44% | 26.8% |  |
| GDX | Gold Miners | 92.87 | +0.56% | 50.4% |  |
| XME | Metals & Mining | 108.33 | +0.34% | 45.3% |  |
| OIH | Oil Services | 393.68 | −0.13% | 69.8% |  |
| XOP | Oil & Gas E&P | 181.50 | −1.39% | 75.4% |  |
| PBW | Clean Energy | 30.02 | +0.30% | 13.3% |  |
| MOO | Agribusiness | 83.27 | −0.08% | 69.8% |  |
| IBB | Biotech | 209.77 | +0.25% | 90.4% |  |
| KRE | Regional Banks | 71.55 | +0.86% | 67.3% |  |
| KIE | Insurance | 59.71 | +0.07% | 47.9% |  |
| ITB | Home Construction | 89.43 | +1.27% | 14.7% |  |
| VNQ | REITs (broad) | 90.99 | −0.20% | 27.7% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| MTN | 2026-09-28 | AH | ±8.46% | — |
| JEF | 2026-09-28 | AH | ±7.42% | — |
| CNXC | 2026-09-29 | AH | ±17.50% | — |
| KMX | 2026-09-29 | PM | ±10.66% | — |
| AIR | 2026-09-29 | AH | ±9.75% | — |
| UEC | 2026-09-29 | PM | ±6.66% | — |
| CCL | 2026-09-29 | PM | ±5.99% | — |
| PRGS | 2026-09-30 | AH | ±10.31% | — |
| FDS | 2026-09-30 | PM | ±9.33% | — |
| CALM | 2026-09-30 | PM | ±7.87% | — |
| JBL | 2026-09-30 | PM | ±7.77% | — |
| MU | 2026-09-30 | AH | ±7.29% | 3 |
| CAG | 2026-09-30 | PM | ±4.61% | — |
| MKC | 2026-10-01 | PM | ±7.27% | — |
| NKE | 2026-10-01 | AH | ±7.06% | — |
| ACN | 2026-10-01 | PM | ±6.64% | — |
See you Monday, 60 minutes before the open.