
Pre-Bell: VIX **normal** (16.02, +7.73%) · SPX **+7.47% above** its 200-day SMA · DJI leads US indi…
Daily Market Brief — 2026-09-28
Before the bell rings — here's the tape.
VIX normal (16.02, +7.73%) · SPX +7.47% above its 200-day SMA · DJI leads US indices +0.93% · XLK +0.80% leads sectors; VIX and SPX both rising simultaneously — an unusual divergence
News (last 24h)
- [FinancialJuice, <24h] Nvidia announces $150 billion stock buyback
- [FinancialJuice, <24h] Nvidia forward commitments surge to $279 billion from $119 billion amid AI capex acceleration (includes $180B+ Anthropic investment)
- [FinancialJuice, <24h] Meta CEO Zuckerberg launches new enterprise AI platform as major business pillar
- [Yahoo, <24h] Apple and Nvidia demand boost TSMC; Taiwan Semi considers second Singapore facility
- [FinancialJuice, <24h] Nvidia CEO Huang unveils agent browser as new software platform for AI agents
- [Yahoo, <24h] GM CFO warns Chinese EV rivals fleeing China will intensify US market competition
- [MarketWatch, <24h] Market breadth deterioration signals potential systemic risks ahead for equities
- [FinancialJuice, <24h] Iran and US mediators hold separate nuclear talks Monday or Tuesday on revised proposal
- [FinancialJuice, <24h] Overnight rates stable: Fed Funds 3.88% unchanged; SOFR ticks to 3.90%
- [FinancialJuice + WSJ, <24h] Trump to unveil $15 billion Iowa steel manufacturing project
Observations
Today's setup: US indices are opening modestly higher on a Monday, led by Dow (+0.93%) and tech (XLK +0.80%), while KOSPI posted the session's sharpest loss at −2.70% and gold fell sharply (−3.19%). The dominant background tension is US Treasury yields sitting at or near their 52-week highs across all tenors — the 10-year is at 5.217% and the 30-year at 5.530%, both near the top of their annual range — while the S&P 500 stands over 7% above its 200-day moving average. That combination of high valuations, elevated yields, and a VIX that is rising alongside equities (rather than falling as usual) signals a market that is gaining altitude with increasing structural strain.
The yield environment is the week's most important macro backdrop. When long-term Treasury yields are this elevated, they exert mechanical pressure on the sectors most sensitive to borrowing costs — notably utilities (XLU at just 4% of its 52-week range, near the yearly low), real estate, and housing. Home builders (ITB +1.27%) and industrials (XLI +0.95%) are exceptions, likely supported by the steel-manufacturing and industrial-policy news. The dollar strengthened modestly (+0.22%) alongside the yield move, which is a consistent relationship: higher US rates attract international capital, lifting the dollar.
The AI capital-expenditure cycle remains the equity market's dominant positive narrative. Nvidia's announcement of a $150 billion share buyback — the largest in the company's history — together with a doubling of its forward supply commitments to $279 billion (including a reported $180 billion-plus linked to Anthropic) is a powerful signal that hyperscaler demand for AI infrastructure is accelerating rather than peaking. The beneficiaries of this spending — chip designers, foundries like TSMC, and semiconductor equipment makers — held up well today, with the semiconductor ETF (SMH) gaining 1%. By contrast, Meta fell 3.33% despite Zuckerberg's enterprise-AI platform launch and a fresh analyst price-target increase to $830. This is a recurring pattern in the current cycle: companies that announce major AI spending commitments often see their shares sold on the news because investors interpret the capex as a margin headwind rather than a revenue signal, at least in the near term.
Gold's sharp decline (−3.19%, silver −4.88%) alongside rising crude oil (+2.01%) is notable. When energy prices rise and gold falls simultaneously, markets are typically pricing a growth-expansion environment rather than a crisis or inflationary shock. Gold has now retraced roughly 25% from its all-time high above $5,500, suggesting that the safe-haven bid which drove it to record levels earlier in the cycle is fading as overnight rates remain stable and no acute geopolitical shock has materialized yet — despite Iran-US nuclear talks resuming this week.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,743.41 | +0.51% | 95.1% |  |
| ^IXIC | NASDAQ | 27,068.72 | +0.48% | 96.7% |  |
| ^DJI | Dow Jones | 51,828.62 | +0.93% | 69.9% |  |
| ^RUT | Russell 2000 (US small-cap) | 2,837.55 | +0.07% | 69.7% |  |
| ^GDAXI | DAX (Germany, EUR) | 25,473.45 | +0.26% | 75.9% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,743.20 | +0.45% | 85.7% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 65,877.62 | −0.73% | 75.6% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 6,889.74 | −2.70% | 58.2% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 48,024.60 | −0.28% | 97.5% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 24,642.51 | +0.54% | 38.4% |  |
| ^FVX | US 5Y yield | 5.052% | +0.90% | 99.5% | |
| ^TNX | US 10Y yield | 5.217% | +0.64% | 99.0% | |
| ^TYX | US 30Y yield | 5.530% | +0.47% | 99.7% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 101.19 | +0.22% | 90.3% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,183.30 | −3.19% | 22.1% |  |
| SI=F | Silver | 61.64 | −4.88% | 21.4% | 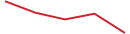 |
| CL=F | WTI Crude | 94.27 | +2.01% | 60.9% | 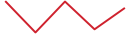 |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,694.00 | +1.33% | 67.7% | S |  |
| KC=F | Coffee | 284.55 | +2.14% | 21.4% | T |  |
| ZS=F | Soybeans | 1,295.00 | −1.82% | 89.0% | T |  |
| ZC=F | Corn | 524.25 | −0.76% | 86.1% | L |  |
| ZW=F | Wheat | 696.00 | −1.03% | 71.9% | L |  |
| SB=F | Sugar | 18.78 | +1.51% | 98.2% | L |  |
| CT=F | Cotton | 82.51 | −0.24% | 69.3% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 16.02 | +7.73% |  |
| ^VXN | NASDAQ | 20.87 | −1.74% |  |
| ^GVZ | Gold | 22.44 | −0.62% |  |
| ^OVX | Crude | 55.09 | +1.18% |  |
Regime: normal (VIX 16.02).
Fear & Greed (CNN): Fear (37/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 196.27 | +0.80% | 96.6% |  |
| XLV | Health Care | 170.70 | +0.49% | 85.9% |  |
| XLF | Financials | 54.84 | +0.57% | 65.6% |  |
| XLRE | Real Estate (S&P) | 41.56 | −0.22% | 27.3% |  |
| XLE | Energy | 62.04 | −0.89% | 82.7% |  |
| XLB | Materials | 49.80 | +0.24% | 63.9% |  |
| XLI | Industrials | 170.43 | +0.95% | 56.7% |  |
| XLU | Utilities | 39.51 | +0.38% | 4.4% |  |
| XLP | Consumer Staples | 82.06 | +0.44% | 46.1% |  |
| XLY | Consumer Disc | 110.56 | +0.22% | 27.1% |  |
| XLC | Communication Svcs | 112.96 | −0.90% | 51.6% |  |
| SMH | Semiconductors | 606.56 | +1.01% | 81.7% |  |
| GLD | Gold (ETF) | 393.41 | +0.44% | 26.8% |  |
| GDX | Gold Miners | 92.87 | +0.56% | 50.4% |  |
| XME | Metals & Mining | 108.33 | +0.34% | 45.3% |  |
| OIH | Oil Services | 393.68 | −0.13% | 69.8% |  |
| XOP | Oil & Gas E&P | 181.50 | −1.39% | 75.4% |  |
| PBW | Clean Energy | 30.02 | +0.30% | 13.3% |  |
| MOO | Agribusiness | 83.27 | −0.08% | 69.8% |  |
| IBB | Biotech | 209.77 | +0.25% | 90.4% |  |
| KRE | Regional Banks | 71.55 | +0.86% | 67.3% |  |
| KIE | Insurance | 59.71 | +0.07% | 47.9% |  |
| ITB | Home Construction | 89.43 | +1.27% | 14.7% |  |
| VNQ | REITs (broad) | 90.99 | −0.20% | 27.7% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| MTN | 2026-09-28 | AH | 8.46% | — |
| JEF | 2026-09-28 | AH | 7.42% | — |
| CNXC | 2026-09-29 | AH | 17.50% | — |
| KMX | 2026-09-29 | PM | 10.66% | — |
| AIR | 2026-09-29 | AH | 9.75% | — |
| UEC | 2026-09-29 | PM | 6.66% | — |
| CCL | 2026-09-29 | PM | 5.99% | — |
| PRGS | 2026-09-30 | AH | 10.31% | — |
| FDS | 2026-09-30 | PM | 9.33% | — |
| CALM | 2026-09-30 | PM | 7.87% | — |
| JBL | 2026-09-30 | PM | 7.77% | — |
| MU | 2026-09-30 | AH | 7.29% | 3 |
| CAG | 2026-09-30 | PM | 4.61% | — |
| MKC | 2026-10-01 | PM | 7.27% | — |
| NKE | 2026-10-01 | AH | 7.06% | — |
| ACN | 2026-10-01 | PM | 6.64% | — |
See you tomorrow, 60 minutes before the open.