
Pre-Bell: VIX **calm** (14.83); SPX **+6.51% above** its 200-day SMA; NASDAQ leads US indices at +0…
Daily Market Brief — 2026-09-21
Before the bell rings — here's the tape.
VIX calm (14.83); SPX +6.51% above its 200-day SMA; NASDAQ leads US indices at +0.39%; Semiconductors (SMH) +2.21% best sector on TSMC/ASML AI-capex news; GM −5.10% biggest single-name move on auto-pricing pressure and managed-trade tariff overhang.
News (last 24h)
- [FinancialJuice, ~4h] USTR Greer: US pivots to managed trade with China (3-6 month truce possible), Mexico rules of origin, Canada globalization dispute; Iran sanctions on table
- [FinancialJuice, ~6h] Gulf states urge Iran reset; Houthi-Saudi escalation creating separate energy risk amid Middle East tensions
- [FinancialJuice, ~5h] Treasury Secretary Bessent: headline inflation only, bonds energy-correlated, yields above equilibrium; rates should fall post-conflict as PBOC/China engage on Iran
- [FinancialJuice, ~8h] SNB expected to hold policy rate at 0% at September 24 meeting and through 2027 (consensus of all 35 economists)
- [MarketWatch/FinancialJuice, ~7h] Record diesel prices exposing economic pain; Iraq ramps oil exports to 4M barrels/day with majority of Strait tanker traffic
- [Yahoo, ~3h] TSMC building tech validation lab in Kaohsiung; ASML partners with chip giants for AI chip production expansion
- [FinancialJuice/Yahoo, ~5h] Chicago Activity Index −0.04 (soft); US sentiment Risk ON; Dow rallies 450 pts, NVDA extends gains amid falling oil
- [Yahoo, ~2h] Tesla and Sunrun dispatch 580 MW to California grid during heat wave—largest residential distributed power event in history
- [Yahoo, ~4h] Meta AI glasses compatibility announced; Wells Fargo issues bull case ahead of Connect; stock jumps despite Facebook outage
- [Yahoo, ~6h] David Tepper's fund holds 40% allocation across just 3 AI stocks—high-conviction positioning in AI sector
Observations
Today's setup: The dominant story is a potential US-China managed-trade truce — a structural shift away from blanket tariffs toward negotiated terms that, if confirmed, would reduce the persistent cost headwind on US importers and supply chains. Treasury Secretary Bessent's parallel signal — that bond yields are running above equilibrium and inflation is now driven primarily by energy rather than broad demand — frames today's modest yield pullback (10-year at 4.96%, off 3-4 basis points) as the beginning of a repricing, not a one-day blip. The VIX at 14.83 is firmly in calm territory, but CNN's Fear & Greed index reads 29 (Fear) — a notable divergence that often precedes a sentiment-driven squeeze higher.
The semiconductor space is absorbing the trade-truce optimism most directly. TSMC's new tech-validation lab and ASML's expansion into AI chip production reaffirm that the AI infrastructure buildout is deepening, not plateauing. SMH gained 2.2% and Taiwan's TAIEX is trading at 97.8% of its 52-week range — a near-record level that reflects how concentrated global AI demand is in the Asian supply chain. The KOSPI in South Korea added 1.7%, reinforcing the same theme. When hyperscalers are still expanding capacity and equipment makers are still adding partnerships, the hardware tailwind remains intact.
Crude oil's 2.7% drop is the sharpest move in today's tape and contains a dual message. First, Iraq's ramp to 4 million barrels per day is contributing to supply, which on its own would be incrementally bearish for oil prices. Second — and more importantly — the market appears to be pricing in a reduction in Middle East risk premium as Iran-engagement diplomacy gains traction alongside the broader US trade-policy pivot. Normally a geopolitical escalation in the Gulf would push crude higher; today's selling suggests traders see the truce narrative as more near-term credible than the Houthi escalation risk. This matters for inflation: cheaper energy directly reduces headline CPI, which is precisely Bessent's argument for why yields should fall.
GM's 5.1% single-day decline deserves attention. The USTR announcement on Mexico rules of origin sits squarely inside the auto industry's cross-border supply chain — vehicles assembled with components from multiple countries are exactly the kind of product managed-trade rules reclassify. Add a separate report that automotive retail pricing pressure is intensifying (consumers struggling to find the best price on their next car), and you have a demand and supply-chain cost squeeze hitting simultaneously. The broader consumer sector is showing stress in today's session: utilities and home construction are trading near 52-week lows, both sensitive to the prolonged high-yield environment, while consumer staples and real estate also softened.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,650.50 | +0.17% | 88.9% | 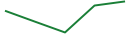 |
| ^IXIC | NASDAQ | 26,522.55 | +0.39% | 89.7% | 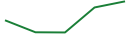 |
| ^DJI | Dow Jones | 51,682.64 | −0.18% | 68.4% | 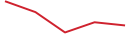 |
| ^RUT | Russell 2000 (US small-cap) | 2,860.40 | 0.00% | 72.7% | 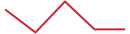 |
| ^GDAXI | DAX (Germany, EUR) | 25,591.28 | +1.14% | 78.4% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,760.87 | +0.95% | 87.4% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 65,018.95 | +1.38% | 72.6% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 7,007.72 | +1.65% | 60.5% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 47,718.84 | +1.14% | 97.8% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 25,042.71 | +1.18% | 45.6% |  |
| ^FVX | US 5Y yield | 4.825% | −0.64% | 91.9% | |
| ^TNX | US 10Y yield | 4.963% | −0.70% | 95.0% | |
| ^TYX | US 30Y yield | 5.297% | −0.64% | 85.8% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 100.262 | +0.04% | 75.4% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,396.90 | −0.63% | 36.3% |  |
| SI=F | Silver | 67.25 | +0.15% | 30.7% |  |
| CL=F | WTI Crude | 93.49 | −2.70% | 59.7% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,417.00 | +1.69% | 59.1% | S |  |
| KC=F | Coffee | 280.30 | −0.07% | 19.3% | T |  |
| ZS=F | Soybeans | 1,314.00 | +0.81% | 94.6% | T |  |
| ZC=F | Corn | 533.25 | +1.09% | 95.7% | L |  |
| ZW=F | Wheat | 721.75 | +1.05% | 80.9% | L |  |
| SB=F | Sugar | 18.45 | +1.15% | 92.4% | L |  |
| CT=F | Cotton | 83.49 | −1.17% | 72.4% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 14.83 | +0.14% |  |
| ^VXN | NASDAQ | 19.29 | −3.36% |  |
| ^GVZ | Gold | 23.31 | −6.69% |  |
| ^OVX | Crude | 50.39 | −3.30% |  |
Regime: calm (VIX-band).
Fear & Greed (CNN): Fear (29/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 189.60 | +0.82% | 87.3% |  |
| XLV | Health Care | 168.39 | −0.25% | 80.8% |  |
| XLF | Financials | 55.86 | −0.04% | 74.9% |  |
| XLRE | Real Estate (S&P) | 42.53 | −0.95% | 41.7% |  |
| XLE | Energy | 64.31 | −0.26% | 92.2% |  |
| XLB | Materials | 49.99 | −1.42% | 65.4% |  |
| XLI | Industrials | 169.75 | +0.44% | 55.1% |  |
| XLU | Utilities | 41.10 | −1.42% | 0.3% |  |
| XLP | Consumer Staples | 82.80 | −0.83% | 51.0% |  |
| XLY | Consumer Disc | 111.03 | −0.32% | 29.5% |  |
| XLC | Communication Svcs | 110.81 | −1.37% | 37.6% |  |
| SMH | Semiconductors | 573.00 | +2.21% | 72.4% |  |
| GLD | Gold (ETF) | 401.17 | +0.71% | 35.3% |  |
| GDX | Gold Miners | 95.48 | −0.46% | 55.8% |  |
| XME | Metals & Mining | 108.68 | −2.37% | 46.1% |  |
| OIH | Oil Services | 398.71 | −0.47% | 72.1% |  |
| XOP | Oil & Gas E&P | 190.61 | −1.03% | 86.9% |  |
| PBW | Clean Energy | 30.63 | −0.42% | 16.3% |  |
| MOO | Agribusiness | 84.64 | −1.84% | 76.7% |  |
| IBB | Biotech | 204.56 | −1.21% | 84.0% |  |
| KRE | Regional Banks | 72.75 | +0.01% | 73.1% |  |
| KIE | Insurance | 61.95 | −0.75% | 65.0% |  |
| ITB | Home Construction | 87.41 | −1.29% | 8.0% |  |
| VNQ | REITs (broad) | 92.91 | −0.96% | 40.6% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| ABVX | 2026-09-21 | AH | ±7.24% | — |
| KBH | 2026-09-22 | AH | ±8.61% | — |
| AZO | 2026-09-22 | PM | ±8.26% | — |
| NEOV | 2026-09-23 | AH | ±39.89% | — |
| SFIX | 2026-09-23 | AH | ±18.06% | — |
| CBRL | 2026-09-23 | PM | ±12.94% | — |
| MANU | 2026-09-23 | PM | ±8.11% | — |
| GIS | 2026-09-23 | PM | ±7.52% | 3 |
| PAYX | 2026-09-23 | PM | ±6.76% | — |
| CTAS | 2026-09-23 | PM | ±3.90% | — |
| BB | 2026-09-24 | PM | ±10.85% | — |
| SNX | 2026-09-24 | PM | ±7.76% | — |
| DRI | 2026-09-24 | PM | ±6.48% | — |
| COST | 2026-09-24 | AH | ±3.03% | — |
| IVA | 2026-09-25 | AH | ±54.12% | — |
See you tomorrow, 60 minutes before the open.