
Pre-Bell: VIX regime **normal** (15.71, +4.18%); SPX **+7.7% above** its 200-day SMA; US indices sl…
Daily Market Brief — 2026-10-08
Before the bell rings — here's the tape.
VIX regime normal (15.71, +4.18%); SPX +7.7% above its 200-day SMA; US indices slipped (S&P −0.22%, NASDAQ −0.22%, Russell 2000 −1.31%) while WTI jumped +4.83% and the 10Y yield pushed to 5.33%; weakest sectors: Industrials −2.18% and miners/metals (GDX −3.13%, XME −3.14%).
Macro crash watch
Capture: 2026-10-08T13:00:32.832959+00:00 (UTC). Data coverage: ok.
| Indicator | Latest | Change | Observation period |
|---|---|---|---|
| US 10Y yield | 5.27 % | +0.47 pp | 2026-10-06 |
| US 30Y yield | 5.64 % | +0.39 pp | 2026-10-06 |
| Headline CPI YoY | 3.40 % | -0.85 pp | 2026-08 (monthly) |
| Unemployment | 4.20 % | +0.00 pp | 2026-09 (monthly) |
| WTI spot | 96.24 $/bbl | +2.15 % | 2026-10-06 |
| Brent spot | 125.44 $/bbl | +18.21 % | 2026-10-06 |
Change windows: 20 available daily observations; 3 calendar months for CPI and unemployment. pp means percentage points. Monthly data are rechecked daily, not newly measured daily.
- Falling 10Y/30Y yields with rising CPI inflation: Not observed.
- Falling 10Y/30Y yields with rising WTI (oil proxy): Not observed.
- Rising long yields with rising CPI inflation: Not observed.
- Rising unemployment: Not observed.
These are unvalidated warning patterns, not a crash forecast or an all-clear. Falling inflation and yields can accompany either relief or an existing downturn. The complete sequence of phases is not a calibrated forecast. Oil spot prices are a proxy, not the futures contracts shown in the source video.
Tech earnings versus expectations
| Company | Fiscal quarter | Expected EPS | Actual EPS | Surprise |
|---|---|---|---|---|
| AAPL | FY2026 Q3 | 1.9271 | 1.9100 | -0.89% |
| MSFT | FY2026 Q4 | 4.3274 | 4.7400 | +9.53% |
| NVDA | FY2027 Q2 | 2.1384 | 2.2200 | +3.82% |
| GOOGL | FY2026 Q2 | 2.9798 | 2.8500 | -4.36% |
| META | FY2026 Q2 | 7.3594 | 6.1800 | 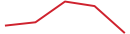 |
| AMZN | FY2026 Q2 | 1.8563 | 1.9700 | +6.13% |
| AMD | FY2026 Q2 | 1.6313 | 1.6600 | +1.76% |
| AVGO | FY2026 Q3 | 3.3013 | 3.3200 | +0.57% |
Latest reported quarters: 5 beats, 3 misses, 0 meets, covering 8/8 companies. Quarters differ by company; counts are equally weighted, not index EPS growth.
Source: Finnhub earnings surprises; captured 2026-10-08T13:00:37.905679+00:00. EPS values are provider-paired actuals and consensus estimates (USD/share); accounting basis and historical consensus timestamp are unspecified. These are vendor-reported expectations, not independently archived pre-release estimates. Company fiscal periods are not announcement dates. The selected basket spans several sectors; results do not represent the entire technology sector. Positive surprises alone do not establish that a crash is unlikely.
Pre-release expectation archive: ok; 7 upcoming quarterly records captured today. These timestamped estimates are kept before the expected reporting date for future verification; schedule dates and accounting basis still require confirmation.
Historical validation
Retrospective monthly decisions, 2006–2025, using ALFRED publication vintages: falling 10Y/30Y yields with rising CPI inflation preceded a ≥20% S&P 500 fall within 126 sessions in 4/56 warning months (7.14%), versus 6.75% across 237 eligible months. 52 warning months did not meet that outcome. Overlapping observations are not independent; these historical frequencies are not today’s crash probability. The pattern has not established reliable predictive value.
Broad-market trend and correction context
| Index | Daily close date | Drawdown | Bars | Completed period | EMA20 | EMA100 | Close below EMA20 | EMA20 below EMA100 |
|---|---|---|---|---|---|---|---|---|
| S&P 500 | 2026-10-07 | -0.22% | weekly | 2026-10-02 | 7540.09 | 6673.23 | no | no |
| S&P 500 | 2026-10-07 | -0.22% | monthly | 2026-09-30 | 6821.98 | 4833.64 | no | no |
| NASDAQ Composite | 2026-10-07 | -0.22% | weekly | 2026-10-02 | 26017.81 | 22464.06 | no | no |
| NASDAQ Composite | 2026-10-07 | -0.22% | monthly | 2026-09-30 | 23080.77 | 15433.25 | no | no |
Only completed weeks/months and prior-day final closes are used; period dates label calendar bar ends. EMA20/100 means 20/100 weeks or months, respectively. These lagging trend measures do not predict recovery duration. The owner’s research question is whether a decline of up to 15% is a correction or the start of a prolonged bear market; no automatic sell or re-entry signal is established. Sources: Yahoo index history (^GSPC, ^IXIC); raw captures are archived.
Conditional correction forecast
keine belastbare Prognose verfügbar — no reliable forecast available.
Evidence status: unqualified. Model: correction-logistic-v1-9e2b52269d8c. Training cutoff: 2026-10-06. ET capture date: 2026-10-08; generated: 2026-10-08T13:01:10.506589+00:00.
Target: extra_loss_20pct_in_9m_and_peak_recovery_24m.
- No independent scientific review or operational qualification
- Minimum ten positive independent terminal episodes not established
- Current earnings consensus unavailable historically; no validated re-entry signal
- Known historical crises are retrospective, not blind tests
- Model not approved; research estimates are not operational probabilities.
| Input | Observation period | Available at | Source |
|---|---|---|---|
| DGS10 | 2026-10-06 | 2026-10-08T13:00:32.832959+00:00 | source |
| DGS30 | 2026-10-06 | 2026-10-08T13:00:32.832959+00:00 | source |
| DGS2 | 2026-10-06 | 2026-10-08T13:00:32.832959+00:00 | source |
| DFEDTARU | 2026-10-08 | 2026-10-08T13:00:32.832959+00:00 | source |
| CPI_YOY | 2026-08-01 | 2026-10-08T13:00:32.832959+00:00 | source |
| UNRATE | 2026-09-01 | 2026-10-08T13:00:32.832959+00:00 | source |
| DCOILWTICO | 2026-10-06 | 2026-10-08T13:00:32.832959+00:00 | source |
| DCOILBRENTEU | 2026-10-06 | 2026-10-08T13:00:32.832959+00:00 | source |
| sp500 | 2026-10-07 | 2026-10-08T13:01:09.181367+00:00 | source |
| nasdaq_composite | 2026-10-07 | 2026-10-08T13:01:09.181367+00:00 | source |
Tech earnings remain current context only; historical consensus/basis is not validated.
Missing evidence is not an all-clear. A recovery or EMA100 reclaim is not a tested buy signal. The target concerns the broad price index, not individual shares or portfolio returns.
Correction versus prolonged bear market
Historical S&P 500 declines first crossing 15%: 8 episodes since 1990; 2 had both a further ≥20% decline within 189 sessions and at least 24 months from the old peak until recovery. Both indices were below their weekly EMA20 in all 7 episodes with adequate EMA history, including fast recoveries. The stricter price < EMA20 < EMA100 configuration in both indices was present in 0 of those episodes at the first 15% crossing; later confirmation can exceed the desired exit-loss limit. These small retrospective counts do not calibrate a probability or establish a sell/re-entry rule.
News (last 24h)
- [FinancialJuice, <24h] US Initial Jobless Claims 197k (forecast 200k, previous 197k revised to 199k)
- [FinancialJuice, <24h] Goldman Sachs: September FOMC minutes reinforce hawkish bias, but a December hike remains data-dependent
- [FinancialJuice, <24h] Yemen's Houthis attacked King Khalid Airport in Riyadh with a ballistic missile
- [FinancialJuice, <24h] BoE's Bailey: markets display an elevated risk premium; leveraged positions could shift fast
- [FinancialJuice, <24h] JPMorgan: G7 emergency release targets diesel, but much of the headline volume appears previously committed
- [FinancialJuice, <24h] US sentiment: risk-off bias remains, with geopolitics and energy supply in focus
- [FinancialJuice, <24h] BoE's Bailey: inflation risks rise if high energy prices persist; fiscal policy must be credible
- [MarketWatch, <24h] Rising yields are quietly crashing the stock market's earlier winners of 2026
- [Yahoo, <24h] TSMC gives AI trade an upbeat signal — AMD and other chip stocks fall anyway
- [FinancialJuice, <24h] Google Cloud: agent can run on Gemini or Claude models
Observations
Today's setup: Wall Street heads into the open slightly lower, with the S&P 500 and NASDAQ each down 0.22% and small caps weaker at −1.31%. Two forces dominate: bond yields pressing fresh highs (10-year at 5.33%) after Federal Reserve minutes that read hawkish, and a jump in crude oil (+4.83% to $92.54) following a missile attack on Riyadh's airport. Volatility is still in the "normal" band (VIX 15.71), and the market remains 7.7% above its 200-day average.
Rates and the dollar. Yields across the curve are within a hair of 52-week highs, with the 5-year up about 5.6 basis points and the 30-year about 3.3 — a broad lift rather than a flattening. Higher yields normally pressure long-duration assets, and that shows up in rate-sensitive pockets: real estate (−1.29%), homebuilders (−2.59%, near a 52-week low) and regional banks (−1.68%). Technology is holding up better (XLK −0.30%, still near its 52-week high), helped by TSMC's upbeat read-through, a sign that investors are still paying for the AI theme even as financing costs climb. Jobless claims of 197,000 came in under the 200,000 forecast, which keeps the labor market tight and the rate debate alive.
Energy and geopolitics. A Houthi missile strike on Riyadh's King Khalid Airport put a geopolitical premium back into crude. Typically such shocks lift oil and gold and push Treasury yields lower; today only oil follows the script. Energy equities barely reacted (XLE −0.61%, XOP −0.12%) and oil services fell 2.53%, suggesting equity investors are not extrapolating the spike. Gold held flat in futures but gold ETFs fell 1.67% and miners 3.13%, as higher yields and a firm dollar raised the opportunity cost of holding it.
Global tape. Asia sold off broadly — KOSPI −2.62% (nearly 5% lower on the week), Nikkei −1.42%, Hang Seng −1.43% — and Europe followed, with the DAX −0.80%. Industrials (−2.18%) and metals/mining (−3.14%) were the weakest US groups; health care (+1.03%) was the lone meaningful gainer, a defensive tilt consistent with a cautious Fear-reading on sentiment gauges (CNN 45/100).
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,801.77 | -0.22% | 97% | 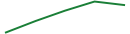 |
| ^IXIC | NASDAQ | 27,538.69 | -0.22% | 97% | 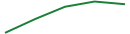 |
| ^DJI | Dow Jones | 51,179.87 | -0.66% | 63% | 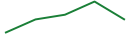 |
| ^RUT | Russell 2000 (US small-cap) | 2,793.20 | -1.31% | 64% |  |
| ^GDAXI | DAX (Germany, EUR) | 24,904.35 | -0.80% | 64% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,454.73 | -0.04% | 69% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 69,042.11 | -1.42% | 86% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 6,625.93 | -2.62% | 53% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 49,313.44 | -0.99% | 97% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 23,785.79 | -1.43% | 23% |  |
| ^FVX | US 5Y yield | 5.077% | +1.12% | 98% | |
| ^TNX | US 10Y yield | 5.326% | +0.93% | 97% | |
| ^TYX | US 30Y yield | 5.694% | +0.58% | 97% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 102.36 | +0.12% | 97% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,140.30 | -0.01% | 14% |  |
| SI=F | Silver | 59.02 | -1.48% | 17% |  |
| CL=F | WTI Crude | 92.54 | +4.83% | 58% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (October) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,513.00 | -1.24% | 70% | T |  |
| KC=F | Coffee | 287.35 | -1.83% | 23% | T |  |
| ZS=F | Soybeans | 1,292.00 | -0.42% | 88% | L |  |
| ZC=F | Corn | 501.75 | -0.05% | 71% | S |  |
| ZW=F | Wheat | 687.25 | +0.11% | 69% | T |  |
| SB=F | Sugar | 20.47 | -1.73% | 90% | T |  |
| CT=F | Cotton | 80.65 | +5.70% | 63% | T |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 15.71 | +4.18% |  |
| ^VXN | NASDAQ | 21.00 | -0.71% |  |
| ^GVZ | Gold | 23.39 | +1.83% |  |
| ^OVX | Crude | 48.61 | -0.37% |  |
Regime: normal (VIX-band; see Step 5).
Fear & Greed (CNN): Fear (45/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 201.39 | -0.30% | 98% |  |
| XLV | Health Care | 168.81 | +1.03% | 78% |  |
| XLF | Financials | 53.75 | -0.48% | 56% |  |
| XLRE | Real Estate (S&P) | 40.57 | -1.29% | 13% |  |
| XLE | Energy | 63.36 | -0.61% | 88% |  |
| XLB | Materials | 48.98 | -1.51% | 57% |  |
| XLI | Industrials | 167.84 | -2.18% | 50% |  |
| XLU | Utilities | 41.15 | -0.02% | 24% |  |
| XLP | Consumer Staples | 81.70 | -0.12% | 44% |  |
| XLY | Consumer Disc | 111.36 | -0.32% | 31% |  |
| XLC | Communication Svcs | 111.26 | -0.35% | 41% |  |
| SMH | Semiconductors | 625.03 | -1.18% | 87% |  |
| GLD | Gold (ETF) | 375.88 | -1.67% | 11% |  |
| GDX | Gold Miners | 85.46 | -3.13% | 35% |  |
| XME | Metals & Mining | 104.84 | -3.14% | 38% |  |
| OIH | Oil Services | 381.54 | -2.53% | 64% |  |
| XOP | Oil & Gas E&P | 188.24 | -0.12% | 84% |  |
| PBW | Clean Energy | 28.92 | -2.89% | 8% |  |
| MOO | Agribusiness | 81.23 | -1.42% | 60% |  |
| IBB | Biotech | 203.34 | +0.12% | 80% |  |
| KRE | Regional Banks | 68.89 | -1.68% | 55% |  |
| KIE | Insurance | 59.53 | -0.40% | 46% |  |
| ITB | Home Construction | 84.70 | -2.59% | 3% |  |
| VNQ | REITs (broad) | 88.69 | -1.38% | 12% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| BYRN | 2026-10-08 | PM | 46.47% | |
| HELE | 2026-10-08 | PM | 14.26% | |
| NG | 2026-10-08 | PM | 11.03% | |
| ANGO | 2026-10-08 | PM | 10.15% | |
| TLRY | 2026-10-08 | PM | 9.30% | |
| PEP | 2026-10-08 | PM | 3.21% | |
| DAL | 2026-10-09 | PM | 5.45% |
See you tomorrow, 60 minutes before the open.