
Pre-Bell: VIX **normal** at 16.33; SPX **+6.0% above** its 200-day SMA; Nikkei **+3.30%** leads ind…
Daily Market Brief — 2026-10-01
Before the bell rings — here's the tape.
VIX normal at 16.33; SPX +6.0% above its 200-day SMA; Nikkei +3.30% leads indices; KIE −1.65% is the largest sector-ETF move. US stock and ETF returns: September 30 close; international indices and futures: latest available quotes.
News (last 24h)
- [FinancialJuice, ≤24h] Israel's Prime Minister Netanyahu: There are indications that Iran and proxies want to attack Israel
- [MarketWatch / FinancialJuice, ≤24h] How European supplies could impact a U.S. diesel ban as White House reportedly asks Germany, France to release stockpiles
- [FinancialJuice, ≤24h] US Initial Jobless Claims Actual 197k (Forecast 200k, Previous 197k, Revised 198K)
- [MarketWatch, ≤24h] The latest oil-price shock rippling through the economy is a refining crisis — not a crude crisis
- [FinancialJuice, ≤24h] BoE's Mann: Can't rely on risk premia to do the work of monetary policy, need to raise the bank rate
- [Yahoo, ≤24h] TSMC Mulls Multibillion-Dollar Texas Campus for More AI Chips
- [Yahoo, ≤24h] BYD, Leapmotor Continue EV Sales Streak; Tesla Deliveries On Deck
- [FinancialJuice, ≤24h] USTR Greer: Gaps remain between US and Canada on trade.
- [MarketWatch, ≤24h] Google is sending its first AI data center to space
- [Yahoo, ≤24h] Detroit Three automakers set to lose market share to Asian rivals
Observations
Today's setup: Technology is carrying a mixed tape: the Nikkei gained 3.30%, while the latest US close left the NASDAQ up 0.24% and the S&P 500 down 0.25%. The S&P remains 6.0% above its 200-day average, but that trend strength coexists with weakness in housing, real estate and financials. Long Treasury yields remain high as the dollar firms, while Middle East and diesel-supply headlines keep energy costs in focus. VIX is in its normal band at 16.33, even as NASDAQ implied volatility rises alongside the index.
Rates and the dollar. The 30-year Treasury yield rose 1.4 basis points to 5.652%, the 10-year held at 5.293%, and the five-year fell 1.2 basis points to 5.077%. That widened the five-to-30-year spread by 2.6 basis points to 57.5 basis points: steepening driven by opposing moves at the two ends. Higher long-term rates raise mortgage costs and discount future property and utility cash flows, a channel consistent with homebuilders losing 1.54% and real-estate funds roughly 1%. The dollar's 0.33% gain aligns with the long end; stronger US yields can attract capital, though the falling five-year shows this is not a uniform repricing of rates. Insurance fell 1.65%, contrary to the usual benefit that higher reinvestment yields offer insurers.
AI strength is selective. In the current infrastructure investment cycle, spending on compute supports chipmakers and equipment suppliers while committing substantial cash at the companies funding the build-out. Asian chip-gains coverage and a reported prospective US foundry expansion fit that backdrop. US technology gained 0.64% and semiconductors 0.35%, while industrials and utilities fell; the demand channel does not lift every related sector together. Technology sits near the top of its 52-week range, while homebuilders and utilities remain near the bottom, underscoring the split between investment-led growth and rate-sensitive cash flows.
Energy costs have more than one bottleneck. Reports about diesel restrictions and European stockpile releases point to the distinction between crude availability and the ability to refine and deliver usable fuel. A refinery's margin depends on product prices relative to its crude input; higher crude alone does not establish stronger refining profits. Diesel shortages can raise freight surcharges and farm transport costs, then feed into goods prices with a lag. WTI's 1.44% rise and the Iran-risk headlines are consistent with supply-risk concerns, but the accompanying Asian equity gains and firmer long Treasury yield do not show the full defensive pattern usually associated with an acute geopolitical shock. Silver rose 2.35% and gold futures 0.57% despite the stronger dollar, diverging from the usual currency headwind for dollar-priced metals.
Volatility is firmer beneath the headline band. VIX edged down 0.06% even though the latest S&P close was lower, while NASDAQ volatility rose 1.77% alongside a positive index return. Equity prices and implied volatility normally move in opposite directions, so these readings indicate an uneven response across markets rather than a broad surge in fear. Over five sessions VIX is up 9.82%, yet its level remains in the normal band. CNN's Fear & Greed reading is Fear at 31/100: a sentiment counterpoint to the strength in technology, not a forecast.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,651.54 | -0.25% | 89.0% | 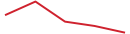 |
| ^IXIC | NASDAQ Composite | 26,861.06 | +0.24% | 93.5% | 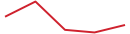 |
| ^DJI | Dow Jones | 50,906.05 | -0.86% | 60.4% | 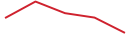 |
| ^RUT | Russell 2000 (US small-cap) | 2,796.86 | -0.39% | 64.4% | 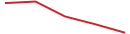 |
| ^GDAXI | DAX (Germany, EUR) | 25,187.79 | -0.05% | 69.9% | 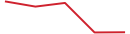 |
| ^FTSE | FTSE 100 (UK, GBP) | 10,521.74 | -0.79% | 72.7% | 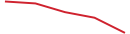 |
| ^N225 | Nikkei 225 (Japan, JPY) | 68,956.72 | +3.30% | 86.2% | 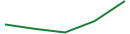 |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 6,971.35 | +1.95% | 58.9% | 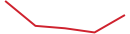 |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 48,353.49 | +0.86% | 98.9% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 24,613.27 | +0.37% | 37.8% |  |
| ^FVX | US 5Y yield | 5.077% | -0.24% | 97.9% | |
| ^TNX | US 10Y yield | 5.293% | +0.00% | 99.0% | |
| ^TYX | US 30Y yield | 5.652% | +0.25% | 99.9% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 101.79 | +0.33% | 96.8% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,210.70 | +0.57% | 21.1% |  |
| SI=F | Silver | 61.51 | +2.35% | 21.2% | 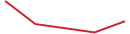 |
| CL=F | WTI Crude | 91.72 | +1.44% | 57.0% | 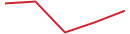 |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (October) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,090.00 | -5.16% | 58.6% | T | 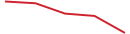 |
| KC=F | Coffee | 286.20 | -1.55% | 22.3% | T | 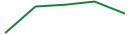 |
| ZS=F | Soybeans | 1,289.50 | -0.27% | 87.1% | L | 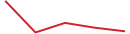 |
| ZC=F | Corn | 502.25 | +0.30% | 71.1% | S | 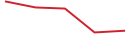 |
| ZW=F | Wheat | 680.25 | +0.67% | 66.3% | T | 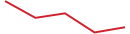 |
| SB=F | Sugar | 18.75 | +6.35% | 95.7% | T | 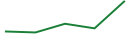 |
| CT=F | Cotton | 78.44 | +4.88% | 56.4% | T |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 16.33 | -0.06% |  |
| ^VXN | NASDAQ | 22.46 | +1.77% |  |
| ^GVZ | Gold | 23.74 | -2.59% |  |
| ^OVX | Crude | 52.24 | -2.79% |  |
Regime: normal (VIX-band).
Fear & Greed (CNN): Fear (31/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 195.75 | +0.64% | 95.9% |  |
| XLV | Health Care | 168.42 | -1.35% | 77.0% |  |
| XLF | Financials | 53.40 | -1.13% | 52.4% |  |
| XLRE | Real Estate (S&P) | 40.91 | -1.04% | 17.6% | 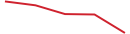 |
| XLE | Energy | 61.50 | -0.06% | 80.4% | 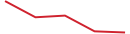 |
| XLB | Materials | 48.70 | -0.81% | 54.8% | 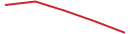 |
| XLI | Industrials | 166.98 | -1.27% | 48.3% | 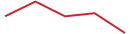 |
| XLU | Utilities | 39.44 | -0.68% | 4.7% |  |
| XLP | Consumer Staples | 80.60 | -1.53% | 36.3% |  |
| XLY | Consumer Discretionary | 108.84 | -0.28% | 18.4% |  |
| XLC | Communication Services | 110.97 | -0.45% | 38.6% |  |
| SMH | Semiconductors | 609.00 | +0.35% | 82.4% |  |
| GLD | Gold (ETF) | 380.84 | -0.54% | 18.6% |  |
| GDX | Gold Miners | 87.80 | -1.43% | 40.1% |  |
| XME | Metals & Mining | 103.56 | -0.33% | 35.8% |  |
| OIH | Oil Services | 378.37 | -0.50% | 62.7% |  |
| XOP | Oil & Gas E&P | 179.33 | +0.39% | 72.6% |  |
| PBW | Clean Energy | 29.07 | -0.17% | 8.5% |  |
| MOO | Agribusiness | 81.47 | -0.80% | 60.8% |  |
| IBB | Biotech | 210.53 | -0.24% | 90.5% |  |
| KRE | Regional Banks | 69.44 | -0.56% | 57.2% |  |
| KIE | Insurance | 58.50 | -1.65% | 38.6% |  |
| ITB | Home Construction | 87.02 | -1.54% | 6.7% |  |
| VNQ | REITs (broad) | 89.63 | -0.99% | 18.6% |  |
Quotes in native units: Treasury yields in percent; coffee, grains, sugar and cotton in US cents per exchange quotation unit. US stocks and ETFs reflect September 30 close; futures and international indices use latest available quotes. Week charts cover five trading sessions; each uses its own scale.
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| NKE | 2026-10-01 | AH | 7.29% | |
| MKC | 2026-10-01 | PM | 6.34% | |
| ACN | 2026-10-01 | PM | 6.06% |
See you tomorrow, 60 minutes before the open.