
Pre-Bell: VIX **normal** (15.83); SPX **+6.34% above** its 200-day SMA; Nikkei **+1.94%**, the larg…
Daily Market Brief — 2026-09-30
Before the bell rings — here's the tape.
VIX normal (15.83); SPX +6.34% above its 200-day SMA; Nikkei +1.94%, the largest index move; oil services (OIH) −2.44%, the largest sector ETF move. Latest US cash session: September 29; international markets and futures: latest available quotes.
News (last 24h)
- [FinancialJuice, MarketWatch, Yahoo, last 24h] US Core PCE Price Index YoY Actual 3% (Forecast 3.3%, Previous 3.3%, Revision 3%)
- [FinancialJuice, last 24h] US GDP QoQ Final Actual 2.2% (Forecast 1.5%, Previous 1.5%)
- [FinancialJuice, last 24h] US 2025 GDP growth revised to +2.3% from +2.1%.
- [FinancialJuice, last 24h] German CPI YoY Prelim Actual 3.3% (Forecast 3.1%, Previous 2.90%)
- [FinancialJuice, last 24h] US ADP Employment Change Actual 90k (Forecast 74.5k, Previous 38k, Prior Revision 36k)
- [FinancialJuice, last 24h] US Real Personal Consumption MoM Actual 0.6% (Forecast 0.5%, Previous 0.0%)
- [FinancialJuice, last 24h] US Advance Goods Trade Balance Actual -132.6B (Forecast -115B, Previous -118.94B)
- [FinancialJuice, last 24h] US Personal Income MoM Actual 0.2% (Forecast 0.5%, Previous 0.4%)
- [Yahoo, last 24h] Tesla’s Cash Crunch Has Arrived—Blame Its AI Ambitions
- [Yahoo, last 24h] Taiwan Semiconductor Manufacturing Reportedly Weighing Texas Investment to Boost US Chip Production
Observations
Today's setup: Lower US Treasury yields and a softer dollar sit alongside a modestly weaker US cash-equity tape and gains in precious metals. Core PCE at 3.0%, below the reported 3.3% consensus, points toward less inflation pressure, while GDP and private payrolls beat expectations. The Nikkei leads the international indices at +1.94%; oil services are the weakest sector ETF at −2.44%. The key divergence is rising crude alongside falling energy equities, while VIX remains in its normal band.
Rates and growth. Five-, ten- and thirty-year Treasury yields fell 2.7, 1.7 and 0.7 basis points respectively. The five-to-ten-year spread widened to 20.2 basis points, and the ten-to-thirty-year spread reached 34.9 basis points: yields fell more at shorter maturities, a bull-steepening pattern. That shape is consistent with easier policy expectations, and the dollar’s 0.25% decline fits the same direction of travel. Stronger growth and employment releases complicate the inflation relief; this is a repricing pattern, rather than a policy announcement.
Metals and energy. A weaker dollar makes dollar-priced commodities cheaper for overseas buyers, helping explain the alignment of gold +1.55% and silver +1.54%. Gold miners gained 1.34%, barely ahead of the bullion ETF’s 1.32%, so the recovery shows little of miners’ usual operating leverage. WTI rose 1.11%, but energy, exploration and oil-services ETFs fell; the usual link from higher crude to stronger producer economics is absent in these snapshots. Futures and cash-equity returns cover different market hours, which limits what that divergence says about the response to a single catalyst.
Uneven equity relief. Lower long-term yields normally ease the discount-rate burden on utilities, property and homebuilders. Utilities gained 1.17%, yet remain near the bottom of their annual range; homebuilders and property ETFs stayed slightly lower, while technology sits near the top of its range. Semiconductors’ 1.15% gain fits the current AI infrastructure cycle, where spending reaches chip suppliers and power demand, but that cycle also raises fixed costs and consumes cash at the buyers. Sector returns therefore show selective strength rather than broad participation in rate relief.
Volatility and sentiment. VIX at 15.83 and CNN’s Fear reading of 29/100 describe different aspects of risk: the first prices expected equity fluctuations, while the second combines broader sentiment measures. VIX fell even as the S&P 500 slipped, a departure from the usual pattern in which falling equities raise implied volatility. Gold-option volatility also eased during the metals rebound, and crude-option volatility fell 4.22% to 53.74; commodity option uncertainty can move differently from the underlying price.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7670.84 | -0.17% | 90.27% |  |
| ^IXIC | NASDAQ Composite | 26797.54 | -0.09% | 92.56% |  |
| ^DJI | Dow Jones | 51349.92 | -0.26% | 64.96% |  |
| ^RUT | Russell 2000 (US small-cap) | 2807.92 | -0.35% | 65.84% |  |
| ^GDAXI | DAX (Germany, EUR) | 25350.46 | -0.19% | 73.33% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10648.63 | +0.11% | 80.10% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 66753.72 | +1.94% | 78.65% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 6838.04 | -0.48% | 57.15% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 47940.13 | +0.65% | 97.08% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 24613.27 | +0.37% | 37.83% |  |
| ^FVX | US 5Y yield | 5.036% | -0.53% | 95.32% | |
| ^TNX | US 10Y yield | 5.238% | -0.32% | 95.91% | |
| ^TYX | US 30Y yield | 5.587% | -0.13% | 96.89% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 101.11 | -0.25% | 88.99% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4244.40 | +1.55% | 23.04% |  |
| SI=F | Silver | 61.60 | +1.54% | 21.36% |  |
| CL=F | WTI Crude | 90.37 | +1.11% | 54.87% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5375.00 | -0.61% | 64.06% | S |  |
| KC=F | Coffee | 296.10 | +2.30% | 27.35% | T |  |
| ZS=F | Soybeans | 1305.25 | +0.58% | 92.02% | T |  |
| ZC=F | Corn | 524.75 | +0.53% | 86.47% | L |  |
| ZW=F | Wheat | 698.50 | +0.83% | 72.75% | L |  |
| SB=F | Sugar | 18.64 | +4.60% | 91.86% | L |  |
| CT=F | Cotton | 79.14 | +5.34% | 58.62% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 15.83 | -1.31% |  |
| ^VXN | NASDAQ | 22.07 | -0.27% |  |
| ^GVZ | Gold | 24.37 | -1.85% |  |
| ^OVX | Crude | 53.74 | -4.22% | 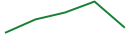 |
Regime: normal (VIX-band).
Fear & Greed (CNN): Fear (29/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 194.50 | -0.02% | 94.13% | 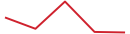 |
| XLV | Health Care | 170.73 | -0.31% | 84.14% | 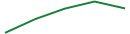 |
| XLF | Financials | 54.01 | -0.33% | 58.01% | 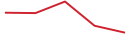 |
| XLRE | Real Estate (S&P) | 41.34 | -0.02% | 24.00% |  |
| XLE | Energy | 61.54 | -0.90% | 80.56% |  |
| XLB | Materials | 49.10 | -0.75% | 58.12% |  |
| XLI | Industrials | 169.13 | +0.21% | 53.57% |  |
| XLU | Utilities | 39.71 | +1.17% | 7.75% |  |
| XLP | Consumer Staples | 81.85 | -0.52% | 44.66% |  |
| XLY | Consumer Disc | 109.15 | +0.14% | 19.98% |  |
| XLC | Communication Svcs | 111.47 | +0.26% | 41.89% |  |
| SMH | Semiconductors | 606.90 | +1.15% | 81.80% |  |
| GLD | Gold (ETF) | 382.89 | +1.32% | 19.89% |  |
| GDX | Gold Miners | 89.07 | +1.34% | 42.69% |  |
| XME | Metals & Mining | 103.90 | -1.44% | 36.50% |  |
| OIH | Oil Services | 380.26 | -2.44% | 63.59% |  |
| XOP | Oil & Gas E&P | 178.63 | -0.84% | 71.74% |  |
| PBW | Clean Energy | 29.12 | +0.52% | 8.72% |  |
| MOO | Agribusiness | 82.13 | -1.14% | 64.11% |  |
| IBB | Biotech | 211.04 | +0.16% | 91.61% |  |
| KRE | Regional Banks | 69.83 | -1.02% | 59.04% |  |
| KIE | Insurance | 59.48 | +0.15% | 46.10% |  |
| ITB | Home Construction | 88.38 | -0.42% | 11.23% |  |
| VNQ | REITs (broad) | 90.53 | -0.07% | 24.67% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| PRGS | 2026-09-30 | AH | 10.82% | |
| FDS | 2026-09-30 | PM | 7.38% | |
| JBL | 2026-09-30 | PM | 6.58% | |
| CALM | 2026-09-30 | PM | 6.54% | |
| MU | 2026-09-30 | AH | 6.44% | 3 |
| CAG | 2026-09-30 | PM | 3.84% | |
| NKE | 2026-10-01 | AH | 7.35% | |
| MKC | 2026-10-01 | PM | 6.90% | |
| ACN | 2026-10-01 | PM | 6.17% |
See you tomorrow, 60 minutes before the open.