
Pre-Bell: VIX **normal** (15.52); SPX **+6.39% above** its 200-day SMA; NASDAQ leads US indices at…
Daily Market Brief — 2026-09-18
Before the bell rings — here's the tape.
VIX normal (15.52); SPX +6.39% above its 200-day SMA; NASDAQ leads US indices at +1.69%; XLK best broad sector at +2.25%; BoJ split rate hike sends JPY sharply higher.
News (last 24h)
- [FinancialJuice, today] BoJ Delivers Split Rate Hike; Tech Leads as Oil Eases
- [FinancialJuice/MarketWatch, today] US Treasury Yields at 100-Year Highs; Expected to Remain Elevated Into 2027
- [MarketWatch, today] Fed Signals Confidence on Economic Growth; Rare Terse Statement Suggests Market Stability
- [MarketWatch, today] Mortgage Bonds Set to Deteriorate; Wall Street Expert Warns of Systemic Spillover Risk
- [FinancialJuice, today] Saudi Arabia Cuts Crude Exports to European Refiners Next Month
- [FinancialJuice, today] ECB's Lagarde: Energy Shocks Significant but Won't Drive Rate Lockstep; Well Positioned to Respond
- [FinancialJuice, today] JP Morgan Revises ECB Forecast: Expects 25bp Hike in March 2027 After December, Not Hold
- [Yahoo, today] TSMC Ramping 2nm Production with MediaTek Wins; Stock Gains but Analyst Notes Overvaluation
- [FinancialJuice, today] Citigroup Analysis: Bank of England Policy and Rate Path Implications
- [FinancialJuice, today] Macron: France Mulling Strategic Energy Reserve Release; Will Convene G7 Energy Summit
Observations
Today's setup: Markets are navigating a tension between surging US Treasury yields — the 10-year note is approaching 4.98% and the 30-year is at 5.31%, both near levels not seen in a generation — and a resilient tech rally led by TSMC's 2nm production breakthrough with MediaTek. Despite textbook signals that would normally weigh on growth stocks (higher discount rates, duration pressure), NASDAQ gained +1.69% and the technology sector added +2.25%, driven by the AI infrastructure buildout narrative. Europe is the exception, with DAX −1.23% and FTSE −1.17%, as energy-shock uncertainty and an increasingly hawkish ECB path weigh on continental equities. The CNN Fear & Greed gauge sits at 29 (Fear territory) even as large-cap tech extends gains — a divergence that points to narrow market leadership.
Japan's central bank raised rates in a split decision, sending the yen sharply higher (yen gained roughly 1.7% against the dollar). The yen carry trade — borrowing cheaply in yen to invest in higher-yielding assets globally — faces pressure when the yen strengthens, as investors must unwind those positions. Historically this has briefly pressured US equities and risk assets; today the Nikkei absorbed the shock well at +1.38%, suggesting the market is digesting rather than panicking. Still, watch for lagged cross-asset effects if the yen continues to appreciate.
WTI crude oil fell −5.14%, a notable move that runs counter to Saudi Arabia's announcement of supply cuts to European refiners. When supply is being tightened but prices still fall, it typically reflects demand-side weakness the market considers more powerful than the supply adjustment — a soft global growth read embedded in today's oil price. Energy equities showed resilience (XLE +0.70%) relative to the crude drop, and crude implied volatility compressed sharply (−9.36%), suggesting the move is being treated as a re-pricing rather than a disruption.
The mortgage bond warning from a Wall Street expert deserves context: with 30-year yields at 5.31%, the transmission to mortgage rates is direct and severe. Utilities (8% of their 52-week range), home builders (12% of their 52-week range), and REITs are all near yearly lows — confirming that the long-duration channel is very much in play even as tech diverges. A Wall Street analyst warning of systemic spillover from mortgage deterioration is consistent with the Fear & Greed gauge remaining depressed and warrants monitoring even on a positive tape.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,637.76 | +1.14% | 88.1% |  |
| ^IXIC | NASDAQ | 26,418.30 | +1.69% | 88.1% |  |
| ^DJI | Dow Jones | 51,778.04 | +0.61% | 69.4% |  |
| ^RUT | Russell 2000 (US small-cap) | 2,874.63 | +0.55% | 74.5% |  |
| ^GDAXI | DAX (Germany, EUR) | 25,399.14 | −1.23% | 74.4% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,689.60 | −1.17% | 83.5% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 65,018.95 | +1.38% | 72.6% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 6,894.23 | +2.66% | 58.6% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 47,180.75 | +1.93% | 95.4% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 24,750.78 | +0.60% | 40.3% |  |
| ^FVX | US 5Y yield | 4.842% | +0.85% | 93.2% | |
| ^TNX | US 10Y yield | 4.980% | +0.67% | 96.6% | |
| ^TYX | US 30Y yield | 5.311% | +0.28% | 87.4% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 100.46 | +0.24% | 78.5% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,406.00 | +0.14% | 38.6% |  |
| SI=F | Silver | 67.10 | +2.48% | 31.8% | 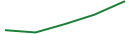 |
| CL=F | WTI Crude | 96.67 | −5.14% | 64.6% | 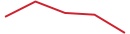 |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,514.00 | −4.47% | 60.4% | S | 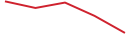 |
| KC=F | Coffee | 279.10 | −3.94% | 18.6% | T | 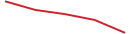 |
| ZS=F | Soybeans | 1,308.75 | −0.83% | 93.1% | T |  |
| ZC=F | Corn | 529.50 | −0.19% | 93.1% | L |  |
| ZW=F | Wheat | 723.00 | −0.55% | 81.4% | L |  |
| SB=F | Sugar | 18.49 | +6.14% | 93.1% | L |  |
| CT=F | Cotton | 81.64 | +4.12% | 66.6% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 15.52 | +0.52% |  |
| ^VXN | NASDAQ | 19.96 | −11.05% |  |
| ^GVZ | Gold | 24.98 | −5.91% |  |
| ^OVX | Crude | 52.11 | −9.36% |  |
Regime: normal (VIX 15.52).
Fear & Greed (CNN): Fear (29/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 188.06 | +2.25% | 85.2% |  |
| XLV | Health Care | 168.81 | +0.62% | 81.8% |  |
| XLF | Financials | 55.88 | −0.09% | 75.1% |  |
| XLRE | Real Estate (S&P) | 42.94 | +0.30% | 47.8% |  |
| XLE | Energy | 64.48 | +0.70% | 92.9% |  |
| XLB | Materials | 50.71 | +0.69% | 71.4% |  |
| XLI | Industrials | 169.01 | +0.18% | 53.3% |  |
| XLU | Utilities | 41.69 | +0.90% | 8.1% |  |
| XLP | Consumer Staples | 83.49 | +0.19% | 55.6% |  |
| XLY | Consumer Disc | 111.39 | +1.10% | 31.3% |  |
| XLC | Communication Svcs | 112.35 | −0.58% | 47.6% |  |
| SMH | Semiconductors | 560.61 | +2.76% | 69.0% |  |
| GLD | Gold (ETF) | 398.36 | +1.69% | 35.8% |  |
| GDX | Gold Miners | 95.92 | +3.36% | 56.7% |  |
| XME | Metals & Mining | 111.32 | +2.34% | 51.3% |  |
| OIH | Oil Services | 400.60 | +0.19% | 73.0% |  |
| XOP | Oil & Gas E&P | 192.59 | +0.41% | 89.5% |  |
| PBW | Clean Energy | 30.76 | +2.84% | 17.0% |  |
| MOO | Agribusiness | 86.23 | +1.10% | 84.6% |  |
| IBB | Biotech | 207.07 | +2.31% | 87.2% |  |
| KRE | Regional Banks | 72.74 | 0.00% | 73.0% |  |
| KIE | Insurance | 62.42 | −0.32% | 68.6% |  |
| ITB | Home Construction | 88.55 | +0.49% | 11.8% |  |
| VNQ | REITs (broad) | 93.81 | +0.35% | 46.6% |  |
Earnings & Zacks
Zacks rank changes (last 24h)
- DOWNGRADE GIS (General Mills)
2 → 3
See you tomorrow, 60 minutes before the open.