
Pre-Bell: VIX 15.98 — **normal** volatility regime; SPX **+7.15% above** its 200-day SMA; Russell 2…
Daily Market Brief — 2026-09-24
Before the bell rings — here's the tape.
VIX 15.98 — normal volatility regime; SPX +7.15% above its 200-day SMA; Russell 2000 leads US indices lower (−1.28%); duration-sensitive sectors (Utilities −2.24%, REITs −2.52%) hit hard as the 30-year Treasury yield approaches its 52-week high.
News (last 24h)
- [FJuice, today] Federal Reserve officials signal persistent inflation risk tilted upside; Hammack/Barkin on labor market and supply shocks
- [FJuice, today] US jobless claims 197k in-line; Canadian retail mixed; current account −$246B (better than forecast)
- [FJuice/Yahoo, today] Trump-Xi Summit: Current state of AI battle; Chinese CEOs in Washington, China-EU trade talks
- [FJuice, today] ECB's Radev: Inflation risks tilted upside, growth downside; rate hikes don't signal predetermined path
- [FJuice, today] Oil rebounds sharply on Iran/Hormuz tensions; Russia forecasts Urals crude $53/bbl in 2027
- [FJuice, today] Global duration selloff intensifies as oil and PMI data reprice rates across markets
- [Yahoo, today] Tesla: FSD roadblock (EU review), EU registrations +53% YoY but trail China; analyst downgrades to $268 (underperform)
- [Yahoo, today] Traders ditch Meta for cleaner AI plays; analyst resets Meta 2027 target; chip stock valuations reassessed
- [MW, today] S&P 500 'priced for perfection' faces 20% slump risk; Barclays bullish despite rising yields
- [FJuice, today] ECB's Schnabel to step down early and join IMF; leadership transition imminent
Observations
Today's setup: A hawkish Federal Reserve signal — with both Hammack and Barkin flagging persistent upside inflation risk — is driving a broad-based yield surge, with the 10-year at 5.118% and the 30-year at 5.418%, both within basis points of their 52-week highs. That moves through directly into rate-sensitive sectors, while geopolitical risk on the Iran/Hormuz front adds an oil premium and complicates the inflation picture. The broad equity tape is lower, but the texture underneath is interesting: technology is holding, defensives and yield proxies are being hit hardest, and gold is selling off despite the headlines.
When long-duration Treasury yields rise sharply — particularly at the 30-year end — the most rate-sensitive equity sectors absorb the impact first. Today's moves confirm that channel clearly: Utilities are essentially at their 52-week low (−2.24%), REITs (VNQ) are down 2.52%, and insurance stocks have lost 2.12%. This is the direct pricing effect of higher discount rates on long-duration cash flows, which is how utilities and real estate investment trusts are typically valued. The same channel also applies to mortgage rates and home financing costs, though home builders are actually holding slightly positive today — suggesting the market sees the rate move as temporary, or that homebuilder fundamentals are offsetting the macro headwind.
One notable divergence this morning: gold (GLD −1.80%) and gold miners (GDX −4.36%) are selling off sharply despite rising oil prices and geopolitical tension from Iran — conditions that would normally support the safe-haven trade. The explanation is the real-yield channel. When nominal yields rise AND the US dollar strengthens (DXY up 0.16%, at 91% of its 52-week range), gold faces dual pressure: higher opportunity cost for holding a non-yielding asset, and dollar appreciation making gold more expensive for foreign buyers. At current yield levels, that dual headwind is outweighing the geopolitical fear premium — at least for today.
On the geopolitical side, the Trump-Xi summit adds a layer of uncertainty for AI and semiconductor supply chains, with Chinese CEOs in Washington and China-EU trade talks running in parallel. Technology (XLK) is actually the brightest sector today at +0.25%, which partly reflects this resilience in AI-related demand — but the underlying chip names are softer, with the semiconductor ETF (SMH) down 1.0% and Taiwan's TAIEX near its 52-week high amid the TSMC/Cadence AI chip design partnership announcement. The interaction between AI capex optimism and tariff risk is the key tension to watch as the summit develops.
Indices & Macro
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| ^GSPC | S&P 500 | 7,706.03 | −0.76% | 92.6% | 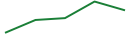 |
| ^IXIC | NASDAQ Composite | 26,936.04 | −0.69% | 94.7% | 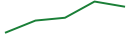 |
| ^DJI | Dow Jones Industrial Average | 51,511.59 | −1.03% | 66.7% | 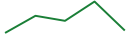 |
| ^RUT | Russell 2000 (US small-cap) | 2,838.66 | −1.28% | 69.8% | 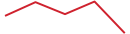 |
| ^GDAXI | DAX (Germany, EUR) | 25,336.63 | −0.29% | 73.0% |  |
| ^FTSE | FTSE 100 (UK, GBP) | 10,710.75 | +0.05% | 84.4% |  |
| ^N225 | Nikkei 225 (Japan, JPY) | 65,513.99 | +0.76% | 74.3% |  |
| ^KS11 | KOSPI (South Korea, tech-heavy, KRW) | 7,080.92 | +1.04% | 61.7% |  |
| ^TWII | TAIEX (Taiwan, tech/TSMC-heavy, TWD) | 48,024.60 | −0.28% | 97.5% |  |
| ^HSI | Hang Seng (HK / China, HKD) | 24,761.13 | −0.29% | 40.5% |  |
| ^FVX | US 5Y yield | 4.991% | −0.12% | 97.2% | |
| ^TNX | US 10Y yield | 5.118% | +0.08% | 98.6% | |
| ^TYX | US 30Y yield | 5.418% | +0.31% | 99.2% | |
| DX-Y.NYB | US Dollar Index (DXY, trade-weighted) | 101.26 | +0.16% | 91.4% |  |
Commodities
| Symbol | Description | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| GC=F | Gold | 4,314.90 | −0.08% | 30.7% |  |
| SI=F | Silver | 64.06 | −0.51% | 26.2% |  |
| CL=F | WTI Crude | 93.67 | +1.64% | 60.0% |  |
Soft Commodities (Agricultural)
| Symbol | Description | Last | Δ% | 52W pos | Seasonal (September) | Week |
|---|---|---|---|---|---|---|
| CC=F | Cocoa | 5,609.00 | +1.47% | 64.9% | S |  |
| KC=F | Coffee | 274.50 | −0.51% | 16.3% | T |  |
| ZS=F | Soybeans | 1,321.75 | +0.28% | 96.9% | T |  |
| ZC=F | Corn | 527.50 | −0.28% | 88.4% | L |  |
| ZW=F | Wheat | 704.00 | −0.64% | 74.7% | L |  |
| SB=F | Sugar | 18.80 | +5.92% | 95.4% | L |  |
| CT=F | Cotton | 83.79 | +6.18% | 73.4% | S |  |
Seasonal: L = long-biased month, S = short-biased, T = transition. Calibrated against 10y + 20y empirical futures backtest — context only.
Volatility
| Symbol | Underlying | Last | Δ% | Week |
|---|---|---|---|---|
| ^VIX | SPX | 15.98 | +5.27% |  |
| ^VXN | NASDAQ | 20.76 | +1.81% |  |
| ^GVZ | Gold | 22.77 | −2.61% |  |
| ^OVX | Crude | 53.24 | +5.82% |  |
Regime: normal (VIX-band; 15 ≤ VIX < 20).
Fear & Greed (CNN): Fear (35/100).
Sector ETFs
| Symbol | Sector | Last | Δ% | 52W pos | Week |
|---|---|---|---|---|---|
| XLK | Technology | 195.34 | +0.25% | 95.3% |  |
| XLV | Health Care | 168.80 | −0.12% | 81.8% |  |
| XLF | Financials | 54.54 | −0.47% | 62.9% |  |
| XLRE | Real Estate (S&P) | 41.84 | −1.76% | 31.4% |  |
| XLE | Energy | 62.37 | +0.96% | 84.1% |  |
| XLB | Materials | 50.28 | +1.15% | 67.8% |  |
| XLI | Industrials | 170.10 | +0.07% | 55.9% |  |
| XLU | Utilities | 39.75 | −2.24% | 0.5% |  |
| XLP | Consumer Staples | 82.43 | +0.62% | 48.5% |  |
| XLY | Consumer Disc | 110.65 | −1.41% | 27.5% |  |
| XLC | Communication Svcs | 112.56 | −1.91% | 48.9% |  |
| SMH | Semiconductors | 601.41 | −1.00% | 80.3% |  |
| GLD | Gold (ETF) | 392.88 | −1.80% | 30.1% |  |
| GDX | Gold Miners | 93.56 | −4.36% | 51.8% |  |
| XME | Metals & Mining | 109.58 | +0.53% | 47.8% |  |
| OIH | Oil Services | 395.66 | −0.24% | 70.7% |  |
| XOP | Oil & Gas E&P | 182.65 | −1.14% | 76.8% |  |
| PBW | Clean Energy | 30.47 | −1.58% | 15.5% |  |
| MOO | Agribusiness | 84.31 | +0.33% | 75.0% |  |
| IBB | Biotech | 206.60 | −0.27% | 86.6% |  |
| KRE | Regional Banks | 70.38 | −1.14% | 61.7% |  |
| KIE | Insurance | 60.09 | −2.12% | 50.8% |  |
| ITB | Home Construction | 88.79 | +0.67% | 12.6% |  |
| VNQ | REITs (broad) | 91.45 | −2.52% | 30.8% |  |
Earnings & Zacks
Reporting next ~7 sessions
| Ticker | Date | Timing | Implied move | Zacks Rank |
|---|---|---|---|---|
| BB | 2026-09-24 | PM | 11.56% | — |
| SNX | 2026-09-24 | PM | 8.46% | — |
| DRI | 2026-09-24 | PM | 6.54% | — |
| COST | 2026-09-24 | AH | 2.90% | — |
| IVA | 2026-09-25 | AH | 59.30% | — |
See you tomorrow, 60 minutes before the open.