
Traditional milestones are outdated and need to be tossed out

One thing about writing about single people and finances is I have a lot of conversations that revolve around single people. Just the other day, a financial planner said to me that he keeps meeting single people looking for planning advice. This doesn’t surprise me but it did make me wonder if the financial industry is ready for and marketing to single people. I do plan on exploring that in another newsletter.
Another thing that has crossed my desk, cropped up in conversation and rolled through my algorithm was the question of what were the adult milestones for single people.
Spite is not a retirement plan but it can help
Now financially, it’s the same, more or less, like couples: getting your first job, renting or buying your home, getting laid off, saving for vacation and/or retirement, getting your first credit card, etc. The difference is in the planning and access to tax credits and refunds. (No income splitting for us. Boo!)
What is a little more difficult is the social milestones. It’s usually coupling up, marriage, kids, seeing them grow up and leave the home, etc.
Now obviously, you’re an adult whether or not you’re coupled up or not. We’re all getting older. Using those guidelines is archaic and stupid as that isn’t the be all and end all. Thankfully they seem to slowly dying out.
But there are some very cool guidelines that definitely mean you’re an adult. Some are financial, some are community-oriented but all are important.
You have the financial security to leave a bad job, aka, the fuck-off fund.
You have a friend or core group of friends or family that you can rely on for help. I know that when I get sick, I have friends who will literally drop off soup and honey tea for me.
You take your first solo trip even if it’s a long weekend a few hours away from home.
You are a friend that people can rely on. Someone needs to get home after a colonoscopy? On it. Watch a puppy while a friend needs to run for a meeting? Give me that dog.
You have the money to help a friend out if you want to and you do it gladly without expecting to get paid back.
You have a will, an estate plan and beneficiaries.
You have some kind of savings and/or investment portfolio.
You’re thinking about elder care.
You realize you’re not waiting for your life to begin.
You’re comfortable making decisions on your own, even after soliciting opinions from your nearest and most trusted.
You’re designing the next month, year, five years, ten years of your life.
Obviously you don’t have do all of these but remember at some point in time all of us will be single, unless you were born a few hundred years ago, was royalty, betrothed at birth to your cousin, married at 18 and die at 22 from childbirth.
Milestones are only important if they’re important to you, not some list created by a bunch of randoms who decided it was important. Besides we have better things to do, like change government policies.
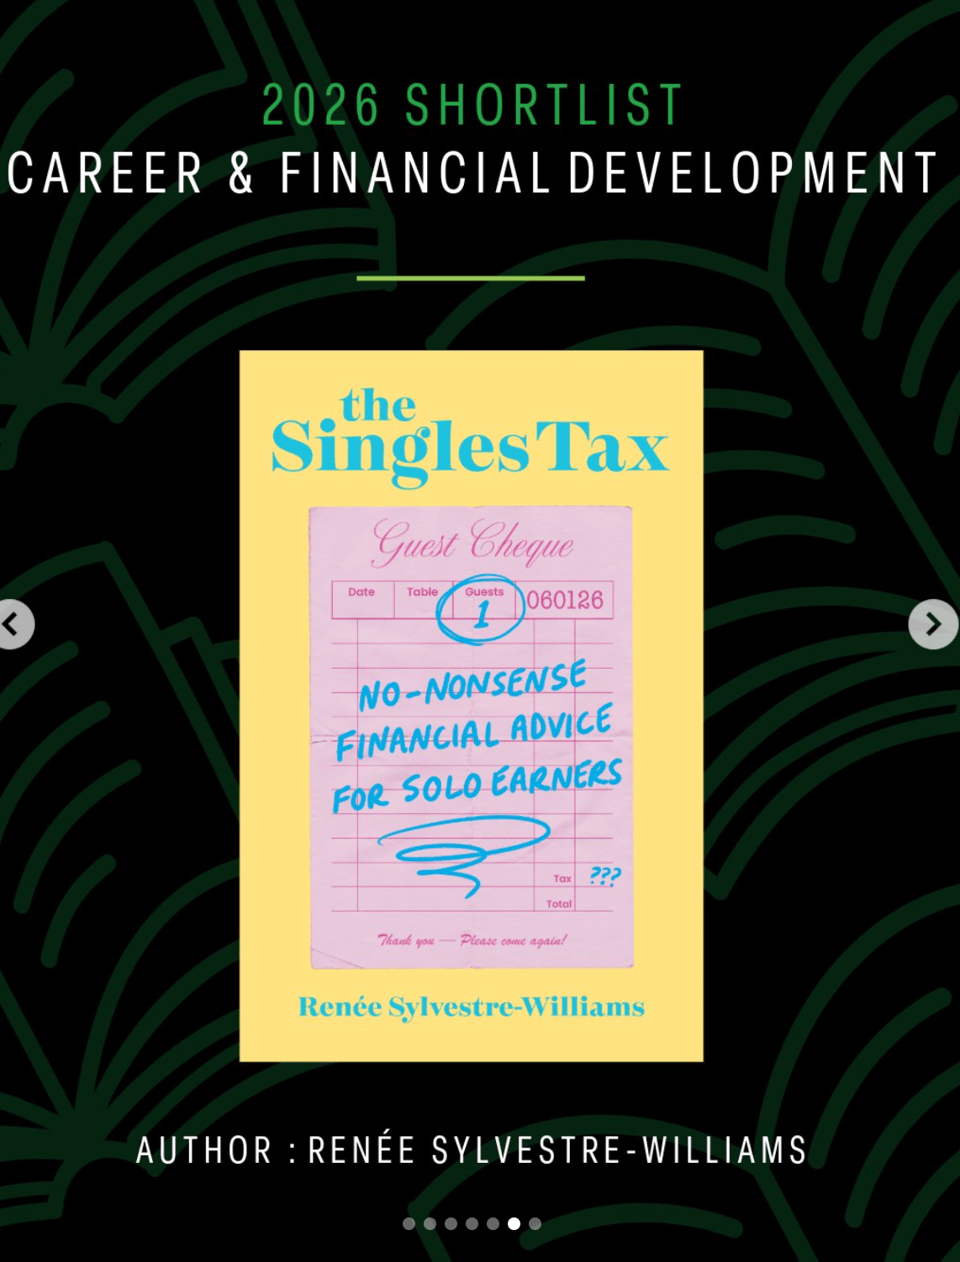
The book continues to book. My publisher and I submitted it to the Society for the Advancement of Business Editing and Writing (SABEW) for its 2026 Best in Business Book Awards. It made the shortlist, in the Career and Financial Development category. I am endlessly amused that I and Jim Cramer are in the same category.
This week’s readings:
Is divorce becoming unaffordable? (The Cut)
Personal finance pros reveal one thing they wish they knew when they were younger (MoneySense)
How does a finance independence calculator work? (The Week)
Let’s put our money where our mouths are (Indspire.ca)
And remind our government that only 15 of the Truth and Reconciliation Calls to Action have been completed. (National Centre for Truth and Reconciliation)


Add a comment: