|
Buyers paid 10.5% below net asset value for multi-asset continuation vehicles in the first half, against 4.2% in 2025. That number comes from Campbell Lutyens' half-year review of 26 August, five weeks old, and this Sunday reads it in full because the week ahead is priced on it. On Monday Partners Group Private Equity counts its realisation-share elections, and Meridiam's $4 billion-plus vehicle is in market. Single assets, meanwhile, priced at 2.9% below.
Buyers paid full value for single assets and less for portfolios
Campbell Lutyens drew its data from more than 120 buyers, and the split sits on pages 7 and 8 of its August review. First, a single-asset vehicle priced at 2.9% below net asset value on average, from 3.1% in 2025. Of those deals, 69% closed at or above value, from 57%. Second, a multi-asset vehicle priced at 10.5% below, from 4.2%, and two in three closed below value. So the gap between the two averages was one point last year and is now almost eight.
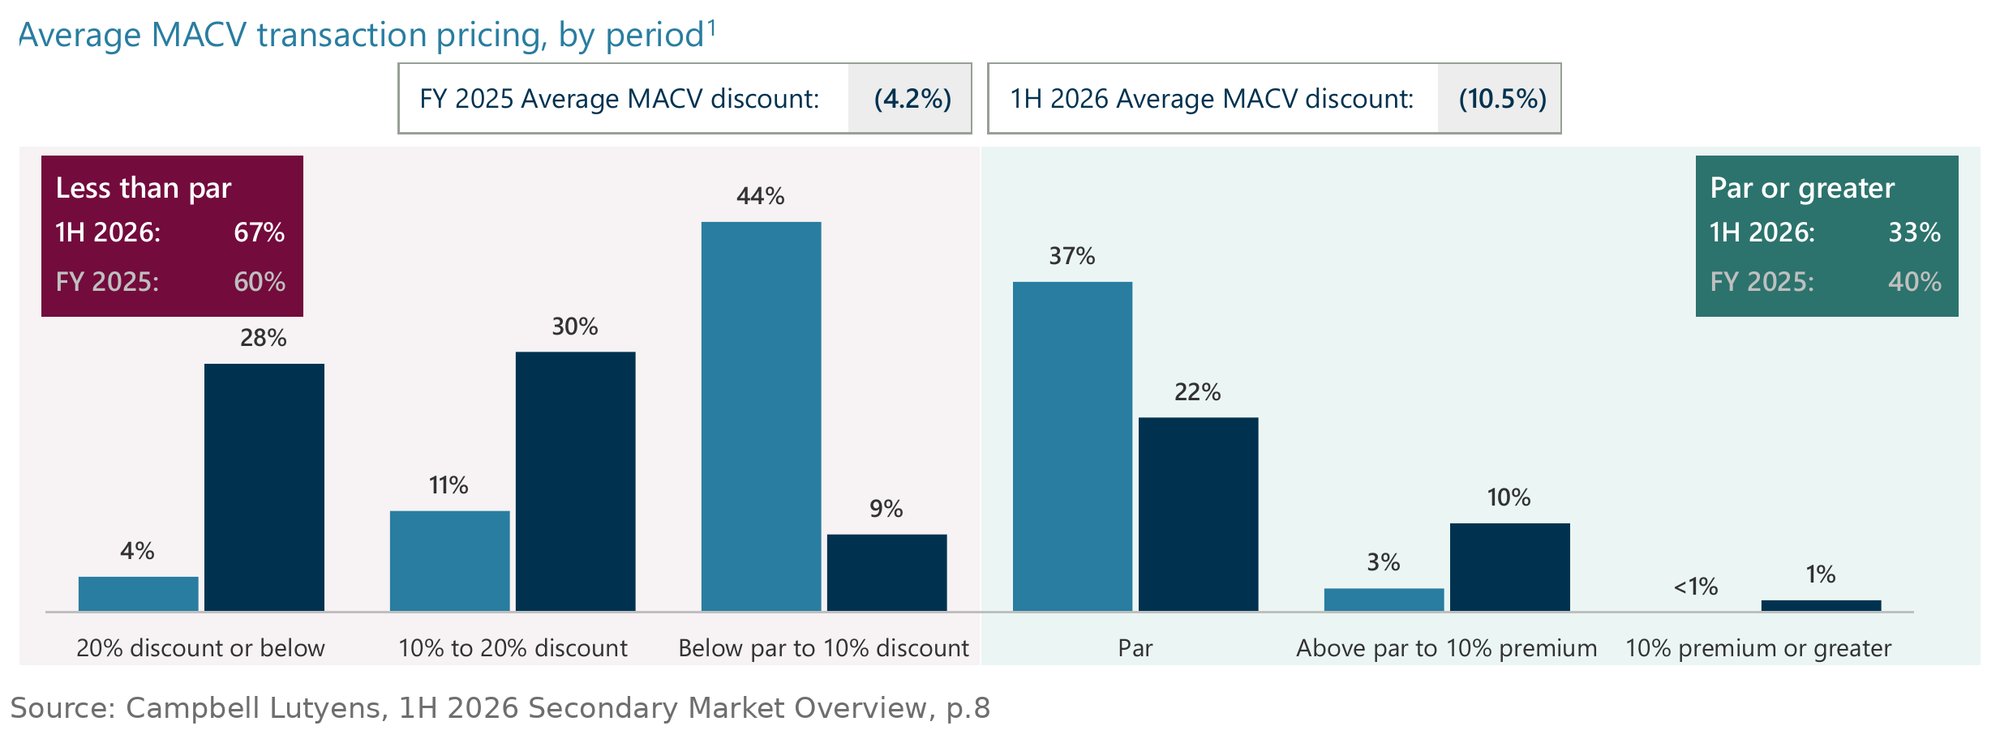 Source: Campbell Lutyens, 1H 2026 Secondary Market Overview, p.8. |
The advisor reads the widening as a change in what came to market rather than in demand. Those sponsors brought larger portfolios, and 45% of the multi-asset vehicles held eight companies or more. So buyers had to underwrite several growth profiles at once and paid less for the bundle. Meanwhile the money went to the concentrated deals, because single-asset vehicles took 62% of the $54 billion of GP-led volume, from 48%. Multi-asset volume fell from $22 billion to $19 billion. So for a sponsor planning a vehicle this autumn, the price now depends on how many companies go into it. Meridiam's vehicle is the largest test of that rule this quarter, at $4 billion-plus for infrastructure assets, read here yesterday with Ares, GIC and Pantheon behind it.
The sellers changed too. Their LP-led volume fell 8% to $54 billion, because pensions sold less as the denominator effect faded. Those pensions sold $15 billion against $23 billion a year earlier. Sovereign wealth funds filled part of the gap and rose to 20% of LP-led volume from 12%. GIC belongs to that cohort, as the seller of about $1 billion of fund interests to HarbourVest read here on Thursday. The advisor's explanation is that these funds now use the market "as a portfolio-management tool rather than a liquidity solution".
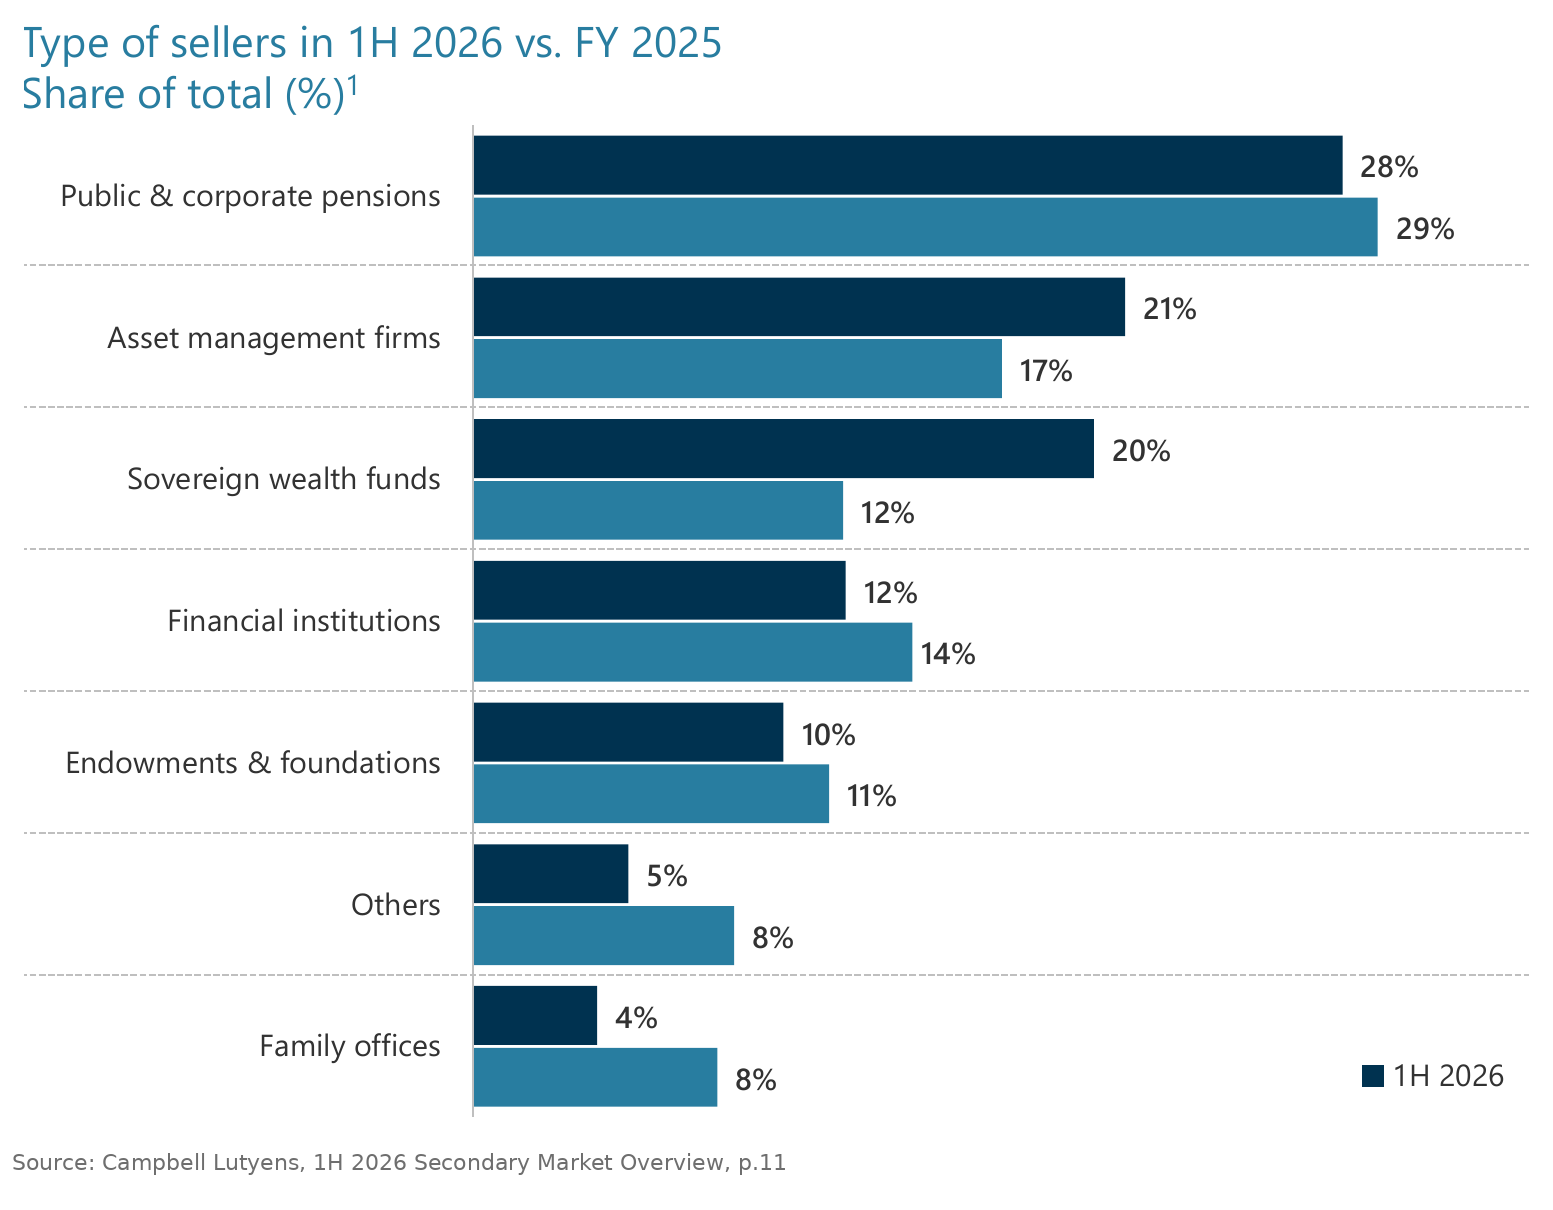 Source: Campbell Lutyens, 1H 2026 Secondary Market Overview, p.11. Dark bars are the first half of 2026, light bars the full year 2025. |
The buyers paying the most were the evergreens. Campbell Lutyens puts their average price for LP portfolios at 92.1% of net asset value, against 86.7% for the market. The gap is 540 basis points, against 334 in 2025. Those funds also sent 63% of their money to GP-led deals, from 42%. Finally, 74% of the buyers surveyed expect 2026 volume above 2025's $225 billion, and the advisor's own forecast is at least $250 billion.
Since Friday
- FILING Morgan Stanley registered on 24 September the general partner of Morgan Stanley Private Equity India CV, the $500 million healthcare vehicle Bloomberg reported in February.
- DEAL NewView Capital and Carta said on 22 September they will run company tender offers. Carta ran 70-plus tenders worth $3 billion in the first half.
- LP CalSTRS holds one continuation vehicle after all, TRF IV CFS Continuation Fund, at 1.1x in a 23 September fee report, missed here on 20 September.
- LP Schroders Capital Global Innovation Trust's holders tendered 72% of its shares on 25 September for a £28 million buyback at the 30 June value.
-
On the radar, the week of 5 October
- Monday 5 October, Guernsey. Partners Group Private Equity publishes the result of its realisation-share election, which closed on Friday. Elections above 40% of the shares lapse the proposal and start a managed wind-down of the whole portfolio, the circular says. Meanwhile the trust extended its buyback to 31 October with about €5 million left.
- Monday 5 October, Washington. The SEC's interval fund proposal is published in the Federal Register, so comments are due by 4 December. The monthly repurchase option and the two-year deferral of a first offer, read here on Thursday, are the terms the evergreens that buy secondaries will argue over.
- Wednesday 7 October, 11am, Guernsey. Partners Group Private Equity's EGM votes on the two share classes at Trafalgar Court. A large realisation class makes a listed seller of fund interests in the fourth quarter.
- October, Guernsey. HarbourVest Global Private Equity publishes the timetable of its $400 million tender with its half-year results, priced around 10% below the 30 September value for a November offer.
- Thursday 22 October, 9am, New York. Blackstone's third-quarter call, the first since it shelved Eclipse, read here on 24 September.
-
|