|
Sponsors in the US hold more than $860 billion of buyout net asset value in funds older than seven years, PitchBook counts in a note of 17 August. The 2021 vintage has returned 0.14x by the end of its fourth year. The note names the secondary buyer as the party that prices these assets, so I read all 22 pages. The week then opens in Singapore and ends on the quarter-end mark.
PitchBook counts the zombies and names their buyers
PitchBook's analysts have put a number on the assets the secondary market spent September pricing. Kyle Walters and Harrison Waldock count 13,509 companies in US sponsor portfolios in their note of 17 August. Of those, 2,536 are past the usual exit window. The net asset value in buyout funds older than seven years is above $860 billion, about 40% of the total. Walters and Waldock single out the 2021 vintage, which has returned 0.14x by the end of its fourth year. It bought at peak multiples with debt at 5% to 6% that now costs 9% to 11%, so 1,869 of roughly 2,500 platform buyouts that year are still held.
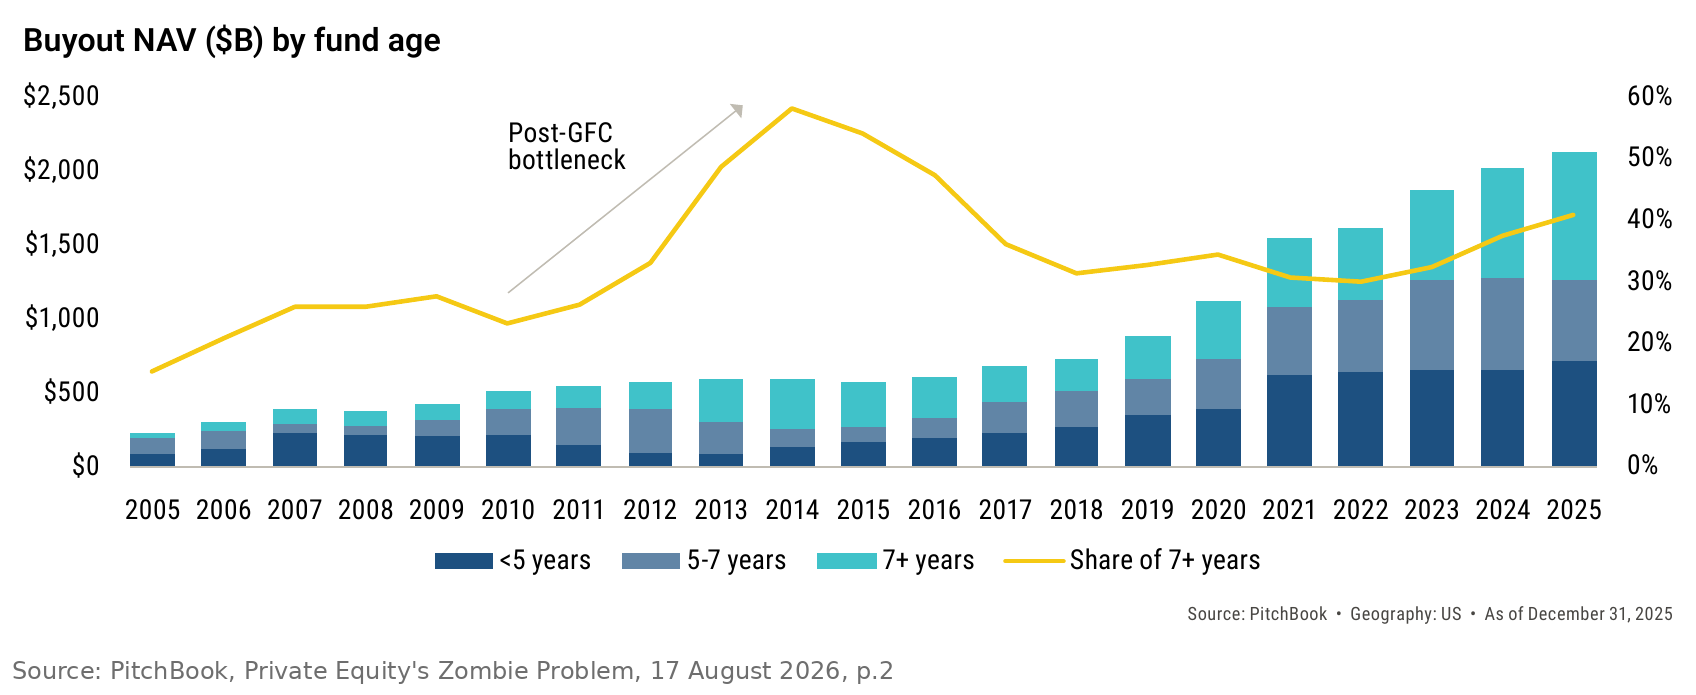 Source: PitchBook, Private Equity's Zombie Problem, 17 August 2026, p.2. |
The authors read the continuation vehicle as the industry's way of keeping those companies rather than selling them. They count continuation-fund exits at 2 in 2016, 158 in 2025 and 69 in the first half of this year. In their words, "CVs are both a symptom of the zombie problem and a tool for managing it". A vehicle priced below the sponsor's carrying value, by buyers who did their own work, is "a quiet but telling acknowledgment that the mark was optimistic". They will watch for more vehicles out of the 2018 to 2022 vintages over the next two to three years. More of them would mean the problem is being moved rather than solved.
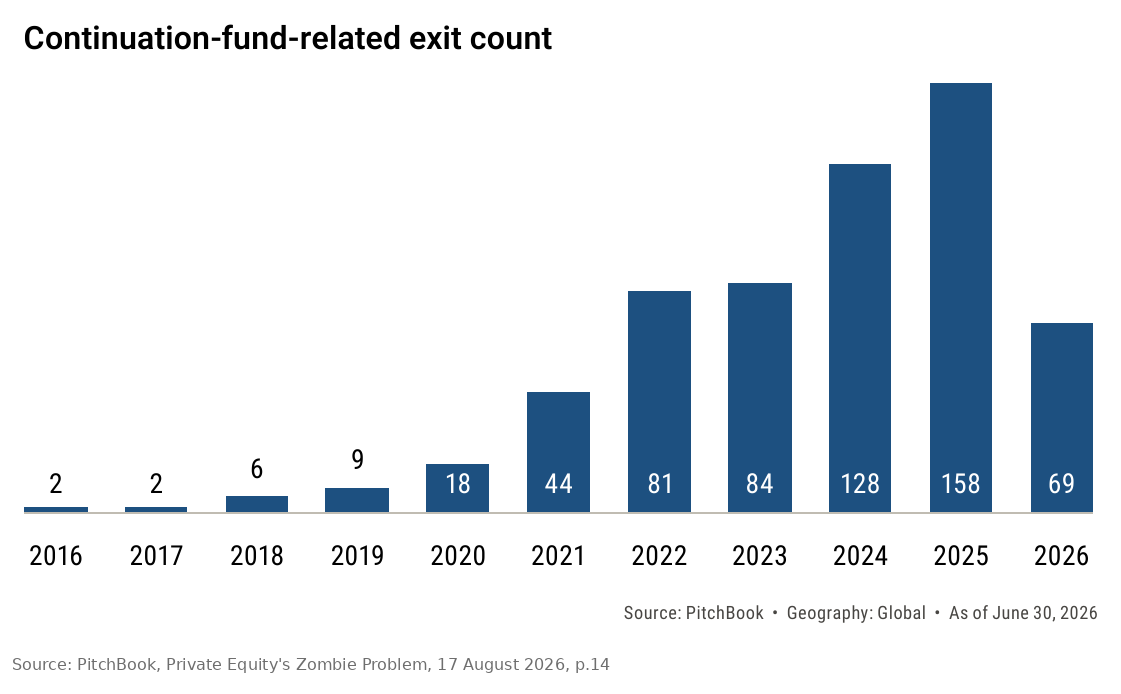 Source: PitchBook, Private Equity's Zombie Problem, 17 August 2026, p.14. |
The buyers are named in the last pages, as the ones who gain. The note calls secondary investors "among the most direct beneficiaries of the zombie dynamic". Their "pricing leverage increases precisely when sponsors are most motivated to transact and least able to demand full value". September gave the evidence, since Blackstone found no bid for the oldest quarter of the 700 funds in its Eclipse securitization, read here on Thursday. Jefferies, meanwhile, had tail-end funds among the strategies that price at wider discounts, read on Saturday.
So an investor holding 2018 to 2021 buyout funds has a screen to run before the sponsor's vehicle arrives. PitchBook's test is two of three signs together, which are no deal of any kind since the end of 2021, flat revenue and a shrinking headcount. On the first sign alone, 3,332 of the companies held five years or more fail. That investor can sell the fund interest now, at the 91% of net asset value Jefferies prints for buyout. Or it can wait for a continuation vehicle whose price the same buyers will set. Walters and Waldock end on the share of exits sold to another sponsor in the first quarter, 53.5% of them.
Since Friday
- DATA HarbourVest puts 2018 to 2021 vintages "roughly one year behind" on DPI in its outlook, a theme Scott Voss took to Alternatives Watch on Friday.
- DATA Secondaries Investor wrote on Friday that Asia-Pacific deals remain "far and few between", while KIC is selling more than $1 billion of fund interests.
- DATA Secondaries Investor also wrote on 17 September that buyers are doubling down through CV-on-CV deals, "bringing price discovery and other potential conflicts into sharper focus".
-
On the radar, the week of 28 September
- Monday 28 September. Responses are due to CrossBoundary's call for a manager of a pan-African secondary fund of $100 million to $200 million. GIZ's ICAMA initiative prefers a GP-led or hybrid mandate.
- Tuesday 29 September, Singapore and New York. SuperReturn Asia holds its one secondaries session at 12:25, with Adams Street's Pinal Nicum among the speakers. In New York, ILPA's Continuation Vehicles for the Limited Partner course meets the day before quarter-end.
- Wednesday 30 September, 10am, Washington. The SEC's open meeting votes on proposing the interval fund and multiple share class amendments, the rulebook for the wealth feeders filed all month.
- Wednesday 30 September, 1pm, Guernsey. The deadline for Partners Group Private Equity's shareholders to elect realisation shares, with the EGM on 7 October. A large election makes a listed seller of fund interests in the fourth quarter.
- Wednesday 30 September, quarter-end. Every process launched in October, Yale's and KIC's included, is priced on the 30 September mark. Anthropic's prospectus was expected by the end of the month, Reuters reported, with marketing in mid-October.
- To Thursday 15 October. Corporate pension plans file their Form 5500 for 2025, every fund interest at cost and value. A fund that left a schedule with value in it is a sale.
-
|